
Executive summary:
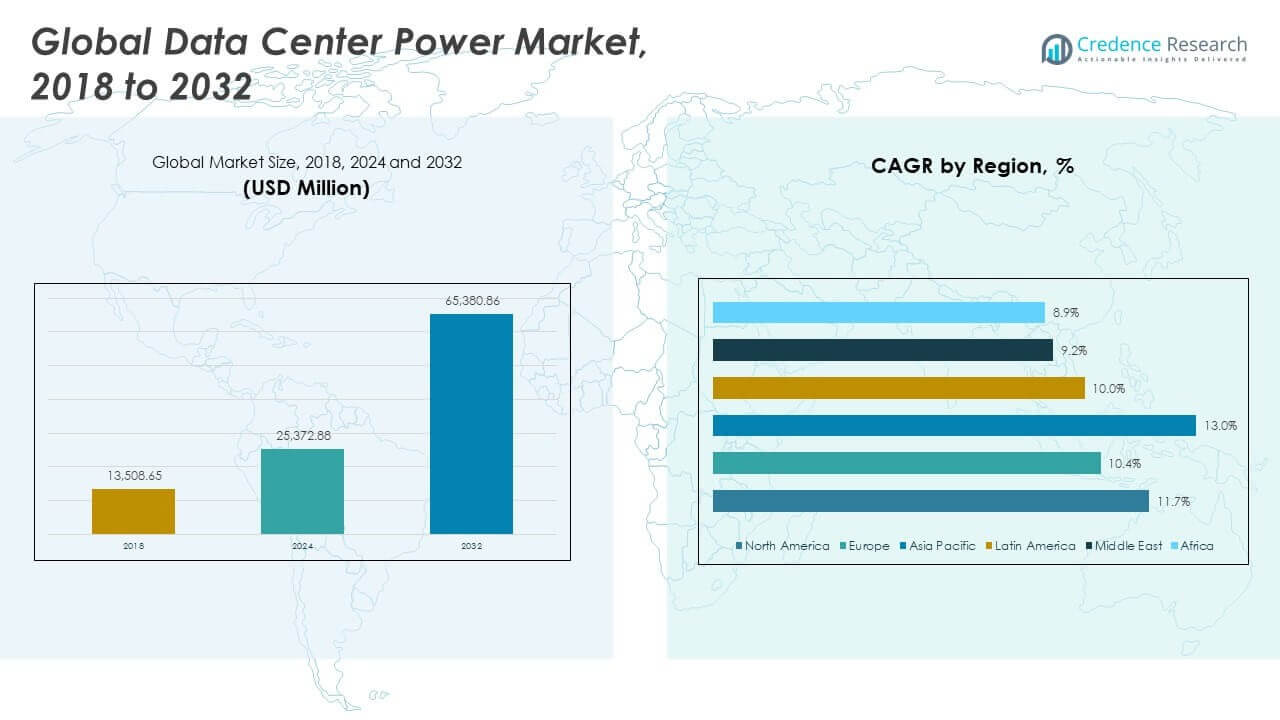
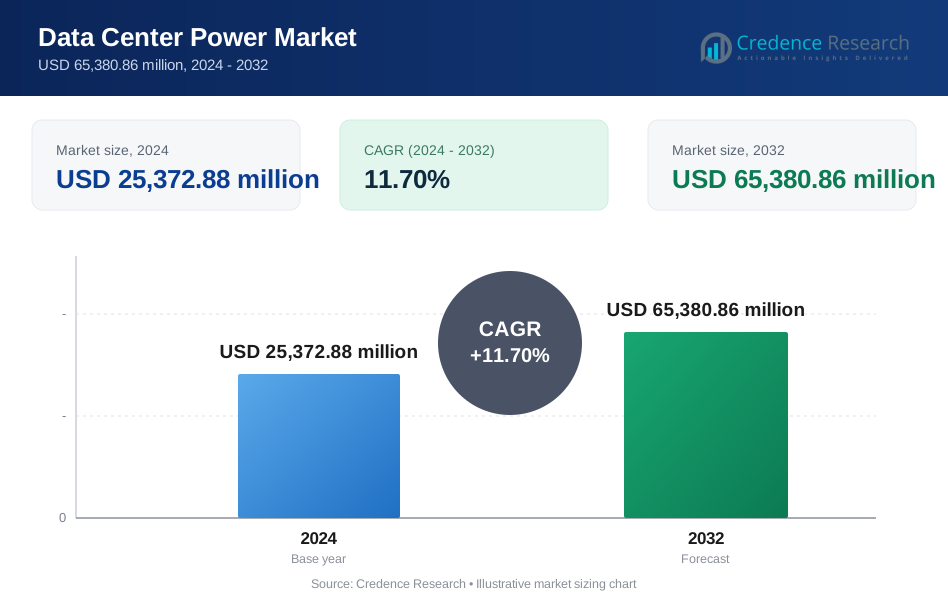
The Global Data Center Power Market size was valued at USD 13,508.65 million in 2018 to USD 25,372.88 million in 2024 and is anticipated to reach USD 65,380.86 million by 2032, at a CAGR of 11.70% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Data Center Power Market Size 2024 | USD 25,372.88 million |
| Data Center Power Market, CAGR | 11.70% |
| Data Center Power Market Size 2032 | USD 65,380.86 million |
Surging cloud adoption, edge computing, and AI workloads are fueling demand for scalable power infrastructure. Operators are deploying advanced UPS systems, intelligent PDUs, and modular power units to improve reliability and energy efficiency. Growth in hyperscale data centers is reshaping procurement strategies toward sustainability and grid independence. Innovations like lithium-ion batteries, hybrid backup systems, and smart power monitoring platforms are critical to meet evolving data processing needs. The Global Data Center Power Market supports long-term digital transformation goals for businesses and presents attractive returns for investors.
North America holds the largest share of the Global Data Center Power Market, led by early adoption of hyperscale campuses and AI infrastructure. Europe follows with a focus on sustainable and energy-efficient data centers. Asia Pacific is the fastest-growing region due to rising digital demand in China, India, and Southeast Asia. Latin America and the Middle East show steady growth with government support and increasing cloud investments. Africa remains in early development but shows future promise through mobile-first digitalization and localized power innovations.
Market Dynamics:
Market Drivers
Rising Integration of Energy-Efficient Power Systems in Data Centers
The Global Data Center Power Market benefits from growing investments in energy-efficient power infrastructure. Operators are deploying advanced UPS systems, precision cooling units, and power distribution units with real-time monitoring. These systems lower operational costs and help meet sustainability targets. Energy management platforms using AI enhance power usage effectiveness. High electricity costs are pushing companies to adopt low-loss transformers and intelligent switchgear. Governments support this shift through energy compliance mandates. Enterprises view efficiency upgrades as long-term cost savers. The market gains strategic importance through these modernization efforts. It provides a foundation for future-ready and reliable data ecosystems.
- For instance, CyberPower's intelligent PDUs achieve ±1% measurement accuracy for current, wattage, voltage, and frequency metering across connected devices.
Increased Demand for Scalable Power Solutions to Support Hyperscale Growth
Hyperscale data centers require scalable and modular power systems to meet massive computing demands. Operators prefer plug-and-play infrastructure that allows phased expansion with minimal downtime. High-density server racks need customized power support with reliable load balancing. Power architecture now plays a central role in data center design planning. The Global Data Center Power Market supports this shift by offering flexible components and control systems. It addresses both capital efficiency and resilience in large-scale environments. Cloud providers rely on scalable power to maintain uptime SLAs. The demand for hyperconnectivity drives rapid deployment cycles. Investors see this infrastructure layer as critical to future digital economies.
Technology-Driven Shifts Toward Renewable and Hybrid Power Integration
The integration of solar panels, fuel cells, and battery energy storage into data centers drives new growth. Operators aim to reduce reliance on conventional grid supply and diesel generators. Hybrid power setups ensure uninterrupted operations during outages and peak demand. Smart grids and microgrid configurations enable load optimization and carbon footprint reduction. The Global Data Center Power Market aligns with ESG priorities through these clean energy strategies. Technological maturity in inverters and control software supports transition feasibility. Multinational operators pilot green campuses in key regions. This shift improves brand image and aligns with green building certifications. It enables long-term compliance with environmental regulations.
- For instance, EkkoSoft Critical's real-time analytics monitor power consumption across racks and facilities to detect abnormal patterns early.
Critical Need for Intelligent Power Monitoring and Fault Management Tools
Power management is evolving beyond hardware, focusing on software-enabled visibility and control. Operators deploy DCIM systems, smart meters, and AI tools for predictive fault diagnostics. These tools minimize downtime and avoid thermal stress on power components. Advanced analytics offer granular insights into energy consumption by rack or module. The Global Data Center Power Market benefits from the growing need for real-time performance insights. Operators prioritize early fault identification to prevent cascading failures. AI and machine learning models offer adaptive control and energy savings. These capabilities support autonomous data center management initiatives. Businesses adopt such tools to enhance uptime and operational confidence.
Market Trends
Growing Preference for Lithium-Ion UPS Systems over Traditional VRLA Units
Operators are replacing VRLA-based UPS systems with lithium-ion alternatives across new and existing facilities. Lithium-ion batteries offer longer life, higher energy density, and reduced maintenance. These benefits improve TCO and reduce space requirements in dense environments. Adoption rates grow in hyperscale and colocation facilities with high uptime demands. The Global Data Center Power Market tracks this shift as vendors scale production and lower costs. Regulatory support for clean battery tech also supports this trend. Operators evaluate battery chemistries based on safety, efficiency, and footprint. Longer service intervals lower operating risk. The transition supports sustainability and performance goals simultaneously.
Deployment of Liquid Cooling Systems Influencing Power Architecture
Liquid cooling adoption in high-performance environments changes data center power distribution planning. These systems reduce air cooling demand and shift thermal load away from raised floors. Power components now support higher rack densities and localized energy use. The Global Data Center Power Market adapts with integrated power-cooling packages. Efficient pump systems, heat exchangers, and control circuits gain demand. AI workloads and HPC clusters drive demand for these systems. Colocation providers align designs to support next-gen tenant hardware. Liquid cooling improves power efficiency at the rack level. This trend accelerates where AI and graphics processing dominate server loads.
Edge Data Centers Driving Demand for Compact, Modular Power Systems
Edge computing expands data processing closer to end users, requiring decentralized power infrastructure. These micro data centers need compact UPS, PDUs, and battery systems with remote control capabilities. Power systems are designed for rapid deployment, minimal maintenance, and low footprint. The Global Data Center Power Market responds by offering scalable power kits optimized for edge locations. Telecom players and enterprises integrate these solutions into smart city, 5G, and IoT frameworks. Modular setups allow operators to install plug-in units at underserved sites. Integration with renewable sources ensures resilience in remote areas. The market supports edge expansion by simplifying power provisioning.
Adoption of Software-Defined Power and AI-Based Load Management
Software-defined power platforms automate power provisioning based on demand fluctuations. AI models predict energy needs across clusters and optimize load distribution. These platforms reduce overprovisioning and enhance operational agility. Enterprises use such tools to meet sustainability and uptime KPIs. The Global Data Center Power Market reflects rising demand for predictive control solutions. Software intelligence reduces energy waste across non-peak cycles. Data centers integrate these systems with broader DCIM tools. Software-defined control also supports auto-failover in case of component faults. These capabilities align with autonomous and self-healing data center architectures.
Market Challenges
High Capital Costs and Long ROI Cycles for Advanced Power Infrastructure
Advanced power systems such as lithium-ion UPS, solid-state transformers, and fuel cells come at premium costs. Smaller operators struggle to justify high upfront investments with long payback periods. Budget constraints delay upgrades in legacy facilities. Procurement decisions are often weighed against immediate capacity needs. The Global Data Center Power Market faces resistance from businesses seeking short-term cost optimization. Training and integration costs add further complexity. Power system design also requires specialist expertise and long planning cycles. These barriers slow adoption across mid-tier and small-scale deployments. Market growth depends on lowering cost thresholds and improving ROI clarity.
Grid Dependency, Supply Chain Volatility, and Regulatory Uncertainty
Many regions face unreliable grid access or regulatory bottlenecks around new data center construction. Power grid constraints delay site approvals and limit redundancy planning. Supply chain disruptions affect timely delivery of transformers, circuit breakers, and smart meters. The Global Data Center Power Market experiences volatility in raw material availability, especially for battery components. Regulatory gaps around energy usage caps or emissions targets create planning uncertainty. Operators struggle with inconsistent environmental compliance norms across regions. Import restrictions on critical equipment further challenge project timelines. These risks impact capacity planning, especially in emerging data center hubs.
Market Opportunities
Growth of Greenfield Data Center Investments in Emerging Economies
Emerging regions in Asia, Africa, and Latin America offer untapped opportunities for modern data center power deployment. New projects often adopt high-efficiency systems from the start. Operators plan facilities around renewable integration and hybrid power models. The Global Data Center Power Market benefits as local governments support digital infrastructure expansion. Economic digitization drives cloud adoption, 5G rollout, and colocation demand. These investments require resilient and scalable power systems to support future loads. Market players can target early-mover advantage in these geographies.
Rising Interest in Renewable Energy Partnerships and Power Purchase Agreements
Operators actively pursue long-term green energy supply through power purchase agreements and on-site generation. These models ensure energy cost predictability and meet sustainability mandates. Solar, wind, and fuel cells reduce dependency on fossil fuels. The Global Data Center Power Market finds new value in these collaborative supply frameworks. Technology partnerships and energy-as-a-service models expand adoption. Investors view such initiatives as ESG-aligned and risk-diversified.
Market Segmentation:
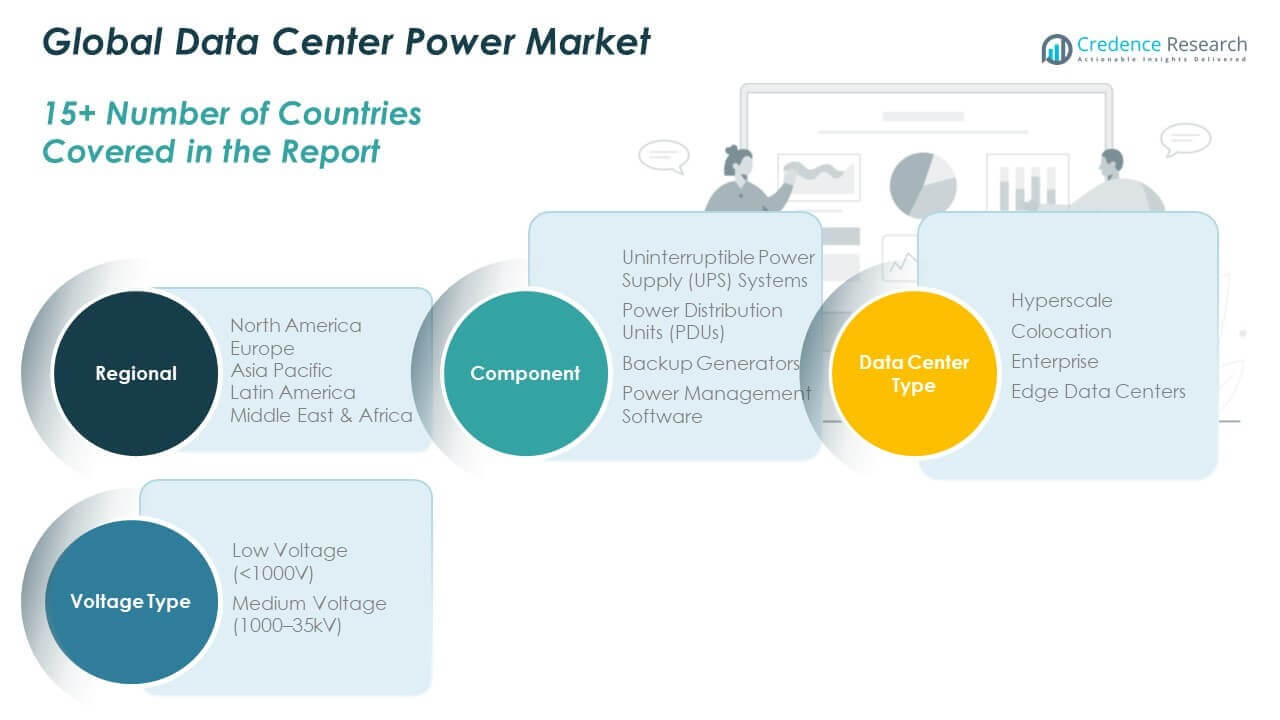
Component Segmentation The Global Data Center Power Market is led by the Uninterruptible Power Supply (UPS) systems segment, holding the largest revenue share. UPS systems remain mission-critical for ensuring zero downtime during power disruptions, especially in hyperscale and colocation environments. The rise of lithium-ion batteries and modular UPS designs further accelerates adoption. Operators prefer UPS systems with scalable capacity and remote monitoring capabilities. Growth in AI and high-density computing boosts demand for efficient backup power. Investments in smart UPS infrastructure enhance data center resilience. Market leaders focus on low-maintenance, high-efficiency units. The segment benefits from strong replacement demand in mature regions.
Data Center Type Segmentation In the Global Data Center Power Market, hyperscale data centers represent the dominant segment, driven by major cloud providers and tech giants. These facilities require large-scale, redundant power systems with high-density load support. Rapid adoption of AI, machine learning, and real-time analytics increases their power intensity. Operators invest in modular and scalable power solutions to match phased deployments. Hyperscale campuses demand high-availability infrastructure with advanced monitoring and automation. The need for sustainable power sourcing further shapes purchasing decisions. Growth in global cloud consumption continues to fuel capacity expansion. Hyperscale providers often adopt direct power procurement agreements. Their design choices influence innovation across the supply chain.
Voltage Type Segmentation
The low voltage segment dominates the Global Data Center Power Market due to its widespread use in server racks, PDUs, and IT load distribution. Most data centers follow standardized low-voltage architectures to ensure safety, interoperability, and ease of maintenance. This segment benefits from high deployment volume across edge, enterprise, and colocation facilities. Operators prefer low-voltage systems for their flexibility, lower equipment cost, and ease of integration. Innovations in power modularity and rack-level distribution reinforce its relevance. While medium voltage supports high-load infrastructure, low voltage remains the foundation of facility-wide deployment. Its scalability and design maturity make it the first choice for both new builds and upgrades.Regional Insights:
North America
The North America Global Data Center Power Market size was valued at USD 6,047.28 million in 2018 to USD 11,243.36 million in 2024 and is anticipated to reach USD 29,050.35 million by 2032, at a CAGR of 11.7% during the forecast period. North America holds the largest market share at 44.3% in 2024, driven by rapid hyperscale data center expansion in the U.S. and Canada. Major cloud providers and colocation operators invest heavily in advanced power infrastructure. The region benefits from mature grid infrastructure, strong digital adoption, and favorable tax incentives. Lithium-ion UPS systems and smart PDUs gain widespread use in Tier III and IV data centers. Rising AI workloads push demand for high-density power solutions. Sustainability goals drive interest in renewable-powered campuses and PPAs. Regulatory frameworks encourage efficient and modular power system upgrades. The market remains highly competitive with strong vendor presence and R&D investments.
- For example, Schneider Electric offers the EcoStruxure Micro Data Center, a pre‑engineered solution that integrates power, cooling, and management for edge and small‑scale facilities. This product supports rapid deployment and improved operational efficiency in distributed IT environments.
Europe
The Europe Global Data Center Power Market size was valued at USD 2,613.25 million in 2018 to USD 4,648.89 million in 2024 and is anticipated to reach USD 10,933.16 million by 2032, at a CAGR of 10.4% during the forecast period. Europe accounts for 18.3% of the market share in 2024, with strong activity in Germany, the UK, the Netherlands, and France. The region emphasizes green data centers and low-carbon energy integration. Operators align with EU regulations on energy efficiency and emissions reduction. Liquid cooling, smart grid compatibility, and modular power designs see higher adoption. Edge and micro data centers grow in Eastern Europe and Nordics. Strong cross-border connectivity and digital transformation projects support infrastructure growth. Rising AI and HPC workloads contribute to higher energy needs. Governments and enterprises collaborate on cloud sovereignty and sustainable data ecosystems. The market attracts steady investment from both global and regional players.
Asia Pacific
The Asia Pacific Global Data Center Power Market size was valued at USD 3,615.59 million in 2018 to USD 7,200.44 million in 2024 and is anticipated to reach USD 20,361.24 million by 2032, at a CAGR of 13.0% during the forecast period. Asia Pacific represents 28.4% of the market share in 2024, led by strong demand in China, India, Japan, and Southeast Asia. Rapid urbanization, cloud growth, and digital economy expansion drive new data center builds. Hyperscale operators target regional hubs for large-scale campuses. Governments support investment through tax benefits, power access, and land approvals. Colocation and edge data centers are expanding in second-tier cities. The market embraces power-efficient and cost-optimized systems to manage grid challenges. Local utilities and tech companies form joint ventures for green energy sourcing. High population density and mobile usage fuel content delivery and data processing needs. This region holds strong momentum in both deployment and innovation.
Latin America
The Latin America Global Data Center Power Market size was valued at USD 638.07 million in 2018 to USD 1,183.58 million in 2024 and is anticipated to reach USD 2,699.40 million by 2032, at a CAGR of 10.0% during the forecast period. Latin America holds 4.7% of the market share in 2024, with Brazil and Mexico being the dominant markets. Regional data sovereignty, cloud demand, and enterprise digitization stimulate investment. Power infrastructure is gradually improving across key metro areas. Operators focus on UPS redundancy, energy-efficient cooling, and automation. Challenges include energy pricing volatility and uneven grid reliability. The market sees growing interest in modular power systems for edge deployments. Regulatory clarity and fiber backbone upgrades enhance market potential. Local and international players expand footprints to meet rising demand from financial services, e-commerce, and content streaming sectors.
- For instance, Huawei’s SmartLi UPS deployment with 21Vianet reduced the physical footprint by around 50% and achieved roughly double the battery lifespan compared with traditional lead‑acid systems in modular data center power applications.
Middle East
The Middle East Global Data Center Power Market size was valued at USD 355.89 million in 2018 to USD 607.39 million in 2024 and is anticipated to reach USD 1,303.60 million by 2032, at a CAGR of 9.2% during the forecast period. The region contributes 2.4% to the 2024 market share, led by the UAE, Saudi Arabia, and Israel. Strong government support for digital hubs and smart city projects accelerates infrastructure growth. Colocation and managed service providers expand capacity to meet rising enterprise needs. Operators invest in resilient power backup, solar integration, and grid synchronization. GCC countries promote energy-efficient data center certifications. Geopolitical stability and business-friendly regulations attract hyperscale investments. Greenfield projects with high-load capacity demand smart PDUs and scalable UPS units. The region moves toward hybrid cloud and edge expansion, pushing localized power demand.
Africa
The Africa Global Data Center Power Market size was valued at USD 238.57 million in 2018 to USD 489.23 million in 2024 and is anticipated to reach USD 1,033.12 million by 2032, at a CAGR of 8.9% during the forecast period. Africa holds a 1.9% market share in 2024, with South Africa, Nigeria, Egypt, and Kenya being key contributors. Power reliability and grid access remain primary concerns in infrastructure planning. Operators rely on diesel and hybrid energy systems to ensure uptime. Regional cloud expansion and mobile connectivity growth spur demand for edge data centers. Governments prioritize digital inclusion and smart infrastructure programs. International cloud providers establish new facilities and partnerships to tap into emerging demand. UPS systems, backup generators, and modular power solutions see rising adoption. Strong growth is expected in fintech, healthcare, and e-commerce sectors. The market is in early stages, with long-term potential anchored in urban digitalization.
Competitive Insights:
- Schneider Electric
- Vertiv
- Eaton
- ABB
- Huawei
The competitive landscape of the Global Data Center Power Market reflects strong rivalry among a focused group of global leaders with broad solution portfolios. Schneider Electric, Vertiv, and Eaton lead through deep expertise in UPS systems, power distribution, and integrated energy management platforms. These companies emphasize modular, scalable architectures that support hyperscale, colocation, and edge deployments. ABB strengthens its position through advanced low- and medium-voltage solutions tailored for high-density facilities. Huawei leverages strong engineering capabilities and global reach to supply end-to-end power infrastructure, particularly in emerging markets. Price competitiveness, system reliability, and lifecycle service quality influence buyer decisions. Vendors invest in product upgrades that improve efficiency and resilience. Strategic partnerships with data center operators support long-term contracts. It remains competitive through continuous technology refinement and solution differentiation.
Recent Developments:
- In November 2025, Schneider Electric announced a major partnership expansion with Switch involving a $1.9 billion supply capacity agreement for prefabricated power modules and the first U.S. deployment of Uniflair chillers to support AI-driven data centers.
- In November 2025, ABB expanded its partnership with Applied Digital supplying medium voltage power technology for a 300 MW AI factory campus expansion in North Dakota. In May 2025, ABB introduced the PowerValue 11RT G3 and PowerValue 33T G2 UPS systems for edge and enterprise data center use.
- In November 2025, Schneider Electric sealed two major deals with US data center operators, expected to generate nearly $2.3 billion in sales to power the AI boom. This partnership underscores the surging demand for advanced power infrastructure amid rapid data center expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Data Center Power Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Data Center Power Market projected to grow between 2024 and 2032?
Which Data Center Power Market segment held the largest share in 2024?
Who are the leading companies in the Data Center Power Market?
Which Global Data Center Power Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Data Center Power Market?
Who are the leading companies in the Global Data Center Power Market?
Which region commanded the largest share of the Global Data Center Power Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,372.88 million → 2032: USD 65,380.86 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Center Power Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Center Power Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Center Power Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Center Power Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Center Power Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Center Power Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Center Power Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Center Power Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,372.88 million → 2032: USD 65,380.86 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Center Power Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Center Power Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Data Center Power Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Data Center Power Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

