
Market Overview
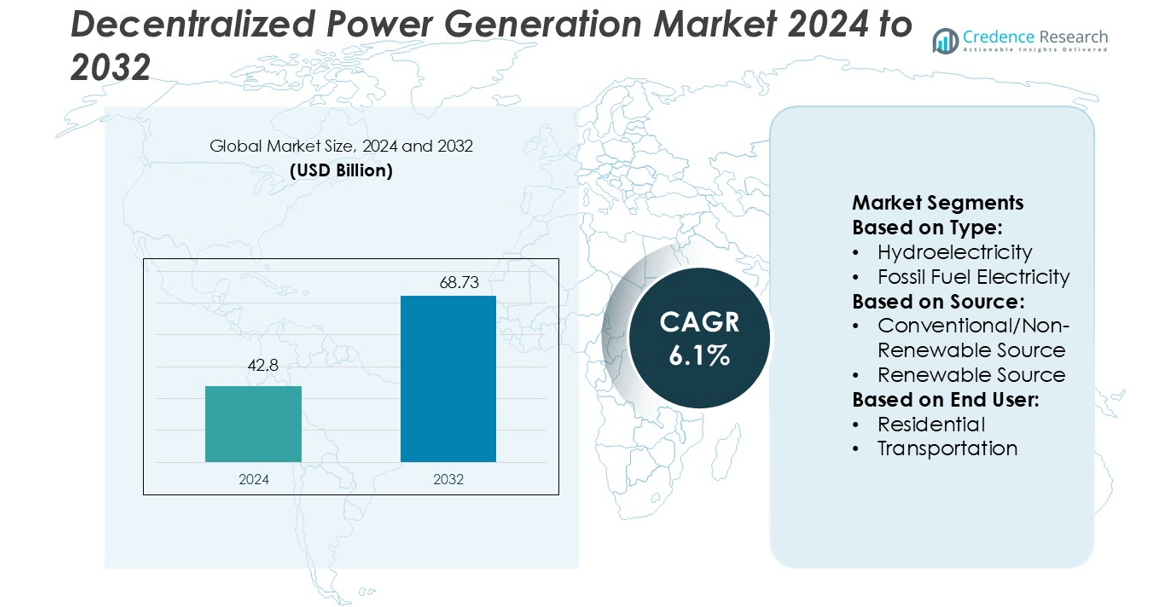
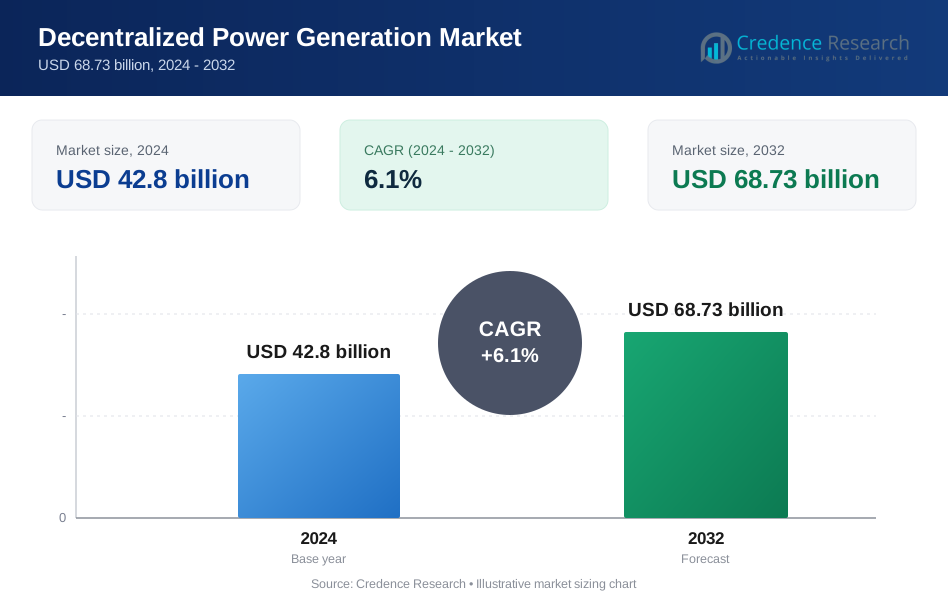
Decentralized Power Generation Market size was valued USD 42.8 billion in 2024 and is anticipated to reach USD 68.73 billion by 2032, at a CAGR of 6.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Decentralized Power Generation Market Size 2024 | USD 42.8 billion |
| Decentralized Power Generation Market, CAGR | 6.1% |
| Decentralized Power Generation Market Size 2032 | USD 68.73 billion |
The decentralized power generation market is driven by major players including S&C Electric Company, Seeo, Inc., SMA Solar Technology AG, Greensmith Energy Management Systems, ABB Ltd., Schneider Electric, Beacon Power, LLC, Convergent Energy and Power Inc., Eos Energy Storage, and BYD Company Ltd. These companies lead in solar integration, advanced inverters, battery storage, and smart grid technologies. Their strategic investments in hybrid systems and digital platforms strengthen operational efficiency and market reach. Asia Pacific dominates the market with a 33.8% share, supported by large-scale renewable deployments, rapid urbanization, and strong government incentives. Continuous innovation and expanding project portfolios from these key players further accelerate the transition toward sustainable and decentralized energy infrastructure globally.
Market Insights
- The decentralized power generation market size was valued at USD 42.8 billion in 2024 and is projected to reach USD 68.73 billion by 2032, growing at a CAGR of 6.1%.
- Rising renewable adoption, energy security needs, and government incentives are driving strong demand across industrial, commercial, and residential sectors.
- Asia Pacific leads the market with a 33.8% share, supported by rapid urbanization, large-scale renewable deployments, and favorable policies, followed by North America and Europe.
- Solar electricity holds the largest segment share, driven by falling equipment costs, flexible installation options, and expanding hybrid projects.
- Strong competition among key players focuses on advanced inverters, battery storage, and digital grid solutions, while high initial capital costs and regulatory hurdles remain key restraints.
Market Segmentation Analysis:
By Type
Solar electricity dominates the decentralized power generation market with a 33.5% share in 2024. Strong adoption is driven by falling photovoltaic costs, quick installation, and low operational expenses. Solar systems enable off-grid power generation and reduce dependency on centralized grids. Government incentives and net metering schemes boost adoption across rural and urban areas. Wind electricity holds the second-largest share, supported by large-scale onshore deployments. Hydroelectricity and biomass electricity also show steady growth due to stable generation capacity and sustainable energy policies.
- For instance, SMA’s Sunny Central FLEX inverter was awarded “PV Magazine Top Innovation 2024” for achieving rated power over 1,500 kW in a compact footprint. SMA’s inverters installed through the past 20 years reach a cumulative output of 132 GW, preventing over 70 million tons CO₂ emissions.
By Source
Renewable sources lead the decentralized power generation market with a 67.4% share in 2024. This growth is supported by global clean energy targets, feed-in tariffs, and rising energy security concerns. Solar, wind, and hydro power form the core of decentralized renewable generation. Declining equipment costs and improved storage solutions strengthen grid independence. Conventional sources, including fossil fuel-based generation, maintain relevance in remote and industrial sites due to reliability during peak loads. However, regulatory pressure and carbon reduction goals are shifting investments toward renewable options.
- For instance, Greensmith's GEMS software has been integrated into numerous energy storage systems globally. The software, capable of processing over 100,000 data points per second, optimizes a wide array of energy assets, including renewables, storage, thermal generation, and grid loads, in real time.
By End-User
The industrial segment holds the dominant share of 45.2% in the decentralized power generation market in 2024. Industries adopt distributed systems to ensure uninterrupted power, reduce costs, and meet sustainability goals. Manufacturing, mining, and heavy industries rely on solar hybrid and cogeneration plants for energy resilience. The commercial segment follows, driven by office complexes and retail hubs using rooftop solar. Residential demand is growing due to smart inverters, home storage, and lower system prices. Transportation is emerging as a niche segment, supported by electric vehicle charging infrastructure.
Key Growth Drivers
Rising Demand for Energy Security
Decentralized power generation ensures stable and reliable energy supply during grid disruptions. Industries and communities are adopting distributed systems to reduce dependence on centralized infrastructure. The growing frequency of power outages and rising energy demand make decentralized generation attractive. Governments support these systems through subsidies and favorable regulations. Microgrids and hybrid power plants further enhance resilience and flexibility. This increased focus on energy security drives investment in decentralized solar, wind, and biomass projects, strengthening the market’s long-term growth potential.
- For instance, Schneider’s EcoStruxure Microgrid Flex is a standardized, modular microgrid system that uses configurable BESS modules with a power capacity from 60 kW to 2 MW, and is offered in standard 2-hour and 4-hour duration options.
Technological Advancements in Renewable Energy
Advances in solar PV, wind turbines, and energy storage improve the efficiency of decentralized systems. Modern inverters, smart grids, and battery technologies enable stable power supply and easy grid integration. Falling renewable equipment costs make decentralized generation more affordable for commercial and residential users. Digital monitoring and automation solutions enhance performance and lower maintenance costs. These innovations attract large-scale deployments in rural, remote, and industrial areas. As technology continues to evolve, it accelerates the global shift toward cleaner and distributed energy sources.
- For instance, Beacon Power's flywheel energy storage systems feature rotors that spin at speeds of up to 16,000 rpm within a sealed vacuum chamber to minimize air resistance.
Government Policies and Financial Incentives
Strong policy support plays a key role in expanding decentralized generation capacity. Governments offer feed-in tariffs, net metering, tax benefits, and renewable energy targets to attract investment. Subsidies reduce installation costs, making renewable projects financially viable for households and businesses. Regulatory reforms encourage private participation in energy infrastructure. International climate commitments further accelerate policy adoption. These initiatives create a favorable ecosystem for small-scale renewable generation, supporting market expansion across both developed and emerging economies.
Key Trends & Opportunities
Integration of Energy Storage Solutions
Energy storage systems are becoming integral to decentralized generation projects. Advanced lithium-ion and flow batteries enable better load balancing and grid stability. Coupling solar and wind installations with storage ensures uninterrupted power supply during demand peaks. This integration improves operational efficiency and makes decentralized systems more attractive for industrial and residential applications. The rise in affordable storage technologies creates new investment opportunities. Governments and private firms are increasingly prioritizing hybrid renewable-plus-storage projects to enhance system reliability.
- For instance, Convergent’s Potomac Edison deployment comprises a 1.75 MW / 8.4 MWh battery energy storage system, capable of delivering backup power for up to five hours.
Growth of Microgrids and Hybrid Systems
Microgrids and hybrid energy systems are gaining strong market traction. These systems combine multiple renewable sources, storage, and smart controls to ensure flexible, local energy generation. Industries, campuses, and remote communities deploy microgrids to reduce costs and achieve energy independence. Improved control technologies enable seamless switching between grid and off-grid modes. The scalability and modular design of microgrids offer strong opportunities for rural electrification. Their growing adoption supports the transition to decentralized and sustainable energy networks worldwide.
- For instance, Eos will supply a 3 MW / 15 MWh zinc-based battery system to the Paskenta Band tribal microgrid. The project, currently in the design stage, is set to integrate the Eos battery with 3.5 MW of solar, a 1 MW fuel cell, and 6 MW of diesel backup.
Decentralization Through Digital Platforms
Digital platforms and IoT technologies are transforming decentralized energy management. Smart meters, remote monitoring, and predictive analytics enhance energy flow control and system optimization. Cloud-based software enables real-time coordination between multiple generation units. These digital tools improve transparency and operational efficiency, lowering overall costs. This trend supports peer-to-peer energy trading models and virtual power plants. Expanding digital infrastructure creates new revenue streams for utilities, startups, and end-users in the distributed energy ecosystem.
Key Challenges
High Initial Capital Costs
Decentralized power generation projects often face high upfront investment requirements. Solar panels, wind turbines, batteries, and smart grid infrastructure demand significant capital. While operational costs are lower in the long run, initial expenditures can deter small businesses and residential users. Financing gaps and lack of accessible credit add to the problem. Although subsidies and incentives help, the high capital barrier remains a major challenge for mass adoption. Innovative financing models and public-private partnerships are crucial to address this issue.
Regulatory and Grid Integration Barriers
Inconsistent policies and complex grid interconnection rules slow market expansion. Many regions lack clear frameworks for distributed generation integration. Utilities often face difficulties in standardizing connection procedures for small-scale producers. Limited grid flexibility further complicates the process. These regulatory gaps delay project approvals and discourage investors. Harmonized standards, streamlined permitting, and supportive grid modernization policies are necessary to overcome these barriers and ensure smooth integration of decentralized systems into existing power infrastructure.
Regional Analysis
North America
North America holds a 29.4% share in the decentralized power generation market in 2024. The U.S. leads with strong investments in solar, wind, and microgrid projects. Policy incentives, tax credits, and net metering schemes encourage widespread adoption across commercial and residential sectors. Canada focuses on renewable integration to support rural and off-grid communities. Technological innovation and advanced grid infrastructure enhance system efficiency and reliability. Industrial users drive demand to improve energy resilience and reduce operational costs. Growing investment in hybrid renewable and storage projects strengthens the region’s leadership in distributed energy solutions.
Europe
Europe accounts for 27.6% of the global decentralized power generation market in 2024. Germany, the UK, and France lead in integrating distributed renewable energy systems. Strong environmental regulations and ambitious carbon neutrality targets accelerate market growth. The region emphasizes decentralized wind and solar installations supported by smart grids and energy storage. Feed-in tariffs and renewable auction programs attract private investments. Industrial and commercial sectors adopt microgrids to reduce dependence on centralized grids. Europe’s advanced regulatory framework and focus on sustainability position it as a key driver of the global decentralized energy transition.
Asia Pacific
Asia Pacific dominates the global decentralized power generation market with a 33.8% share in 2024. China, India, and Japan invest heavily in solar, wind, and hybrid renewable systems. Rapid urbanization, rising power demand, and grid stability needs drive strong adoption. Government subsidies and rural electrification programs boost off-grid solutions in developing countries. Industrial zones rely on decentralized systems to manage peak loads and lower energy costs. Technological advancements and declining equipment prices make deployment more affordable. Asia Pacific’s large population base and expanding renewable infrastructure solidify its market leadership position.
Latin America
Latin America holds a 5.8% share of the decentralized power generation market in 2024. Brazil, Mexico, and Chile lead regional growth with rising renewable investments. Decentralized solar and biomass projects play a key role in electrifying remote communities. Supportive government programs and public-private partnerships drive adoption. The commercial and residential sectors embrace rooftop solar systems to reduce energy costs and improve reliability. While infrastructure development is slower than in other regions, ongoing grid modernization efforts strengthen future growth potential. Latin America presents attractive opportunities for distributed energy expansion over the forecast period.
Middle East & Africa
The Middle East & Africa region accounts for 3.4% of the global decentralized power generation market in 2024. The UAE, Saudi Arabia, and South Africa drive regional activity with solar and hybrid microgrid projects. Energy diversification strategies reduce dependence on fossil fuels and strengthen grid reliability. High solar irradiation and government-led renewable programs make distributed generation cost-effective. Industrial and rural electrification initiatives support market expansion. Although infrastructure challenges remain in several African countries, increasing investment and policy reforms are improving deployment rates. The region is expected to record steady growth over the coming years.
Market Segmentations:
By Type:
- Hydroelectricity
- Fossil Fuel Electricity
By Source:
- Conventional/Non-Renewable Source
- Renewable Source
By End User:
- Residential
- Transportation
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The decentralized power generation market is shaped by key players such as S&C Electric Company, Seeo, Inc., SMA Solar Technology AG, Greensmith Energy Management Systems, ABB Ltd., Schneider Electric, Beacon Power, LLC, Convergent Energy and Power Inc., Eos Energy Storage, and BYD Company Ltd. The decentralized power generation market is becoming increasingly competitive, driven by rapid innovation and strong investment in renewable technologies. Companies are focusing on integrating solar, wind, and hybrid systems with advanced energy storage and smart grid infrastructure. Digital platforms, real-time monitoring tools, and predictive analytics enhance operational efficiency and system reliability. Strategic collaborations between energy developers, technology providers, and utilities are accelerating the deployment of distributed systems. Growing emphasis on flexible generation, grid resilience, and sustainable energy transitions further intensifies competition. This dynamic landscape encourages continuous technological advancement and wider adoption of decentralized power solutions worldwide.
Key Player Analysis
- S&C Electric Company
- Seeo, Inc.
- SMA Solar Technology AG
- Greensmith Energy Management Systems
- ABB Ltd.
- Schneider Electric
- Beacon Power, LLC
- Convergent Energy and Power Inc.
- Eos Energy Storage
- BYD Company Ltd.
Recent Developments
- In May 2025, CATL announced the rollout of the world’s first 9MWh ultra-large capacity TENER Stack Energy Storage System Solution, which aims to revolutionize the energy storage landscape.
- In December 2024, SSE and Siemens Energy have announced a partnership "Mission H2 Power," aimed at advancing gas turbine technology to operate on 100% hydrogen. This initiative supports the decarbonization of SSE’s Keadby 2 Power Station, which currently utilizes natural gas.
- In March 2024, Korea Western Power Co. (KOWEPO) and EDF Renewables entered a joint development agreement for a 1.5 GW solar farm in Khazna, United Arab Emirates (UAE). They are also in advanced talks with Abu Dhabi's Emirates Water and Electricity Co. (EWEC) for a similar project in the Al-Ajban area.
- In January 2024, GE Vernova and IHI Corporation have initiated the next phase of their collaboration to develop a gas turbine combustion system capable of burning 100% ammonia, potentially transforming natural gas fired electricity generation
Report Coverage
The research report offers an in-depth analysis based on Type, Source, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand rapidly with growing renewable energy integration.
- Energy storage adoption will enhance grid flexibility and reliability.
- Microgrid and hybrid system deployments will increase across industrial zones.
- Digital platforms will improve real-time monitoring and control efficiency.
- Rural electrification projects will drive growth in developing economies.
- Policy support and incentives will continue to attract private investment.
- Declining equipment costs will make decentralized systems more accessible.
- Smart grid upgrades will accelerate distributed generation integration.
- Corporate sustainability goals will boost renewable energy adoption.
- Global energy transitions will strengthen long-term market opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Decentralized Power Generation Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Decentralized Power Generation Market projected to grow between 2025 and 2032?
Which Decentralized Power Generation Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Decentralized Power Generation Market?
Who are the leading companies in the Decentralized Power Generation Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Decentralized Power Generation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Decentralized Power Generation Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 42.8 billion → 2032: USD 68.73 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Decentralized Power Generation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Decentralized Power Generation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Decentralized Power Generation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Decentralized Power Generation Market Drivers
- 3.3 Decentralized Power Generation Market Restraints & Challenges
- 3.4 Decentralized Power Generation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Decentralized Power Generation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Decentralized Power Generation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Decentralized Power Generation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Decentralized Power Generation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Decentralized Power Generation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Decentralized Power Generation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Decentralized Power Generation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Decentralized Power Generation Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Decentralized Power Generation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Decentralized Power Generation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Decentralized Power Generation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Decentralized Power Generation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Decentralized Power Generation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Decentralized Power Generation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Decentralized Power Generation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Decentralized Power Generation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Decentralized Power Generation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Decentralized Power Generation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Decentralized Power Generation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
