
Market Overview
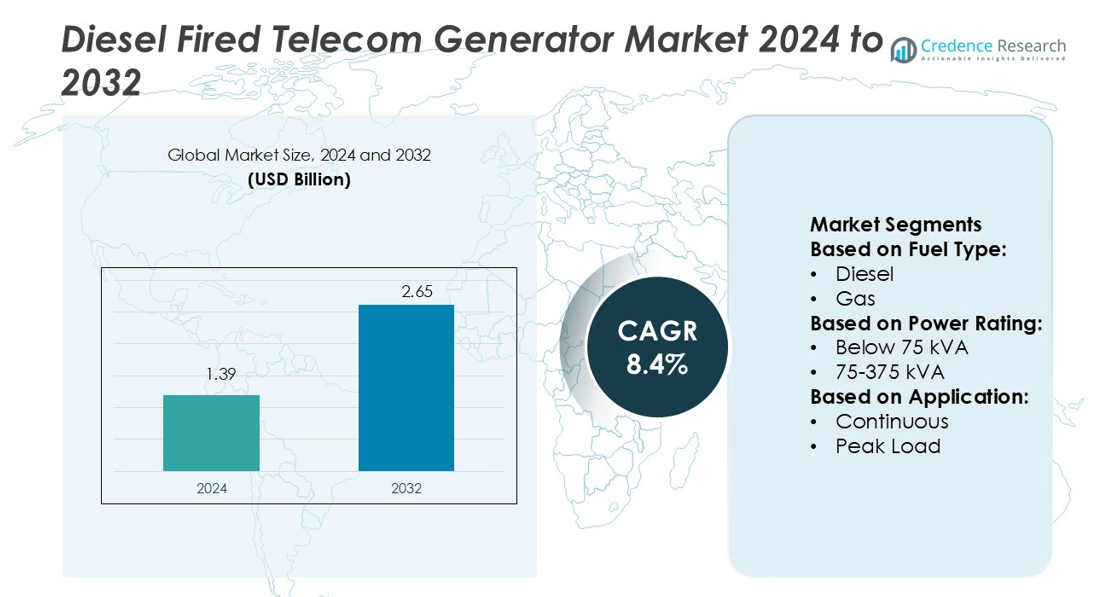
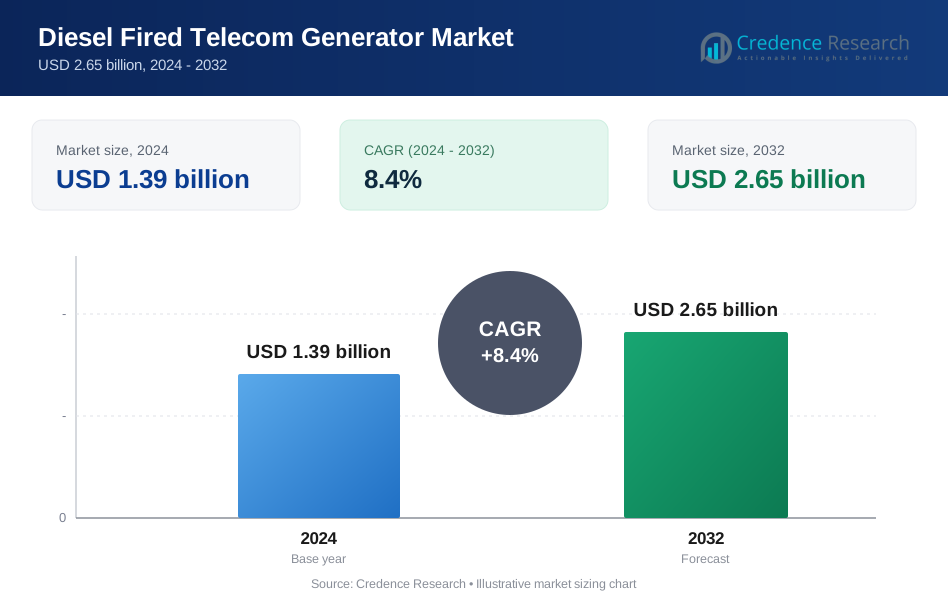
Diesel Fired Telecom Generator Market size was valued USD 1.39 billion in 2024 and is anticipated to reach USD 2.65 billion by 2032, at a CAGR of 8.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Diesel Fired Telecom Generator Market Size 2024 | USD 1.39 billion |
| Diesel Fired Telecom Generator Market, CAGR | 8.4% |
| Diesel Fired Telecom Generator Market Size 2032 | USD 2.65 billion |
The Diesel Fired Telecom Generator Market is shaped by major players such as FG Wilson, Kirloskar Electric, Atlas Copco, Generac Power Systems, Aggreko, Caterpillar, HIMOINSA, Cummins, AGG POWER TECHNOLOGY, and Deere & Company. These companies lead through strong product portfolios, advanced emission control technologies, and reliable service networks. Their focus on fuel-efficient, durable, and IoT-enabled generator systems strengthens their position in both developed and emerging markets. Asia Pacific holds the leading regional share at 34.7% in 2025, driven by large-scale telecom infrastructure expansion, weak grid reliability in rural areas, and growing 4G and 5G deployments.
Market Insights
- The Diesel Fired Telecom Generator Market was valued at USD 1.39 billion in 2024 and is expected to reach USD 2.65 billion by 2032, growing at a CAGR of 8.4%.
- Rising telecom network expansion and increasing demand for reliable backup power solutions are driving strong market growth.
- Integration of hybrid power systems and IoT-enabled monitoring solutions is emerging as a key market trend.
- Asia Pacific leads the market with a 34.7% share, supported by rural network expansion and 5G deployments, while North America holds 27.6% and Europe 24.1%.
- The diesel fuel type segment dominates with a 71.2% share, driven by high efficiency and durability, while the 75–375 kVA power rating segment leads with 48.5% share, reflecting strong demand for medium-capacity generators.
Market Segmentation Analysis:
By Fuel Type
The diesel segment holds the dominant share of the Diesel Fired Telecom Generator Market, accounting for 71.2% in 2025. Diesel generators offer high fuel efficiency, durability, and stable power supply, making them ideal for remote telecom towers. Their fast response time and ease of maintenance drive strong adoption across developing and developed markets. Gas and other fuel types are gaining traction, but their limited infrastructure restricts large-scale deployment. Regulatory support for cleaner diesel technologies further strengthens this segment’s position in the telecom power ecosystem.
- For instance, FG Wilson offers a broad diesel generator portfolio ranging from 6.8 kVA to 2,500 kVA, covering both standby and prime power applications for telecom operators. Many models feature Perkins-powered engines and advanced Deep Sea Electronics (DSE) control panels, enabling remote monitoring and rapid fault detection.
By Power Rating
The 75–375 kVA segment dominates the market with a 48.5% share in 2025. This power range effectively supports medium to large telecom tower loads, ensuring uninterrupted operation during grid outages. Telecom operators prefer this segment due to its balance of power capacity and operational efficiency. Modern diesel generators in this range integrate advanced load management and remote monitoring features, enhancing reliability. Increased deployment of 4G and 5G base stations in rural and semi-urban zones continues to drive demand for this rating segment.
- For instance, QAS 625 T4F model uses a Volvo Tier-4 Final 6-cylinder diesel engine, and supports paralleling of up to 32 units, enabling aggregated output up to 20 MVA for large telecom or utility sites.
By Application
The standby segment leads the market with a 52.7% share in 2025. Diesel standby generators are essential for ensuring uninterrupted network availability during power failures. Their quick start-up time, long service life, and lower operating cost make them a preferred choice for telecom operators. Peak load and continuous segments serve niche applications, but the majority of telecom infrastructure relies on standby power to maintain uptime. Growing investments in network modernization and rural connectivity projects further support strong demand in this segment.
Key Growth Drivers
Rising Telecom Network Expansion
The rapid expansion of telecom networks is a major growth driver for the Diesel Fired Telecom Generator Market. The increasing number of 4G and 5G base stations demands reliable backup power to ensure uninterrupted service. Rural and remote areas often lack stable grid connectivity, making diesel generators the primary power source. Their fast response time, low maintenance, and proven durability support critical telecom infrastructure. Investments in network modernization by operators and governments further accelerate diesel generator installations across emerging and developed markets.
- For instance, Generac Industrial Power offers stationary diesel units such as the SD100, delivering 100 kW (125 kVA) standby power from a 6.7-litre engine. SD750 series, the engine is sized at 18.1 L, producing up to 750 kW standby output, with factory tests covering internal vibration isolation and circuit separation features.
Growing Demand for Reliable Backup Power
Telecom operators are prioritizing network uptime, driving the demand for reliable backup solutions. Diesel generators offer consistent power during outages, ensuring minimal service disruption. Their compatibility with remote monitoring and load management systems enhances operational efficiency. Increasing data traffic, fueled by rising smartphone use, pushes operators to strengthen power reliability. In regions prone to grid instability or harsh weather, diesel generators remain the preferred choice. This growing reliance on dependable backup power is boosting the adoption of diesel generator systems.
- For instance, Aggreko launched a 400 kW Tier 4 Final diesel generator, trailer-mounted on a dual-axle system, leveraging EPA Tier 4 Final compliance and integrated remote monitoring into its “Greener Upgrades” line.
Advancements in Fuel-Efficient Technologies
Technological innovations in diesel engine design and power management are improving generator efficiency and lowering emissions. Modern diesel generators consume less fuel, produce fewer emissions, and operate at higher efficiency levels. Features such as auto-start, hybrid power integration, and smart monitoring make these systems more attractive to telecom operators. These advancements also help meet regulatory standards on emissions, supporting long-term use. Enhanced fuel efficiency reduces operational costs, strengthening the economic viability of diesel generator installations for telecom operators globally.
Key Trends & Opportunities
Integration of Hybrid Power Systems
The integration of diesel generators with renewable energy sources is emerging as a key trend. Hybrid systems combine diesel with solar or battery storage, optimizing fuel use and cutting emissions. Telecom operators are adopting these solutions to lower operational costs and comply with sustainability goals. Hybrid power systems also extend generator life by reducing runtime. This trend presents strong opportunities for manufacturers to offer advanced, integrated energy solutions tailored to telecom infrastructure in off-grid and weak-grid locations.
- For instance, Caterpillar offers the Cat® ETS (Energy Time Shift) module, designed for telecom DC loads, which provides 24 kW DC output and supports up to 150 kWh of storage in an IP55 outdoor enclosure.
Remote Monitoring and IoT Adoption
The use of IoT-enabled monitoring systems is transforming the management of telecom power infrastructure. Smart diesel generators equipped with sensors allow real-time performance tracking, predictive maintenance, and fault detection. This technology improves operational efficiency and reduces downtime. Telecom operators can remotely monitor multiple sites, lowering maintenance costs and improving response times. As networks scale in size and complexity, IoT-based power management is becoming an attractive opportunity for both equipment suppliers and service providers.
- For instance, HIMOINSA’s CE8 family of controllers (CEM8, CEA8, CEC8) enables real-time remote access, programming, and diagnostics across its generator lines. HIMOINSA’s NEURON cloud-based platform, supporting communication via USB, CAN, Modbus TCP/IP, Modbus RS-485, SNMP, and modem links.
Growing Deployment in Emerging Markets
Emerging economies in Asia Pacific, Africa, and Latin America are witnessing a surge in telecom infrastructure development. Rural electrification gaps create opportunities for diesel generator deployment to support tower operations. Expanding mobile user bases and government-backed connectivity initiatives drive demand further. The lack of stable power grids positions diesel generators as a cost-effective and reliable energy solution. These markets present significant growth opportunities for manufacturers and suppliers offering fuel-efficient, low-maintenance diesel generator systems.
Key Challenges
Rising Environmental Regulations
Stringent environmental regulations on diesel emissions pose a major challenge to the market. Governments are enforcing strict standards to reduce carbon and particulate emissions from diesel engines. This forces manufacturers to invest in advanced emission control technologies, increasing costs. Telecom operators may face compliance challenges, especially in markets with limited infrastructure for cleaner fuels. These regulations are pushing the industry toward alternative power solutions, potentially slowing traditional diesel generator demand in some regions.
High Fuel and Maintenance Costs
The high operational costs associated with diesel fuel and maintenance remain a barrier to wider adoption. Fluctuating fuel prices directly impact telecom operators’ operating budgets, especially for sites in remote locations. Regular servicing is required to ensure reliable performance, adding to total costs. These factors can make diesel generators less competitive compared to hybrid or renewable alternatives. Cost pressures are driving telecom operators to seek more fuel-efficient models or explore alternative power sources to optimize long-term expenditure.
Regional Analysis
North America
North America holds a 27.6% share of the Diesel Fired Telecom Generator Market in 2025. The region’s strong network infrastructure and increasing 5G rollout drive high demand for reliable backup power. The U.S. leads this market with extensive deployments in rural and suburban areas to ensure uninterrupted network availability. Frequent weather-related power outages further boost generator adoption. Advanced emission compliance and fuel-efficient technologies are widely implemented to meet environmental standards. The presence of established telecom operators and supportive energy policies strengthens the market position, ensuring steady long-term growth in this region.
Europe
Europe accounts for a 24.1% share of the Diesel Fired Telecom Generator Market in 2025. The region focuses on modernizing telecom networks with stringent emission regulations, encouraging the adoption of cleaner diesel technologies. Countries like Germany, France, and the UK lead deployments, supported by advanced infrastructure and growing 5G expansion. Backup power remains crucial for critical network operations in rural and industrial zones. Investment in hybrid systems that combine diesel with renewables is rising. The strong regulatory framework and ongoing network upgrades position Europe as a stable and mature market for diesel generator solutions.
Asia Pacific
Asia Pacific dominates the Diesel Fired Telecom Generator Market with a 34.7% share in 2025. The region’s rapid telecom expansion in countries like India, China, and Indonesia fuels strong demand for diesel generators, especially in rural and semi-urban areas with unstable grid supply. Growing mobile subscriber bases and 5G rollouts intensify backup power needs. Diesel generators offer cost-effective, reliable energy for tower operations. Governments and private operators are investing heavily in connectivity infrastructure. While sustainability initiatives are emerging, diesel remains the primary power source for many telecom installations in developing economies.
Latin America
Latin America captures a 4.7% share of the Diesel Fired Telecom Generator Market in 2025. Brazil and Mexico dominate regional demand, supported by ongoing 4G and 5G network deployments. Frequent grid instability and underdeveloped rural infrastructure increase reliance on diesel generators for backup power. Telecom operators favor these systems for their durability and low setup cost. Governments are encouraging connectivity expansion to underserved areas, further supporting adoption. While the market is smaller compared to other regions, its steady infrastructure investments and operational needs ensure consistent growth opportunities for diesel generator suppliers.
Middle East & Africa
The Middle East & Africa region holds an 8.9% share of the Diesel Fired Telecom Generator Market in 2025. Rural electrification gaps and challenging grid conditions make diesel generators vital for telecom tower operation. Countries like Saudi Arabia, UAE, Nigeria, and South Africa lead demand due to expanding telecom infrastructure. The region’s climate-related grid disruptions further emphasize the need for reliable backup systems. Rising investments in hybrid and off-grid power solutions are complementing diesel deployments. The combination of rapid network growth and limited grid reliability drives stable market opportunities in this region.
Market Segmentations:
By Fuel Type:
- Diesel
- Gas
By Power Rating:
- Below 75 kVA
- 75-375 kVA
By Application:
- Continuous
- Peak Load
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Diesel Fired Telecom Generator Market is shaped by key players including FG Wilson, Kirloskar Electric, Atlas Copco, Generac Power Systems, Aggreko, Caterpillar, HIMOINSA, Cummins, AGG POWER TECHNOLOGY, and Deere & Company. The Diesel Fired Telecom Generator Market is becoming increasingly competitive, driven by rapid technological innovation and shifting industry dynamics. Manufacturers are focusing on improving fuel efficiency, reducing emissions, and integrating smart monitoring systems to enhance reliability. Hybrid power solutions that combine diesel with renewable sources are gaining strong traction, especially in off-grid and rural telecom deployments. Companies are also expanding their service networks to offer faster maintenance and improved uptime for telecom operators. Regulatory compliance, operational cost optimization, and advanced automation remain key competitive factors. Continuous innovation and strategic collaborations with telecom infrastructure providers are shaping long-term market leadership.
Key Player Analysis
- FG Wilson
- Kirloskar Electric
- Atlas Copco
- Generac Power Systems
- Aggreko
- Caterpillar
- HIMOINSA
- Cummins
- AGG POWER TECHNOLOGY
- Deere & Company
Recent Developments
- In January 2025, AGG strengthened its strategic partnership with Cummins through high-level discussions aimed at expanding their generator product lineup. Representatives from the Chongqing Cummins Engine Company Ltd. and Cummins Investment Company Ltd. shared detailed cooperation efforts to promote innovation as well as new market opportunities for AGG-Cummins generator series.
- In September 2024, Scania unveiled its advanced 13-litre DI13 marine engine, designed for both propulsion and auxiliary use. The new engine sets a high standard for performance and reliability, offering improved fuel efficiency and significant CO2 emission reductions.
- In April 2024, Wärtsilä inaugurated its newly positioned Excellence Center in India to render remote help to its clients in the energy and marine sectors from the Middle East and Asia. This Excellence Center will function as a core operational hub that consolidates all known data sources to improve service capabilities.
- In March 2024, Sudhir Power Limited and Cummins jointly completed a mega roadshow in India, featuring CPCB IV+ compliant gensets. The event brought out the unique aspects and functionality of Cummnis powered gensets ensuring firsthand experience on their efficiency and sustainability
Report Coverage
The research report offers an in-depth analysis based on Fuel Type, Power Rating, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise with ongoing 4G and 5G network expansions worldwide.
- Hybrid systems integrating diesel with renewable energy will gain wider adoption.
- IoT-enabled monitoring will enhance operational efficiency and reliability.
- Manufacturers will focus on lowering emissions to meet stricter regulations.
- Fuel-efficient and low-maintenance models will dominate procurement strategies.
- Emerging markets will remain key growth hubs due to weak grid infrastructure.
- Upgrades in telecom tower power systems will boost replacement demand.
- Strategic collaborations will expand distribution and service networks globally.
- Digital control systems will improve power management and performance.
- Sustainability goals will accelerate innovation in cleaner diesel technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Diesel Fired Telecom Generator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Diesel Fired Telecom Generator Market projected to grow between 2025 and 2032?
Which Diesel Fired Telecom Generator Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Diesel Fired Telecom Generator Market?
Who are the leading companies in the Diesel Fired Telecom Generator Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Diesel Fired Telecom Generator Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Diesel Fired Telecom Generator Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.39 billion → 2032: USD 2.65 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Diesel Fired Telecom Generator Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Diesel Fired Telecom Generator Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Diesel Fired Telecom Generator Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Diesel Fired Telecom Generator Market Drivers
- 3.3 Diesel Fired Telecom Generator Market Restraints & Challenges
- 3.4 Diesel Fired Telecom Generator Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Diesel Fired Telecom Generator Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Diesel Fired Telecom Generator Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Diesel Fired Telecom Generator category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Diesel Fired Telecom Generator Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Diesel Fired Telecom Generator Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Diesel Fired Telecom Generator market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Diesel Fired Telecom Generator Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Diesel Fired Telecom Generator Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Diesel Fired Telecom Generator Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Diesel Fired Telecom Generator (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Diesel Fired Telecom Generator Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Diesel Fired Telecom Generator Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Diesel Fired Telecom Generator Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Diesel Fired Telecom Generator Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Diesel Fired Telecom Generator Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Diesel Fired Telecom Generator Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Diesel Fired Telecom Generator Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Diesel Fired Telecom Generator Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Diesel Fired Telecom Generator Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
