
Market Overview
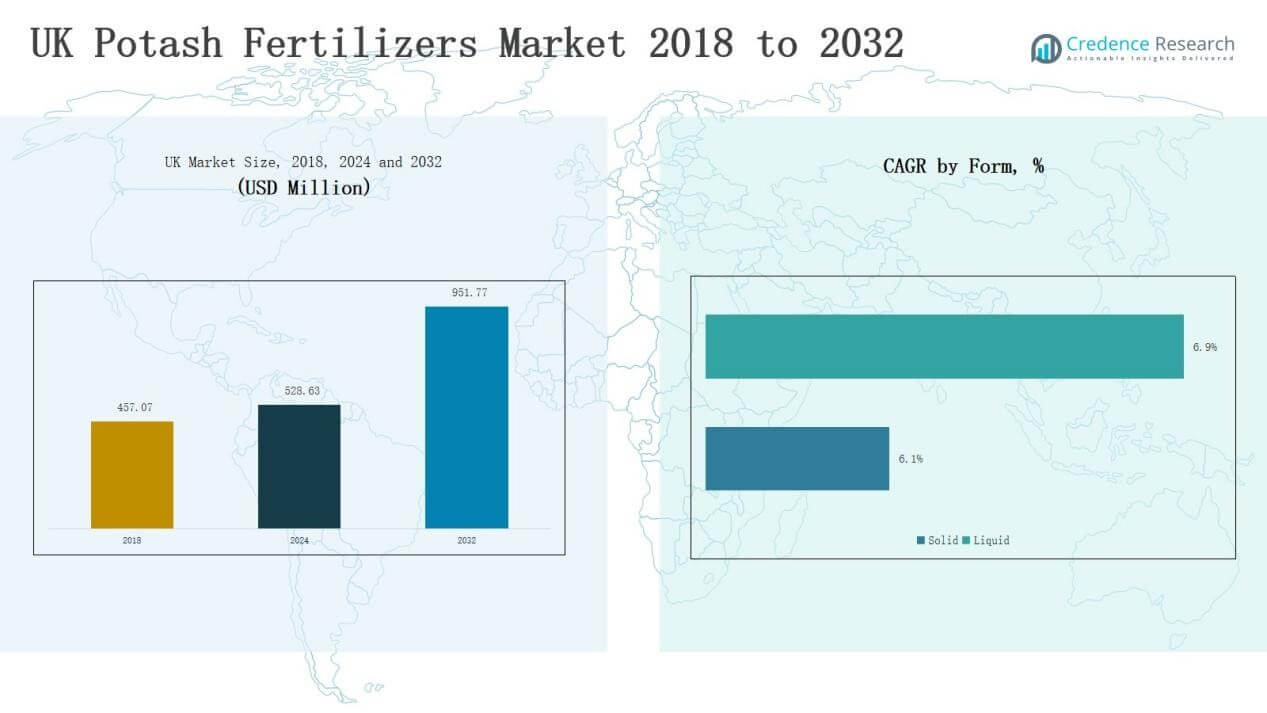
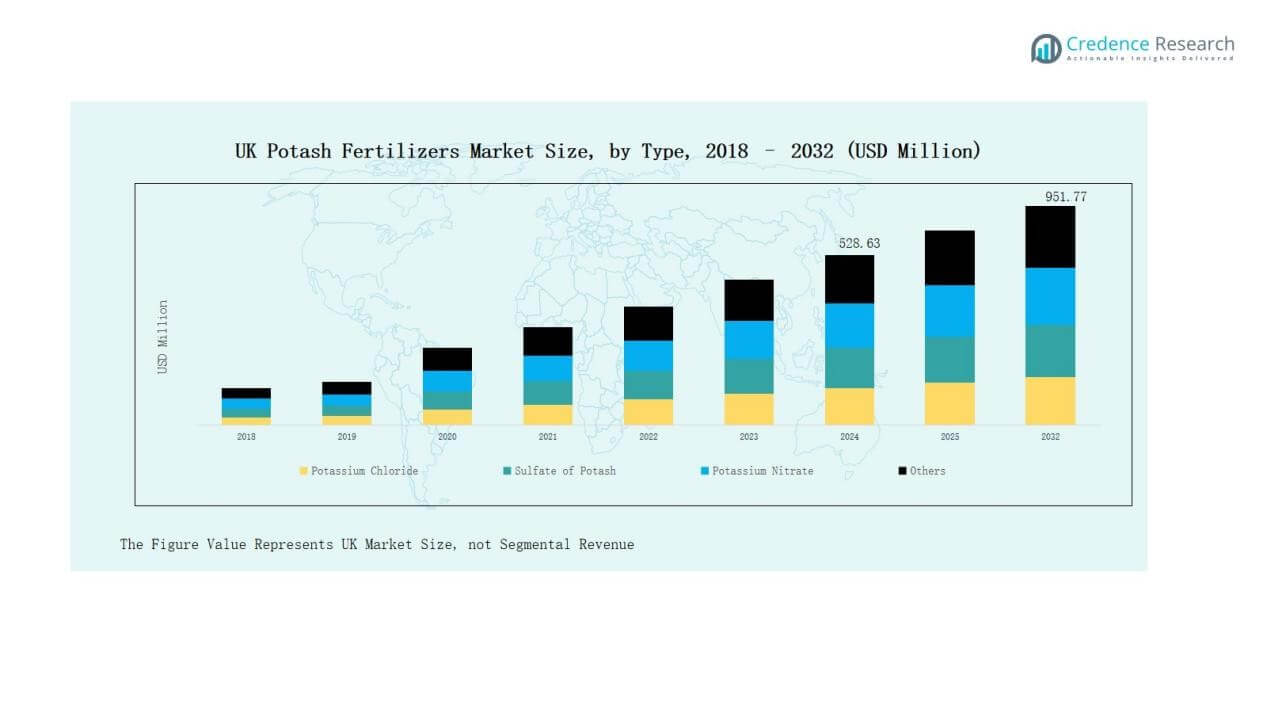
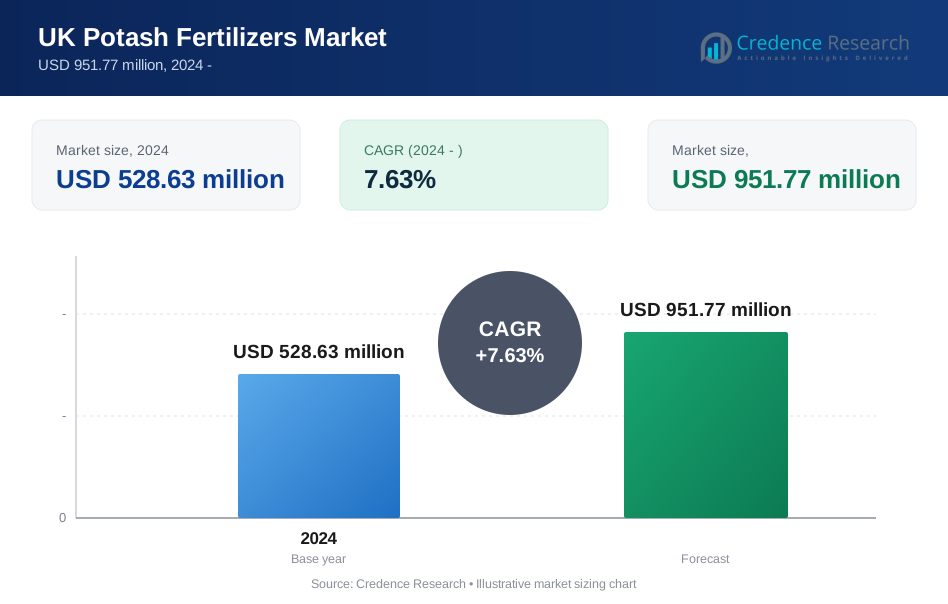
UK Potash Fertilizers Market size was valued at USD 457.07 million in 2018 to USD 528.63 million in 2024 and is anticipated to reach USD 951.77 million by 2032, at a CAGR of 7.63 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Potash Fertilizers Market Size 2024 | USD 528.63 Million |
| UK Potash Fertilizers Market, CAGR | 7.63% |
| UK Potash Fertilizers Market Size 2032 | USD 951.77 Million |
The UK Potash Fertilizers Market is shaped by the presence of global leaders and domestic suppliers focusing on product innovation, sustainable formulations, and efficient distribution. Key players include Yara International ASA, The Mosaic Company, Uralkali PJSC, Israel Chemicals Ltd. (ICL), Agrovista UK Limited, and Bionature UK, each strengthening their positions through diverse product portfolios and tailored solutions for cereals, grains, and horticultural crops. Competition is driven by rising demand for chloride-free and specialty formulations, particularly in high-value farming. England emerged as the leading region with a 45% share in 2024, supported by large-scale cereal cultivation, mechanized farming, and expanding greenhouse production. This dominance highlights England’s central role in driving the market’s overall growth trajectory.
Market Insights
- The UK Potash Fertilizers Market grew from USD 457.07 million in 2018 to USD 528.63 million in 2024 and is projected to reach USD 951.77 million by 2032, registering 7.63% growth.
- Potassium Chloride held a 52% share in 2024, driven by its cost efficiency and strong adoption in large-scale cereal and grain cultivation across the UK.
- Broadcasting led with 47% share in 2024, reflecting its simplicity and extensive use in cereal and oilseed farming, while fertigation gained traction in greenhouse production.
- Solid fertilizers commanded 66% share in 2024 due to longer shelf life and cost-effectiveness, while liquid formulations advanced with rising adoption in fertigation and foliar spraying.
- England dominated with 45% share in 2024, supported by extensive cereal farming, advanced mechanization, and greenhouse horticulture, making it the leading regional contributor to market growth.
Market Segment Insights
By Type
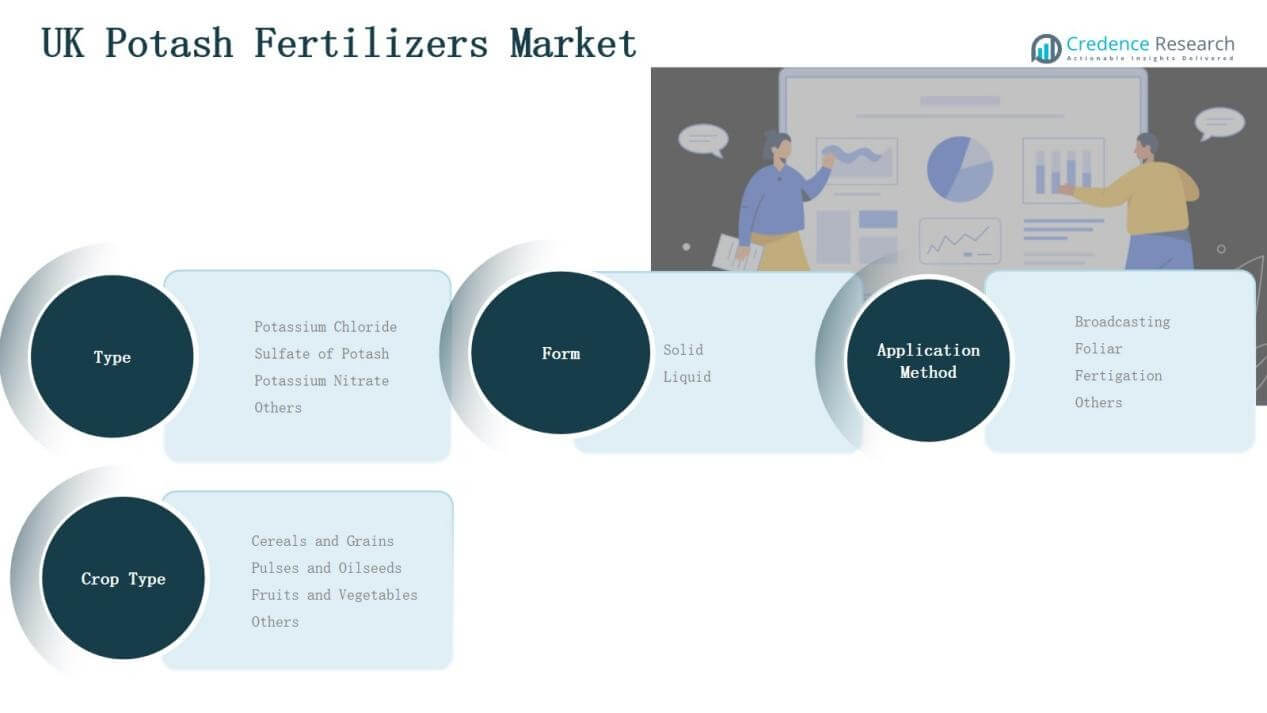
Potassium Chloride dominated the UK potash fertilizers market with a 52% share in 2024, driven by its affordability and suitability for large-scale cereal and grain cultivation. Sulphate of Potash held strong traction in fruit and vegetable farming, where chloride-free formulations improve crop quality and resistance. Potassium Nitrate gained steady adoption in high-value horticulture for supplying both potassium and nitrogen, while mixed or specialty blends in the Others category remained limited to niche applications.
For instance, Yara UK introduced its Krista-K Plus potassium nitrate solution for protected greenhouse horticulture, targeting growers of tomatoes and peppers with integrated potassium and nitrogen delivery.
By Application Method
Broadcasting led the application method segment with a 47% share in 2024, supported by its simplicity and widespread use in cereal and oilseed farms. Foliar spraying gained momentum in vineyards and horticulture, where targeted nutrient delivery improves yields and reduces waste. Fertigation expanded in greenhouse and irrigated farming systems, particularly for fruits and vegetables. The Others category contributed marginally, focused on localized application in specialized crop systems.
By Form
Solid fertilizers accounted for a 66% share in 2024, reflecting their longer shelf life, ease of transport, and cost effectiveness for field crops. Liquid fertilizers captured growth through adoption in fertigation and foliar methods, where quick nutrient uptake and uniform application support greenhouse and high-value crop production. Rising mechanization and precision farming practices are expected to further strengthen the role of liquid formulations in modern UK agriculture.
For instance, ICL Group introduced its Solinure FX liquid formulations targeted at high-value horticultural crops, emphasizing compatibility with fertigation systems.
 Key Growth Drivers
Rising Demand for High-Yield Crops
The UK potash fertilizers market is driven by the need to increase agricultural productivity amid limited arable land. Farmers rely on potassium-based fertilizers to enhance root strength, crop resistance, and yield, particularly in cereals, grains, and horticultural crops. Growing food security concerns, coupled with consumer demand for consistent quality, fuel adoption across both large farms and greenhouse systems. This demand is supported by government-backed initiatives promoting efficient nutrient use and sustainable farming practices across the agricultural sector.
For instance, ICL Group expanded its Polysulphate® fertilizer distribution in the UK, highlighting its multi-nutrient benefits (including potassium and sulfur) for cereal and oilseed farmers.
Expansion of Greenhouse and Horticultural Farming
Greenhouse cultivation and horticultural farming are expanding rapidly across the UK, supported by rising demand for fruits, vegetables, and ornamental crops. Chloride-free formulations such as sulphate of potash and potassium nitrate are increasingly preferred to enhance crop quality and shelf life. The controlled environment of greenhouses requires precision nutrient management, which potash fertilizers effectively provide. This expansion strengthens market demand, particularly among high-value crop producers aiming to balance quality, productivity, and profitability.
Growing Focus on Sustainable Agriculture
Sustainability is a key growth driver as UK farmers adopt eco-friendly practices to align with regulatory frameworks and consumer preferences. Potash fertilizers that support efficient water use, soil fertility, and reduced nutrient loss gain importance in modern farming systems. Suppliers are introducing innovative formulations, including low-chloride and water-soluble options, to cater to this shift. The increasing integration of precision agriculture tools further boosts potash fertilizer use, ensuring targeted application and minimizing environmental impact while maintaining productivity.
For instance, Yara International reported expanding trials of its potassium-based fertigation solutions with UK growers, showcasing up to 20% reduction in nutrient runoff compared to conventional field application methods.
 Key Trends & Opportunities
Adoption of Precision Farming Technologies
The adoption of precision agriculture technologies creates strong opportunities for potash fertilizer providers in the UK. Farmers are using digital tools, sensors, and GPS-based systems to optimize fertilizer application, reduce waste, and enhance yields. This trend aligns with broader industry goals of efficiency and sustainability. Fertilizer manufacturers are expected to partner with technology providers to deliver customized solutions, integrating real-time soil and crop data to maximize nutrient efficiency and farm profitability.
For instance, CF Fertilisers UK introduced precision application trials using N-Sensor technology, helping cereal farmers adjust real-time potash and nitrogen application rates to boost yield and reduce input costs.
Increasing Shift Toward Specialty Fertilizers
The UK market is witnessing a clear shift toward specialty and chloride-free fertilizers such as sulphate of potash and potassium nitrate. These products are increasingly adopted in horticulture, greenhouse farming, and vineyards where crop quality and nutrient balance are crucial. Rising consumer demand for premium fruits and vegetables creates further opportunities for suppliers. Specialty fertilizers also support export competitiveness by meeting strict international quality standards, encouraging continued product innovation and market penetration.
For instance, Mosaic Company reported expanding availability of its Performance Potash solutions for European greenhouse producers, including the UK, ensuring sustainable nutrient supply with reduced chloride levels.
Key Challenges
Volatile Raw Material Prices
The UK potash fertilizers market faces challenges from fluctuating global potash prices, heavily influenced by supply dynamics in key producing countries. Price volatility creates uncertainty for farmers, affecting affordability and purchasing decisions. It also impacts supplier margins, particularly for companies reliant on imports. Sustained fluctuations may limit adoption among smaller farms, slowing overall market growth.
Environmental and Regulatory Pressures
Tightening environmental regulations in the UK challenge the use of conventional fertilizers, with increasing scrutiny on nutrient runoff and soil degradation. Farmers are required to adopt sustainable nutrient management practices, which raises compliance costs. Suppliers must innovate with eco-friendly formulations, but this transition demands significant R&D investment. Balancing productivity with environmental responsibility remains a persistent challenge for the industry.
Competition from Alternative Practices
Alternative soil management practices, including organic fertilizers and crop rotation techniques, present competition to potash fertilizers in the UK. With growing consumer preference for organic food and government support for sustainable agriculture, some farmers are shifting away from chemical fertilizers. This trend creates market pressure, particularly in the fruits and vegetables segment where organic adoption is higher. Potash fertilizer providers must adapt strategies to counter this shift and highlight the role of balanced nutrition.
Regional Analysis
England
England led the UK Potash Fertilizers Market with a 45% share in 2024, supported by extensive cereal and grain farming. Large agricultural regions such as East Anglia drive fertilizer demand through mechanized and high-intensity cultivation. Greenhouse and horticultural production further strengthens the use of chloride-free formulations like sulphate of potash and potassium nitrate. Farmers adopt broadcasting methods widely for cereals, while fertigation is expanding in horticulture. England remains the dominant contributor, combining scale, advanced farming, and modern infrastructure.
Scotland
Scotland held a 25% share in 2024, supported by its strong focus on barley, wheat, and oilseed production. The country’s cool climate favors cereal farming, where potash fertilizers improve soil fertility and crop resilience. Broadcasting is the most common application method due to expansive farmland. Rising demand for sustainable agriculture practices and niche horticultural crops is gradually increasing specialty fertilizer adoption. It continues to emerge as a critical regional market with consistent fertilizer demand.
Wales
Wales accounted for a 15% share in 2024, reflecting steady demand across mixed farming systems. Potash fertilizers play a vital role in supporting cereals, pasture management, and fruit crops. The region’s focus on sustainable practices encourages the use of chloride-free formulations for higher quality produce. Foliar application is gaining popularity among horticultural farmers aiming to improve crop quality. Wales shows stable fertilizer adoption, with growth opportunities in high-value horticulture and greenhouse farming.
Northern Ireland
Northern Ireland represented a 15% share in 2024, with a balanced reliance on cereals, potatoes, and horticultural crops. Potash fertilizers support both yield improvement and soil health in the region’s diverse cropping systems. Fertigation is gaining momentum in protected farming, particularly for fruits and vegetables. Strong export-oriented farming practices encourage adoption of specialty formulations. Northern Ireland plays a consistent role in the market, supported by efficient farming methods and growing attention to crop quality.
 Market Segmentations:
By Type
- Potassium Chloride
- Sulphate of Potash
- Potassium Nitrate
- Others
By Application Method
- Broadcasting
- Foliar
- Fertigation
- Others
By Form
- Solid
- Liquid
By Crop Type
- Cereals and Grains
- Pulses and Oilseeds
- Fruits and Vegetables
- Others
By Region
- England
- Scotland
- Wales
- Northern Ireland
Competitive Landscape
The UK Potash Fertilizers Market is characterized by the presence of both global leaders and domestic suppliers competing on product quality, distribution reach, and innovation. Key companies such as Yara International ASA, The Mosaic Company, Uralkali PJSC, and Israel Chemicals Ltd. (ICL) maintain strong positions through extensive product portfolios and integrated supply chains. Local players including Agrovista UK Limited and Bionature UK contribute by catering to region-specific farming needs and offering tailored solutions for horticulture and greenhouse crops. Competition is shaped by rising demand for chloride-free and specialty formulations, pushing companies to expand their offerings in sulphate of potash and potassium nitrate segments. Partnerships with distributors, investment in R&D, and digital advisory services enhance competitiveness. With sustainability regulations tightening, companies focus on eco-friendly formulations and precision farming support to secure long-term market presence. It remains a moderately concentrated market with both global and regional firms actively influencing growth.
Key Players
- Yara International ASA
- The Mosaic Company
- Agrovista UK Limited
- Bionature UK
- Uralkali PJSC
- Israel Chemicals Ltd. (ICL)
Recent Developments
- In August 2024, ICL signed a five-year agreement valued at approximately USD 170 million with AMP Holdings Group Co. Ltd., a major agricultural distributor in China, to expand its Growing Solutions product offerings globally.
- In September 2025, ERM was hired by EBRD and IFA to develop a low-carbon roadmap for the global potash and phosphate fertiliser industry.
- In September 2025, the UK and Brazil signed a memorandum of understanding (MoU) to partner on sustainable fertiliser production and environmental impact reduction.
- In November 2024, Anglo American and the IAEA launched a research project under the Atoms4Food partnership. It aims to study use of polyhalite and other additives to fight soil salinization.
Report Coverage
The research report offers an in-depth analysis based on Type, Application Method, Form, Crop Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for potash fertilizers will rise with expanding cereal and grain cultivation.
- Greenhouse and horticultural farming will drive adoption of chloride-free formulations.
- Precision agriculture practices will increase targeted fertilizer application across farms.
- Liquid formulations will gain share due to fertigation and foliar applications.
- Sustainability regulations will push innovation in eco-friendly fertilizer solutions.
- Specialty fertilizers will expand in fruits, vegetables, and vineyard production.
- Import dependence will shape pricing strategies and supply chain resilience.
- Local distributors will strengthen their role through customized crop advisory services.
- Digital platforms will support farmers with real-time nutrient management solutions.
- Global and domestic players will intensify competition through R&D and partnerships.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for UK Potash Fertilizers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the UK Potash Fertilizers Market projected to grow between 2025 and 2032?
Which UK Potash Fertilizers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the UK Potash Fertilizers Market?
Who are the leading companies in the UK Potash Fertilizers Market?
Which region commanded the largest share of the UK Potash Fertilizers Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Potash Fertilizers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Potash Fertilizers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 528.63 million → forecast year: USD 951.77 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Potash Fertilizers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Potash Fertilizers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Potash Fertilizers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Potash Fertilizers Market Drivers
- 3.3 UK Potash Fertilizers Market Restraints & Challenges
- 3.4 UK Potash Fertilizers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Potash Fertilizers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Potash Fertilizers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Potash Fertilizers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Potash Fertilizers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Potash Fertilizers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Potash Fertilizers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Potash Fertilizers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Potash Fertilizers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Potash Fertilizers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Potash Fertilizers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Potash Fertilizers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Potash Fertilizers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Potash Fertilizers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Potash Fertilizers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Potash Fertilizers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Potash Fertilizers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Potash Fertilizers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Potash Fertilizers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Potash Fertilizers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
