
Market Overview
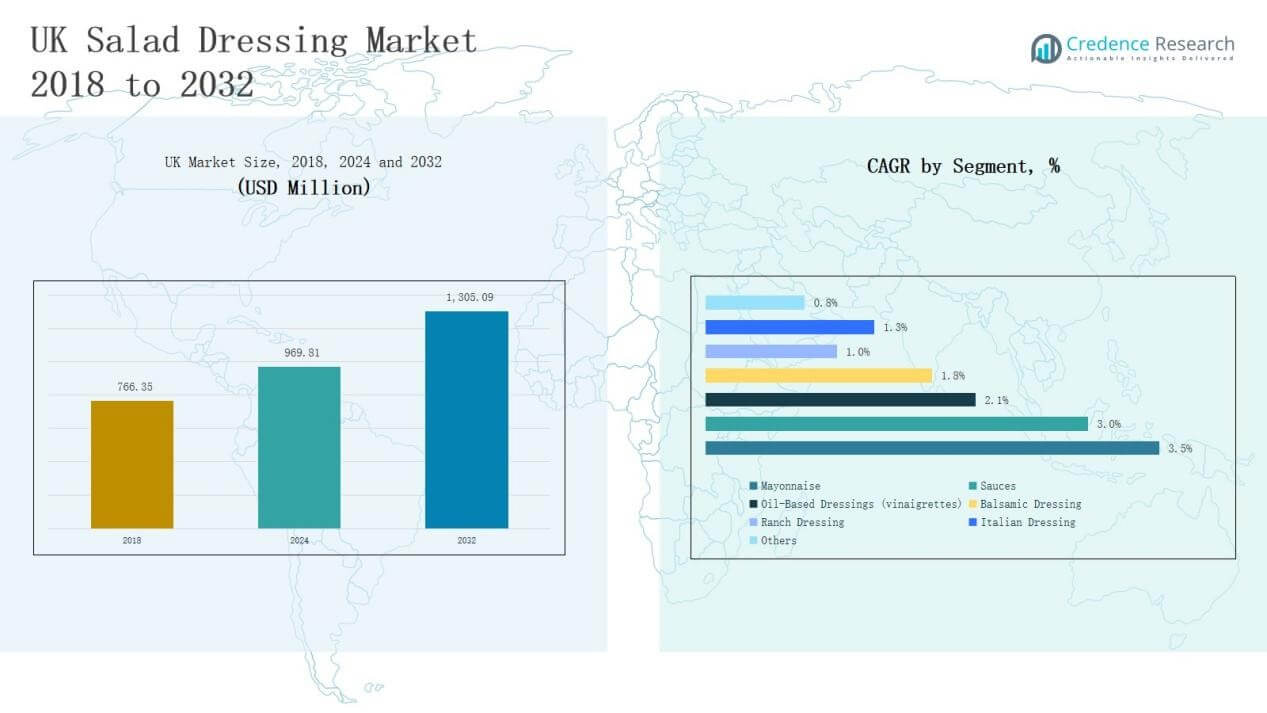
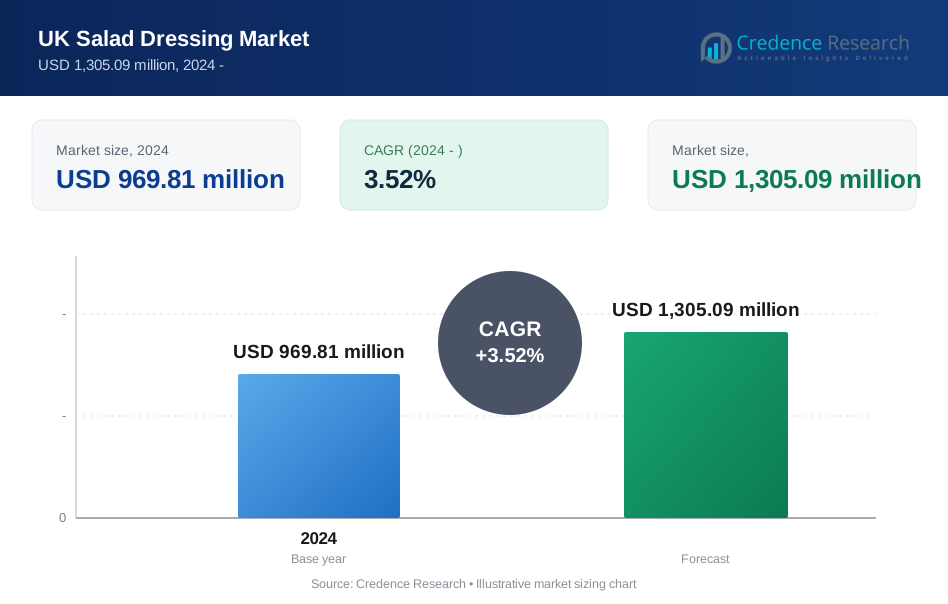
UK Salad Dressing Market size was valued at USD 766.35 million in 2018 to USD 969.81 million in 2024 and is anticipated to reach USD 1,305.09 million by 2032, at a CAGR of 3.52 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UK Salad Dressing Market Size 2024 | USD 969.81 Million |
| UK Salad Dressing Market, CAGR | 3.52% |
| UK Salad Dressing Market Size 2032 | USD 1,305.09 Million |
The UK Salad Dressing Market is shaped by a mix of multinational leaders and regional brands competing across conventional and organic categories. Prominent players include Unilever PLC, Kraft Heinz Company, Ken’s Foods Inc., PepsiCo’s Tostito’s, Best Foods Mayonnaise, Heinz, Mrs. Bector’s Cremica, Oasis Foods Company, Newman’s Own, and Stokes Sauces, all leveraging strong distribution networks, product innovation, and brand recognition. Private labels from major supermarket chains further intensify competition by appealing to price-sensitive buyers. Regionally, England leads with a 61% market share, supported by its large population base, robust retail infrastructure, and growing consumer adoption of organic and clean-label products. This dominance positions England as the primary growth engine within the UK market.
 Market Insights
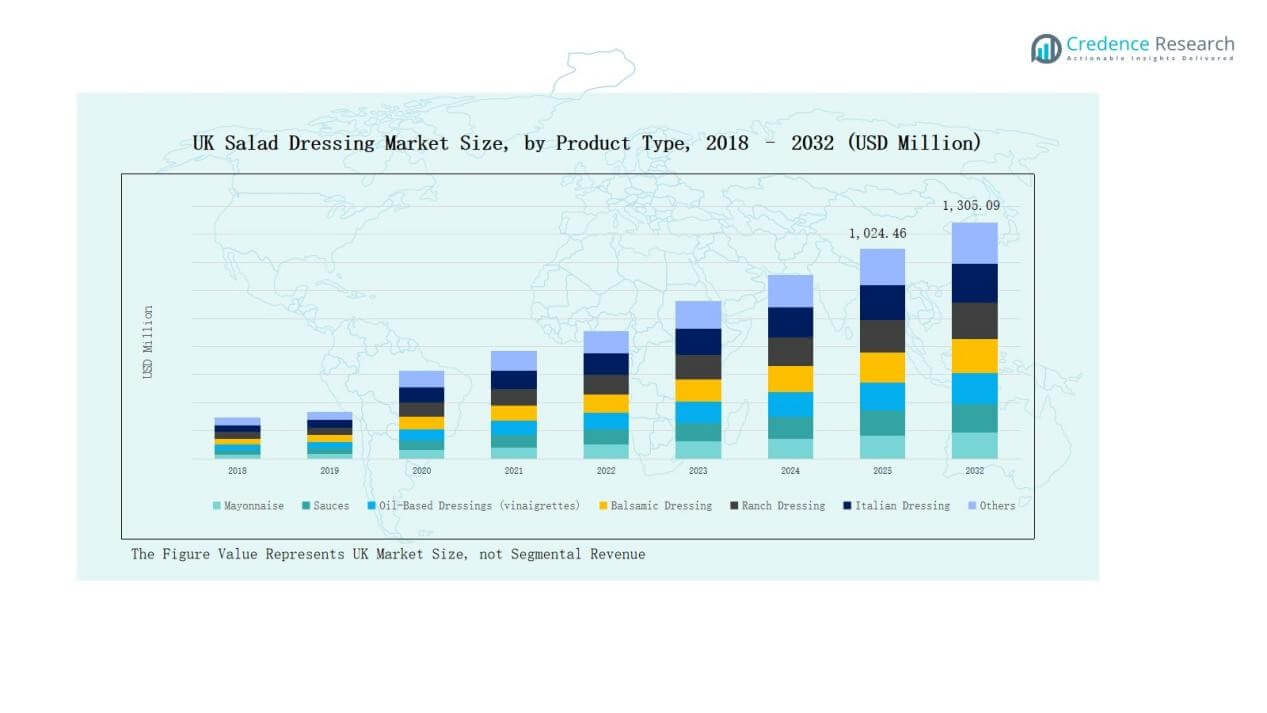
- The UK Salad Dressing Market grew from USD 766.35 million in 2018 to USD 969.81 million in 2024 and is projected to reach USD 1,305.09 million by 2032.
- Mayonnaise dominates with a 34% share, followed by sauces at 23% and vinaigrettes at 15%, reflecting both traditional preferences and growing health-conscious consumer choices.
- Conventional dressings lead with 69% share, while organic products at 31% expand steadily, supported by clean-label demand and increasing presence in supermarket organic aisles.
- Retail stores command 56% of sales, foodservice contributes 30%, and off-trade channels at 14% benefit from online grocery platforms and specialty outlets.
- England leads regionally with a 61% share, followed by Scotland at 15%, Wales at 12%, and Northern Ireland at 12%, highlighting diverse consumption preferences across the UK.
Market Segment Insights
By Product Type
Mayonnaise leads the UK Salad Dressing Market with a 34% share, supported by its versatility in sandwiches, burgers, and ready-to-eat meals. Sauces follow with a 23% share, driven by demand for variety and convenience in home dining. Oil-based dressings, including vinaigrettes, account for 15%, benefiting from rising health awareness and preference for lighter options. Balsamic dressing holds a 9% share, appealing to premium and gourmet consumers. Ranch and Italian dressings together contribute 11%, favored by younger buyers influenced by global cuisines. Other niche varieties make up the remaining 8%, targeting experimental consumers.
For instance, Hellmann’s, a Unilever brand, launched its first vegan mayonnaise in the UK, expanding options for flexitarian and plant-based consumers.
By Category
Conventional salad dressings dominate with a 69% share, driven by affordability, widespread retail availability, and strong consumer loyalty to established brands. This category is reinforced by private label expansion across supermarkets. Organic dressings hold a 31% share and are growing steadily, supported by health-conscious consumers seeking natural, clean-label products. Expansion of organic food aisles and increased focus on transparent labeling strengthen this segment’s appeal.
By Distribution Channel
Retail stores command the largest share at 56%, supported by the dominance of supermarkets, hypermarkets, and private labels offering wide product ranges. Foodservice accounts for 30%, reflecting rising demand in restaurants, cafés, and quick-service outlets where salads and dressings are core offerings. Other off-trade channels hold a 14% share, with online grocery platforms and specialty stores gaining traction. Growth in digital retail and convenience-based shopping continues to push this segment upward.
For instance, in August 2025, Amazon expanded its same-day grocery delivery service to include fresh groceries like produce, meat, and dairy in over 1,000 U.S. cities, with plans to reach over 2,300 by the end of the year. This move contributed to growth in online grocery penetration and overall Prime adoption
Key Growth Drivers
Rising Preference for Convenience Foods
Busy lifestyles and growing demand for ready-to-eat meals drive the use of salad dressings in the UK. Mayonnaise and sauces remain the most popular, offering versatility across sandwiches, burgers, and quick meals. The expansion of convenience stores and supermarket chains boosts accessibility, while promotional offers further encourage consumer purchases. Increasing urbanization and dual-income households strengthen this shift toward quick-preparation food items. This driver supports consistent demand for dressings across retail and foodservice channels, keeping them a staple in everyday consumption.
Health and Wellness Influence
Health-conscious consumers are increasingly favoring lighter, low-fat, and organic salad dressings in the UK. Oil-based vinaigrettes and balsamic options benefit from their perceived nutritional value, while demand for reduced-calorie and clean-label products grows. Rising concerns about obesity and cardiovascular risks push consumers away from high-fat alternatives. Manufacturers are actively reformulating products with natural ingredients, reduced salt, and sugar. This alignment with wellness-focused preferences boosts market growth and strengthens consumer trust in healthier dressing options.
For instance, Unilever expanded its Hellmann’s portfolio in the UK with a new range of plant-based and lower-fat dressings made with natural ingredients to cater to health-conscious consumers.
Expansion of Foodservice Sector
The foodservice industry contributes significantly to salad dressing consumption, supported by restaurants, cafés, and quick-service outlets across the UK. Salads are increasingly featured as main or side meals, encouraging use of diverse dressings. Tourism and multicultural dining trends also enhance the popularity of international flavors like ranch and Italian dressings. Partnerships between foodservice providers and leading brands improve visibility and loyalty. Catering services for events further boost volumes. This sector remains a key growth driver by expanding product exposure beyond retail shelves.
For instance, Nando’s UK added new menu items with peri-peri salad bowls, incorporating house-made dressings to meet rising demand for lighter, flavor-forward dining options.
Key Trends & Opportunities
Growth of Organic and Clean-Label Products
Organic salad dressings are growing in popularity as UK consumers prioritize natural ingredients and transparent sourcing. Supermarkets and specialty stores are expanding organic sections, offering more options to health-conscious buyers. Brands promoting eco-friendly packaging and certified organic claims gain competitive advantages. This trend creates opportunities for premium pricing and stronger consumer trust. Clean-label innovations, emphasizing reduced additives and sustainability, will further drive product differentiation and long-term adoption in the UK market.
For instance, Kerry Group in mid-2025 launched ingredient solutions formulated to reduce environmental impact while supporting clean-label claims, catering to eco-conscious brands.
Expansion of E-commerce and Digital Retail
Online grocery platforms and direct-to-consumer strategies are reshaping salad dressing distribution in the UK. Consumers increasingly prefer the convenience of online shopping for both conventional and premium products. E-commerce allows smaller brands to reach niche audiences and launch innovative dressings more effectively. Subscription models and promotional bundles improve consumer loyalty. Digital marketing campaigns targeting younger, health-conscious buyers create fresh growth opportunities. This channel’s continued expansion is expected to strengthen accessibility and product diversification.
For instance, Tesco expanded its Whoosh rapid delivery service across 1,000 UK stores, enabling faster access to grocery items, including salad dressings and other condiments.
 Key Challenges
Intense Competitive Pressure
The UK Salad Dressing Market is highly competitive, with multinational corporations, regional producers, and private labels vying for share. Price competition is fierce, particularly in retail where private labels dominate shelf space. Established players must continually innovate to retain loyalty and defend margins. Smaller firms face challenges in distribution and brand visibility, limiting their reach. This crowded environment forces companies to invest heavily in marketing, product innovation, and promotional activities to differentiate themselves in a mature market.
Regulatory and Labeling Requirements
Strict UK and EU regulations on food safety, nutrition, and labeling present compliance challenges for manufacturers. Companies must adhere to standards regarding allergens, sugar and salt content, and clean-label claims. Compliance raises operational costs and requires ongoing monitoring to avoid penalties. Smaller producers often face financial strain in meeting these requirements. While regulations help strengthen consumer trust, they also add complexity to market entry and expansion strategies, particularly for emerging and niche brands in the UK.
Evolving Consumer Preferences Shifting consumer tastes create uncertainty for manufacturers, requiring constant adaptation. Younger consumers seek international flavors like ranch and Italian dressings, while traditional buyers remain loyal to mayonnaise and vinaigrettes. This balance between innovation and heritage products complicates portfolio strategies. Brands failing to keep pace with evolving preferences risk losing relevance. Frequent product updates increase costs and shorten product lifecycles. Successfully managing this challenge is critical for maintaining competitiveness in the dynamic UK Salad Dressing Market.
Regional Analysis
England
England dominates the UK Salad Dressing Market with a 61% share, supported by its large population and strong urban demand. It benefits from widespread supermarket penetration and private label expansion, which enhance accessibility for both premium and budget-conscious consumers. Mayonnaise remains the most popular product, with sauces and vinaigrettes gaining momentum among health-conscious buyers. The foodservice sector also plays a key role, as restaurants, cafés, and quick-service outlets drive consumption. It shows strong adoption of organic and clean-label products, reflecting broader health and sustainability trends. England continues to set the pace for innovation and distribution within the market.
Scotland
Scotland holds a 15% share, influenced by changing consumer preferences and rising health awareness. Oil-based dressings and balsamic varieties are growing in popularity as lighter alternatives to mayonnaise. Retail stores dominate distribution, though foodservice outlets are increasingly adding diverse dressings to menus. Local consumers demonstrate strong interest in clean-label and natural options, creating opportunities for organic brands. It benefits from government initiatives promoting healthy eating, which further supports category diversification. Scotland’s market reflects a steady balance between traditional favorites and emerging premium offerings.
Wales
Wales accounts for a 12% share, with retail stores driving the majority of sales. Mayonnaise continues to dominate, but demand for sauces and vinaigrettes is rising among younger consumers. Foodservice demand is supported by casual dining and quick-service outlets that integrate international flavors such as ranch and Italian dressings. Organic products are gradually gaining traction as awareness of clean-label options increases. It demonstrates a preference for affordable and convenient products, making conventional dressings dominant. Wales remains a steadily growing contributor within the UK Salad Dressing Market.
Northern Ireland
Northern Ireland captures a 12% share, supported by cross-border trade influences and evolving consumer preferences. Retail dominates distribution, but online grocery platforms are expanding access to niche and imported dressings. Mayonnaise leads the product mix, with vinaigrettes and balsamic dressings gradually increasing their share. Foodservice demand is supported by restaurants and hotels catering to both local and tourist populations. It reflects a growing interest in health-oriented dressings, with organic options gaining visibility. Northern Ireland’s market is positioned for steady growth as consumer tastes diversify.
 Market Segmentations:
By Product Type
- Mayonnaise
- Sauces
- Oil-Based Dressings (Vinaigrettes)
- Balsamic Dressing
- Ranch Dressing
- Italian Dressing
- Others
By Category
- Conventional
- Organic
By Distribution Channel
- Foodservice
- Retail Stores
- Other Off-Trade Channels
By Region
- England
- Scotland
- Wales
- Noethern Ireland
Competitive Landscape
The UK Salad Dressing Market is highly competitive, shaped by global corporations, regional producers, and private labels. Leading players such as Unilever PLC, Kraft Heinz Company, Ken’s Foods Inc., PepsiCo’s Tostito’s, Best Foods Mayonnaise, Heinz, Mrs. Bector’s Cremica, Oasis Foods Company, Newman’s Own, and Stokes Sauces dominate through brand recognition, strong distribution networks, and diversified product portfolios. Multinationals leverage economies of scale to expand conventional and organic ranges, while niche brands emphasize clean-label, gourmet, and health-focused options. Private labels from UK supermarkets intensify competition, targeting price-sensitive buyers with affordable alternatives. Innovation in flavors, reduced-fat variants, and eco-friendly packaging strengthens brand differentiation. Companies also partner with foodservice operators to increase visibility and consumer reach. With shifting consumer preferences, competition is centered on innovation, health positioning, and sustainability. This dynamic environment ensures that both established and emerging players continually adapt to capture and retain market share in a maturing industry.
Key Players
- Unilever PLC
- Kraft Heinz Company
- Ken’s Foods Inc.
- Tostito’s (PepsiCo)
- Best Foods Mayonnaise
- Heinz
- Bector’s Cremica
- Oasis Foods Company
- Newman’s Own
- Stokes Sauces
Recent Developments
- In April 2025, Hidden Valley introduced seven new ranch dressing varieties with a redesigned applicator bottle, including both widely available and retail-exclusive flavors.
- In 2025, Del Monte UK launched Salad Cream and Light Salad Cream in squeezy bottles, rolling out the range into Asda stores.
- In January 2025, Stonewall Kitchen launched classic salad dressings including French, Blue Cheese, Ranch, and Thousand Island, targeting everyday consumer preferences beyond gourmet products.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Category, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for organic and clean-label salad dressings will continue to expand.
- Retailers will strengthen private label offerings to attract price-sensitive consumers.
- Foodservice adoption of diverse dressing types will rise with menu diversification.
- Online grocery platforms will improve accessibility for premium and niche products.
- Innovation in low-fat, reduced-salt, and sugar-free dressings will gain traction.
- Sustainable and recyclable packaging will become a standard industry expectation.
- Regional preferences will influence new flavor developments tailored to local tastes.
- Strategic partnerships with restaurants and cafés will enhance brand visibility.
- Marketing will emphasize health benefits and natural formulations to build consumer trust.
- Competition between multinational brands and local players will drive continuous innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for UK Salad Dressing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the UK Salad Dressing Market projected to grow between 2025 and 2032?
Which UK Salad Dressing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the UK Salad Dressing Market?
Who are the leading companies in the UK Salad Dressing Market?
Which region commanded the largest share of the UK Salad Dressing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Salad Dressing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Salad Dressing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 969.81 million → forecast year: USD 1,305.09 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Salad Dressing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Salad Dressing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Salad Dressing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Salad Dressing Market Drivers
- 3.3 UK Salad Dressing Market Restraints & Challenges
- 3.4 UK Salad Dressing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Salad Dressing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Salad Dressing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Salad Dressing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Salad Dressing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Salad Dressing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Salad Dressing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Salad Dressing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Salad Dressing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Salad Dressing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Salad Dressing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Salad Dressing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Salad Dressing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Salad Dressing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Salad Dressing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Salad Dressing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Salad Dressing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Salad Dressing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Salad Dressing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Salad Dressing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
