
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
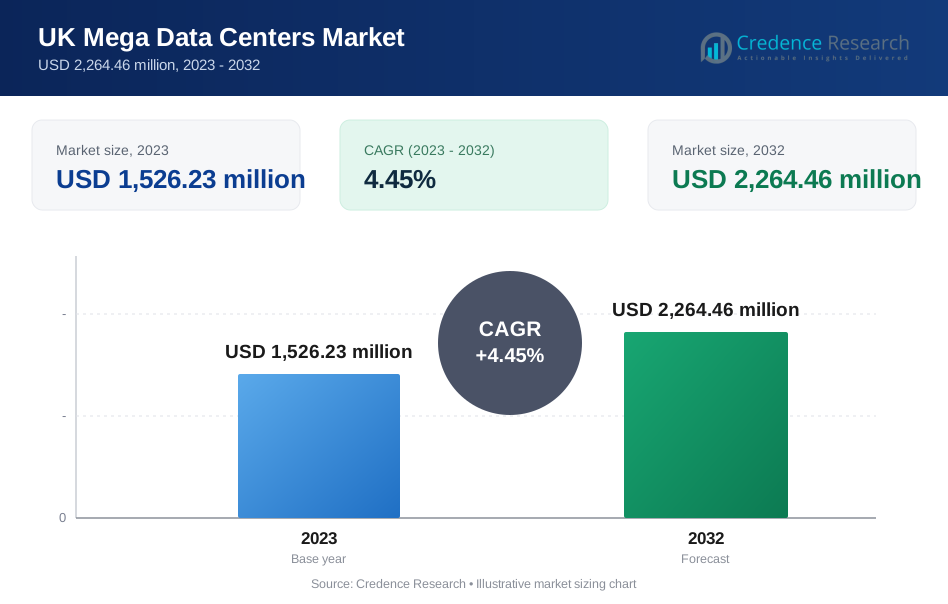
| UK Mega Data Centers Market Size 2023 | USD 1,526.23 Million |
| UK Mega Data Centers Market, CAGR | 4.45% |
| UK Mega Data Centers Market Size 2032 | USD 2,264.46 Million |
Market Overview
The UK Mega Data Centers Market is projected to grow from USD 1,526.23 million in 2023 to an estimated USD 2,264.46 million by 2032, with a compound annual growth rate (CAGR) of 4.45% from 2024 to 2032. This steady expansion reflects the increasing demand for large-scale data processing and storage solutions driven by the digital transformation across various industries.
Key drivers propelling the UK Mega Data Centers Market include the exponential growth of big data analytics, the surge in internet of things (IoT) applications, and the escalating need for robust cybersecurity measures. Additionally, trends such as the shift towards edge computing, increased emphasis on energy-efficient and sustainable data center operations, and the integration of artificial intelligence for optimized performance are shaping the market dynamics. These factors collectively enhance the scalability, reliability, and efficiency of data centers, making them indispensable for businesses seeking to maintain competitive advantage in a data-driven economy.
Geographically, the market is primarily concentrated in major regions including London, Manchester, and Edinburgh, which serve as strategic locations due to their advanced infrastructure and connectivity. The UK government's supportive policies and initiatives aimed at fostering digital innovation further bolster market growth in these areas. Prominent key players in the UK Mega Data Centers Market include Equinix, Digital Realty, Interxion, and Global Switch. These companies are leading the market through continuous investments in cutting-edge technologies, expanding their data center footprints, and forming strategic partnerships to meet the evolving needs of enterprises and support the UK's position as a leading data center destination.
Market Drivers
Accelerated Digital Transformation and Data Proliferation
One of the foremost drivers of the UK Mega Data Centers Market is the accelerated digital transformation across various sectors, leading to an unprecedented surge in data generation and consumption. For instance, the UK currently hosts the largest number of data centers in Western Europe, with the industry generating approximately £4.6 billion in annual revenue. As businesses increasingly adopt digital tools and platforms, the volume of data produced daily has skyrocketed, necessitating robust and scalable data center infrastructures to manage, process, and store this information efficiently. Industries such as finance, healthcare, retail, and telecommunications are particularly reliant on vast data centers to support their operations, analytics, and customer-facing applications. This dependency is clearly illustrated by recent incidents like the CrowdStrike outage, which affected 60% of GP practices, disrupting access to crucial patient information including appointments, prescriptions, and health records. The proliferation of digital services, including e-commerce, online banking, and telemedicine, further amplifies the demand for reliable and high-capacity data centers. Additionally, the rise of digital-native businesses and startups contributes to the sustained need for extensive data storage and processing capabilities, reinforcing the market's growth trajectory. This digital shift not only underscores the necessity for mega data centers but also drives continuous investment in expanding and upgrading existing facilities to handle the ever-increasing data loads.
Expansion of Cloud Computing and Big Data Analytics
The widespread adoption of cloud computing and the increasing reliance on big data analytics are pivotal drivers propelling the UK Mega Data Centers Market. Cloud service providers, including Infrastructure as a Service (IaaS), Platform as a Service (PaaS), and Software as a Service (SaaS) offerings, demand substantial data center resources to deliver scalable and flexible solutions to businesses of all sizes. The shift towards cloud-based infrastructure enables organizations to reduce capital expenditures on physical hardware, enhance operational efficiency, and achieve greater agility in their IT operations. Concurrently, big data analytics requires immense computational power and storage capabilities to process and analyze large datasets, driving the need for advanced data center facilities equipped with high-performance computing resources. The integration of artificial intelligence (AI) and machine learning (ML) within data analytics processes further intensifies the requirement for sophisticated data centers that can support complex algorithms and real-time data processing. Consequently, the synergy between cloud computing and big data analytics fosters a robust demand for mega data centers, facilitating the delivery of comprehensive and high-quality services to end-users.
Government Initiatives and Supportive Regulatory Frameworks
Government initiatives and supportive regulatory frameworks play a crucial role in stimulating the growth of the UK Mega Data Centers Market. The UK government has recognized the strategic importance of data centers in bolstering the nation's digital infrastructure and economic competitiveness, recently designating data centers as the fourteenth critical national infrastructure (CNI) sector, alongside essential services like energy, health, transport, and water. This designation comes with the establishment of a dedicated CNI data infrastructure team comprising senior government officials to monitor and address potential threats. As a result, various policies and incentives have been introduced to attract investments in data center development and expansion. For instance, DC01UK's proposed £3.75 billion investment in Europe's largest data center in Hertfordshire, which will create over 700 local jobs and support 13,740 additional data and tech positions across the country, demonstrates the success of these initiatives. Furthermore, the government's commitment to enhancing digital connectivity, cybersecurity, and data sovereignty aligns with the operational requirements of large-scale data centers, fostering a conducive environment for market growth. Regulatory standards pertaining to data protection, energy efficiency, and environmental sustainability also influence data center design and operations, driving the adoption of advanced technologies and sustainable practices. These government-driven factors not only enhance the attractiveness of the UK as a prime location for mega data centers but also ensure that the market evolves in alignment with national digital and economic objectives.
Technological Advancements and Emphasis on Sustainability
Technological advancements and a growing emphasis on sustainability are significant drivers shaping the UK Mega Data Centers Market. Innovations in data center technologies, such as virtualization, automation, and the Internet of Things (IoT), enhance operational efficiency, scalability, and reliability. The implementation of advanced cooling systems, energy-efficient hardware, and intelligent management software reduces operational costs and minimizes the environmental footprint of data centers. Furthermore, the integration of renewable energy sources, such as solar and wind power, aligns with global sustainability goals and regulatory requirements aimed at reducing carbon emissions. The push towards green data centers not only addresses environmental concerns but also appeals to environmentally conscious businesses and stakeholders, driving demand for sustainable data center solutions. Additionally, advancements in high-density computing, edge computing, and the deployment of 5G networks necessitate data centers with enhanced processing capabilities and reduced latency, further fueling market growth. The continuous evolution of data center technologies ensures that facilities remain capable of meeting the dynamic needs of modern enterprises, thereby sustaining the expansion and modernization of the UK Mega Data Centers Market.
Market Trends
Adoption of Edge Computing and Hybrid Data Architectures
A significant trend within the UK Mega Data Centers Market is the increasing adoption of edge computing and hybrid data architectures. As businesses demand faster data processing and reduced latency to support applications like real-time analytics, Internet of Things (IoT) devices, and autonomous systems, data centers are evolving to incorporate edge computing capabilities. This approach decentralizes data processing by bringing computational power closer to the data source, thereby enhancing performance and reliability. For instance, in March 2022, Hewlett Packard Enterprise announced significant advancements to HPE GreenLake which includes edge computing solutions. Concurrently, hybrid data architectures that integrate on-premises infrastructure with cloud-based services are gaining traction. Organizations are leveraging the flexibility of hybrid models to optimize their data management strategies, balancing the scalability and cost-effectiveness of the cloud with the control and security of local data centers. This dual focus on edge computing and hybrid architectures enables UK mega data centers to meet the diverse and dynamic needs of modern enterprises, fostering innovation and supporting the seamless delivery of digital services across various industries.
Emphasis on Sustainability and Green Data Center Initiatives
Another prominent trend shaping the UK Mega Data Centers Market is the heightened emphasis on sustainability and the implementation of green data center initiatives. With growing awareness of environmental impacts and stringent regulatory requirements, data center operators are prioritizing energy efficiency and the reduction of carbon footprints. Innovations such as advanced cooling technologies, renewable energy integration, and energy-efficient hardware are being widely adopted to minimize power consumption and enhance overall operational sustainability. For instance, Microsoft employs AI algorithms to improve energy efficiency through predictive analytics, allowing servers to enter low-power states during periods of decreased demand. Additionally, the UK government's commitment to achieving net-zero emissions by 2050 has spurred investments in sustainable infrastructure, encouraging data centers to adopt eco-friendly practices. Many UK mega data centers are now pursuing certifications like LEED (Leadership in Energy and Environmental Design) and implementing circular economy principles to further their sustainability goals. These efforts not only align with global environmental standards but also cater to the increasing demand from businesses and consumers for responsible and sustainable digital solutions. For instance, Google's Deepmind AI implementation resulted in a 40% reduction in cooling costs, representing substantial energy savings. By prioritizing sustainability, UK mega data centers are not only reducing their environmental impact but also positioning themselves as leaders in the transition towards a greener and more resilient digital economy. As another example, Huawei used predictive analytics in their China data centres and achieved an eight percent reduction in energy consumption through analyzing historical data and machine learning algorithms.
Market Restraints and Challenges
High Capital Expenditure and Operational Costs
One of the primary restraints facing the UK Mega Data Centers Market is the significant capital expenditure and ongoing operational costs associated with establishing and maintaining large-scale data center facilities. Building a mega data center requires substantial investment in land acquisition, construction, advanced infrastructure, and cutting-edge technologies to ensure high performance, scalability, and security. Additionally, operational expenses such as energy consumption, cooling systems, maintenance, and staffing contribute to the overall financial burden. The UK’s stringent regulatory standards for energy efficiency and data security further escalate costs, as data center operators must invest in state-of-the-art solutions to comply with these requirements. High initial and recurring costs can deter potential investors and limit the market entry of smaller players, thereby consolidating the market among a few dominant firms. Moreover, fluctuations in energy prices and the increasing demand for sustainable energy sources add to the financial challenges, making it difficult for data centers to manage costs while striving to maintain profitability and competitiveness in the market.
Skilled Workforce Shortage and Technological Complexity
Another significant challenge in the UK Mega Data Centers Market is the shortage of skilled professionals and the increasing technological complexity of data center operations. The effective management of mega data centers requires a highly specialized workforce with expertise in areas such as cloud computing, cybersecurity, network management, and advanced data analytics. However, there is a limited pool of qualified professionals available to meet the growing demand, leading to intense competition for talent and elevated labor costs. This shortage can result in delays in project implementation, reduced operational efficiency, and potential vulnerabilities in data security. Additionally, the rapid pace of technological advancements necessitates continuous training and upskilling of existing staff to keep pace with emerging technologies like artificial intelligence, machine learning, and automation. The complexity of integrating new technologies with legacy systems further complicates operations, requiring robust strategies and substantial investment in training and development. These workforce and technological challenges can hinder the ability of data center operators to innovate, scale effectively, and maintain high levels of service quality, thereby posing significant obstacles to the sustained growth of the UK Mega Data Centers Market.
Market Segmentation Analysis
By Component
The UK Mega Data Centers Market by component is divided into solutions and services. Solutions include IT infrastructure solutions such as servers, storage systems, and networking equipment essential for data center operations. Support infrastructure encompasses software and hardware tools for management and monitoring, while power solutions include uninterruptible power supplies (UPS), generators, and power distribution units (PDUs) for continuous operations. Advanced cooling solutions, like liquid cooling and HVAC systems, regulate data center temperatures, and other essential components include security and fire suppression systems. Services include system integration, which unifies hardware and software for cohesive operations, monitoring services for continuous performance management, and professional services like consulting, maintenance, and support to optimize data center efficiency.
By Solution Type
The UK Mega Data Centers Market, by solution type, encompasses a range of essential components: IT infrastructure solutions focus on robust hardware and networking to support large-scale data processing and storage needs; support infrastructure solutions enhance data center management with efficient tools and technologies; power solutions prioritize scalable, reliable systems to ensure continuous operation; cooling solutions employ innovative methods to boost energy efficiency and reduce costs. Additionally, solutions addressing security, fire safety, and other essential requirements help maintain overall data center integrity.
Segments
Based on Component
- Solutions
- Services
Based on Solution Type
- IT Infrastructure Solutions
- Support Infrastructure Solutions
- Power Solutions
- Cooling Solutions
- Others
Based on End User
- Cloud Providers
- Collocation Providers
- Enterprises
Based on Service Type
- System Integration
- Monitoring Services
- Professional Services
Based on Enterprise Size
- Small & Medium Enterprises (SMEs)
- Large Enterprises
Based on Industry Vertical
- Banking, Financial Services & Insurance (BFSI)
- Telecom & IT
- Media & Entertainment
- Government & Public Sector
- Others
Based on Region
- London
- Manchester
- Edinburgh
- Other Regions
Regional Analysis
London (45%)
London holds the largest share of the UK Mega Data Centers Market, accounting for around 45% of the total market. As the financial and business capital of the UK, London benefits from a highly developed infrastructure, making it an attractive location for data center operators. Its proximity to major financial institutions, technology firms, and media organizations drives demand for reliable, high-performance data centers. Additionally, London’s robust connectivity, including high-speed internet and international data links, further cements its position as the leading hub for mega data centers. The region’s concentration of cloud providers, colocation services, and enterprises is a significant driver of market growth, with continuous investment in expanding data center capacity to meet increasing demand.
Manchester (20%)
Manchester is emerging as a key player in the UK Mega Data Centers Market, with an estimated 20% market share. The city’s strategic location, excellent telecommunications infrastructure, and growing tech sector make it an attractive region for data center development. Manchester is increasingly being recognized for its lower operational costs compared to London, making it a favorable destination for companies seeking cost-effective yet highly reliable data center services. The region's growth is further supported by significant investments from global data center providers looking to expand their presence in the North of England. Manchester’s growing reputation as a tech hub and its strong connectivity to major national and international networks are driving the region’s rise as a critical data center market.
Key players
- Cisco Systems Inc.
- Dell Software Inc.
- IBM Corporation
- Intel Corporation
- Juniper Networks Inc.
- Verizon Wireless
- Schneider Electric
- Vertiv Group Corp.
- NetApp
Competitive Analysis
The UK Mega Data Centers Market is highly competitive, with key players like Cisco Systems, Dell Software, IBM Corporation, and Intel Corporation leading the market through innovation, strategic partnerships, and comprehensive service portfolios. Cisco and IBM stand out for their extensive product ranges, which address complex IT infrastructure needs across industries. Meanwhile, Intel and Dell Software provide specialized solutions in computing power and software integration, supporting efficient and scalable data center operations. Schneider Electric and Vertiv Group are prominent for their emphasis on sustainable power and cooling solutions, addressing the growing need for energy efficiency. Juniper Networks and NetApp strengthen their competitive positions through advanced networking and storage technologies, enhancing data management capabilities. Verizon Wireless offers reliable telecommunications infrastructure, supporting connectivity for data centers. Together, these companies create a diverse and innovative landscape, contributing significantly to the overall growth and technological advancement of the UK Mega Data Centers Market.
Recent Developments
- In September 2024, Cisco Systems Inc announced intent to acquire Robust Intelligence to enhance AI security capabilities and accelerate innovation in data centers.
- In July 2024, IBM Corporation acquired SiXworks Limited a UK-based consultancy specializing in digital transformation and secure environments.
- In July 2024, Vertiv Group Corp. Launched MegaMod CoolChip a new liquid cooling-equipped prefabricated modular data center solution designed specifically for AI compute infrastructure.
- In January 2024, HPE announced $14 billion acquisition of Juniper Networks which is currently under investigation by UK Competition and Markets Authority with a deadline of August 14, 2024.
- In June 2024, Cisco Systems Inc. announced a $1 billion global AI investment fund - Acquired Splunk for $28 billion in March 2024.
Market Concentration and Characteristics
The UK Mega Data Centers Market is moderately concentrated, with a mix of dominant global players and regional firms contributing to a competitive landscape. Key players such as Cisco Systems, IBM Corporation, and Schneider Electric hold significant market shares due to their broad portfolios and investments in innovation, infrastructure, and sustainable solutions. The market is characterized by high entry barriers, given the substantial capital investment required, stringent regulatory standards, and the technical expertise needed for managing complex data infrastructure. Furthermore, the demand for scalable, energy-efficient, and secure data centers drives continuous advancements in technology, including cooling solutions, edge computing, and automation, fostering intense competition among established players. The presence of both international and regional companies leads to dynamic market conditions where companies differentiate based on reliability, technological capabilities, and environmental sustainability.
Report Coverage
The research report offers an in-depth analysis based on Component, Solution Type, End User, Service Type, Enterprise Size, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UK Mega Data Centers Market is expected to grow steadily, driven by increasing data demand from digital transformation and expansion of cloud services.
- Edge computing will become integral as businesses seek lower latency, prompting data centers to distribute processing power closer to end-users.
- Emphasis on green practices will intensify, with data centers adopting renewable energy sources, advanced cooling, and energy-efficient hardware to reduce carbon footprints.
- Artificial intelligence (AI) will play a crucial role in optimizing data center operations, from predictive maintenance to energy management, enhancing efficiency and cost-effectiveness.
- As cybersecurity concerns grow, data centers will prioritize enhanced security protocols to protect against evolving threats and ensure compliance with regulatory standards.
- Companies will increasingly rely on colocation services, allowing them to reduce infrastructure costs while leveraging high-capacity data centers for scalability.
- Innovations in cooling technology, such as liquid cooling and AI-controlled temperature management, will improve energy efficiency and support sustainable operations.
- The demand for hybrid cloud architectures will rise, as organizations seek the flexibility of combining on-premises infrastructure with cloud solutions for optimized data management.
- Investments in infrastructure expansion will be crucial as data center operators address rising capacity needs, especially in strategic regions like London and Manchester.
- Government initiatives and regulations will increasingly promote energy efficiency and sustainability, prompting data centers to adopt practices that align with national climate goals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the UK Mega Data Centers Market in 2023 and 2032, and what is its CAGR?
What factors are driving the growth of the UK Mega Data Centers Market?
How does edge computing impact the UK Mega Data Centers Market?
Why is sustainability important in the UK Mega Data Centers Market?
What role does AI play in UK mega data centers?
Which regions in the UK are prominent in the mega data center market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Mega Data Centers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Mega Data Centers Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,526.23 million → 2032: USD 2,264.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Mega Data Centers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Mega Data Centers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Mega Data Centers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Mega Data Centers Market Drivers
- 3.3 UK Mega Data Centers Market Restraints & Challenges
- 3.4 UK Mega Data Centers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Mega Data Centers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Mega Data Centers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Mega Data Centers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Mega Data Centers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Mega Data Centers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Mega Data Centers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Mega Data Centers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Mega Data Centers Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Mega Data Centers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Mega Data Centers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Mega Data Centers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Mega Data Centers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Mega Data Centers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Mega Data Centers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Mega Data Centers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Mega Data Centers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Mega Data Centers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Mega Data Centers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Mega Data Centers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
