
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| US Advanced Battery Energy Storage Systems Market Size 2024 | USD 2,180.66 million |
| US Advanced Battery Energy Storage Systems Market, CAGR | 9.85% |
| US Advanced Battery Energy Storage Systems Market Size 2032 | USD 5,113.95 million |
Market Overview
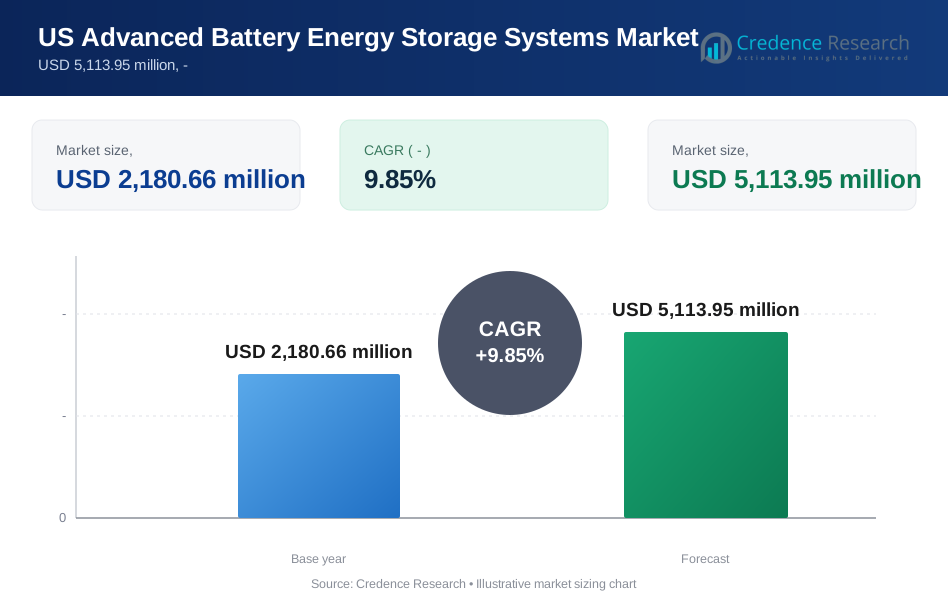
The US Advanced Battery Energy Storage Systems Market is projected to grow from USD 2,180.66 million in 2023 to an estimated USD 5,113.95 million by 2032, with a compound annual growth rate (CAGR) of 9.85% from 2024 to 2032. This substantial growth is attributed to the increasing adoption of renewable energy sources, which necessitates efficient energy storage solutions.
Key market drivers include the rising demand for grid modernization and the integration of renewable energy. The growing need for reliable and efficient energy storage solutions to manage grid stability and ensure a consistent power supply is fueling market growth. Additionally, government incentives and supportive regulatory frameworks are encouraging investments in advanced battery energy storage systems, further boosting market development.
Geographically, the market sees significant contributions from states like California, Texas, and New York, which are leading in renewable energy adoption and grid infrastructure modernization. Key players in the market include Tesla, LG Chem, Panasonic, and Fluence, who are actively engaged in innovation and expanding their product portfolios to cater to the diverse needs of the US market. These companies are also focusing on strategic partnerships and collaborations to strengthen their market position and capitalize on emerging opportunities.
Market Drivers
Increasing Renewable Energy Integration
The integration of renewable energy sources, such as solar and wind power, is a critical driver for the US advanced battery energy storage systems market. Renewable energy is inherently intermittent, with generation dependent on weather conditions and time of day. For instance, the North American Renewable Integration Study (NARIS) informs that in the United States, between 1,200 and 2,000 gigawatts of renewable energy can be deployed to produce 70%–80% of U.S. electricity by 2050 while meeting planning reserve requirements. This variability necessitates the use of energy storage systems to balance supply and demand, ensuring a stable and reliable power grid. Advanced battery systems, particularly lithium-ion batteries, are well-suited for this purpose due to their ability to store large amounts of energy and discharge it rapidly when needed. As the United States continues to pursue aggressive renewable energy targets, the demand for effective energy storage solutions is expected to grow significantly. This trend is supported by federal and state policies aimed at reducing carbon emissions and increasing the share of renewable energy in the overall energy mix.
Grid Modernization and Resilience
Another significant driver is the need for grid modernization and enhanced resilience. The aging infrastructure of the US power grid faces challenges such as capacity constraints, reliability issues, and vulnerability to extreme weather events. For instance, the Department of Energy’s Grid Modernization Initiative is leading the development and execution of programs to deploy approximately $13 billion in funds from the Bipartisan Infrastructure Law (BIL) to finance grid modernization with a focus on improving flexibility, reliability, and resilience against the growing threats of extreme weather and climate change. Advanced battery energy storage systems provide a solution to these challenges by offering grid support services such as frequency regulation, voltage control, and peak shaving. These services enhance grid stability and prevent outages, which are crucial as the demand for electricity continues to rise. Moreover, the ability of these systems to store and dispatch energy during peak demand periods helps in deferring costly grid upgrades and improves the overall efficiency of the energy system. The growing focus on grid resilience, particularly in regions prone to natural disasters, further drives the adoption of advanced battery storage technologies.
Technological Advancements and Cost Reduction
Technological advancements in battery technology are significantly propelling the market. Over the past decade, substantial improvements in battery chemistry, manufacturing processes, and system design have led to increased energy density, longer lifespan, and enhanced safety of battery storage systems. For instance, the National Blueprint for Lithium Batteries 2021-2030 by the U.S. Department of Energy outlines a national blueprint to guide investments in the urgent development of a domestic lithium-battery manufacturing value chain. These advancements have been particularly notable in lithium-ion technology, which dominates the market due to its superior performance characteristics. Concurrently, the costs of battery systems have decreased significantly, making them more economically viable for a wider range of applications, from residential and commercial use to large-scale utility projects. The reduction in costs is attributed to economies of scale in manufacturing, advancements in materials science, and competitive market dynamics. As costs continue to decline, the economic case for deploying advanced battery energy storage systems becomes increasingly compelling, driving market growth.
Supportive Government Policies and Incentives
Government policies and incentives play a crucial role in fostering the adoption of advanced battery energy storage systems. At both federal and state levels, there are numerous initiatives aimed at promoting energy storage as part of broader energy and environmental goals. For instance, the Investment Tax Credit (ITC) has been extended to include standalone energy storage systems, providing a significant financial incentive for their deployment. Additionally, various states have implemented mandates and targets for energy storage capacity, alongside renewable portfolio standards (RPS) that encourage the integration of storage with renewable energy projects. These policies not only provide direct financial incentives but also create a favorable regulatory environment that reduces the risks and uncertainties associated with investing in energy storage technologies. Furthermore, government support for research and development helps accelerate innovation and the commercialization of new technologies, further driving market growth.
Market Trends
Shift Towards Lithium-Ion and Emerging Battery Technologies
The US advanced battery energy storage systems market is witnessing a significant shift towards lithium-ion batteries, which dominate due to their high energy density, long cycle life, and declining costs. Lithium-ion technology has become the preferred choice for a wide range of applications, from residential and commercial installations to large-scale utility projects. This trend is supported by continuous improvements in battery chemistry and manufacturing processes, which enhance performance and safety while driving down costs. For instance, the UK’s first battery strategy, published by the Department for Business & Trade, outlines the government’s commitment to over £2 billion in new capital and R&D funding being made available for the automotive sector, supporting the manufacturing and development of zero-emission vehicles, their batteries and supply chain for 5 years to 2030. Additionally, there is growing interest in emerging battery technologies, such as solid-state batteries and flow batteries, which offer potential advantages in terms of safety, longevity, and scalability. These technologies are still in the developmental stages but hold promise for further transforming the energy storage landscape by providing more efficient and cost-effective solutions.
Increased Focus on Grid-Scale Energy Storage Projects
There is an increasing focus on deploying grid-scale energy storage projects to support the integration of renewable energy sources and enhance grid stability. As utilities and grid operators seek to manage the intermittency of renewables, large-scale battery storage systems are being implemented to provide grid services such as peak shaving, frequency regulation, and backup power. For instance, during 2022, the UK added 800MWh of new utility energy storage capacity, a record level and the start of what promises to be GWh additions out to 2030 and beyond. This trend is particularly pronounced in regions with high renewable energy penetration, such as California and Texas, where storage systems are crucial for maintaining grid reliability and preventing blackouts. The rise of grid-scale projects is also driven by regulatory frameworks that encourage energy storage deployment and by utility companies' growing recognition of storage systems as a cost-effective alternative to traditional grid infrastructure investments. Furthermore, the development of energy storage as a service (ESaaS) models is emerging, allowing customers to access the benefits of advanced storage technologies without the upfront capital investment, thereby broadening the market's accessibility and appeal.
Market Restraints and Challenges
High Initial Capital Costs
One of the key restraints in the US advanced battery energy storage systems market is the high initial capital cost associated with these systems. Despite significant reductions in battery prices over the past decade, the upfront costs remain substantial, particularly for large-scale installations. These costs include not only the batteries themselves but also associated infrastructure, such as inverters, control systems, and installation expenses. For many potential users, especially in residential and small commercial segments, these high costs can be a significant barrier to adoption. Furthermore, the cost of energy storage systems can be higher when integrated with renewable energy projects, where the need for battery storage to manage intermittency adds to the overall project cost. While incentives and financing options are available, the economic viability of these systems often hinges on specific use cases and local electricity pricing structures, limiting broader market penetration.
Regulatory and Market Uncertainties
Regulatory and market uncertainties also pose significant challenges to the growth of the US advanced battery energy storage systems market. The regulatory environment for energy storage is complex and varies widely across states and regions. Inconsistent policies, lack of standardized regulations, and varying levels of support for energy storage projects create uncertainty for investors and developers. This inconsistency can affect the financial viability and operational feasibility of storage projects, as developers must navigate a patchwork of regulations and incentives. Additionally, the evolving nature of electricity markets, including changing tariffs, demand charges, and grid service compensation mechanisms, adds another layer of uncertainty. These factors can impact the revenue streams and economic returns of energy storage systems, making it challenging for stakeholders to plan and invest with confidence. Overcoming these regulatory and market challenges requires coordinated efforts from policymakers, industry stakeholders, and utilities to create a more stable and supportive framework for energy storage deployment.
Market Segmentation Analysis
By Type
The US advanced battery energy storage systems market features a diverse range of technologies. Lithium-ion batteries lead the market due to their high energy density, long cycle life, and decreasing costs, making them ideal for applications from residential storage to large-scale grid installations. Lead-acid batteries, while more affordable and traditional, are less favored for advanced applications because of their lower energy density and shorter lifespan; they are mostly used in cost-sensitive environments with less demanding performance criteria. Sodium sulfur batteries provide high energy density and long discharge durations, suited for large-scale and industrial storage, though their market is constrained by high operating temperatures and safety concerns. Nickel-cadmium batteries are valued for their durability and reliability in niche applications but are limited by environmental concerns and the availability of more efficient alternatives. The "Others" category encompasses emerging technologies such as flow and solid-state batteries, which are attracting interest for their potential in improved safety, longevity, and performance.
By Application
The US advanced battery energy storage systems market is driven by diverse applications across various segments. The electric vehicle market significantly boosts demand due to the need for high energy density, fast charging, and long battery life. In the utility sector, battery storage is essential for grid stability, peak shaving, and integrating renewable energy sources, addressing the challenges of intermittency. The residential segment is expanding as homeowners seek backup power and efficient energy management, particularly in areas with high electricity costs or unreliable grids. Additionally, the commercial and industrial sectors use battery storage for demand charge reduction, backup power, and enhancing power quality.
Segments
Based on Type
- Lithium-Ion Battery Energy Storage Systems
- Lead-Acid Battery Energy Storage Systems
- Sodium Sulfur Battery Energy Storage Systems
- Nickel Cadmium Battery Energy Storage Systems
- Other Battery Energy Storage Systems
Based on Application
- Transportation (Electric Vehicles)
- Utility
- Residential
- Others
Based on Storage Type
- Batteries
- Flywheels
- Compressed Air Storage
- Pumped Hydro-Power
- Others
Based on Technology
- Mechanical
- Thermal
- Electro Chemical
- Others
Based on Region
- California
- Texas
- New York
Regional Analysis
California (35%):
California leads the US market, holding approximately 35% of the share. This dominance is attributed to the state's aggressive renewable energy targets and supportive regulatory environment. California has set ambitious goals for reducing greenhouse gas emissions and increasing the share of renewable energy in its power mix, which has spurred substantial investments in energy storage solutions. The state's initiatives, such as the California Public Utilities Commission's (CPUC) energy storage mandates, and its commitment to integrating solar and wind power, drive high demand for advanced battery storage systems. Additionally, California's high electricity prices and frequent power outages create a robust market for residential and commercial energy storage solutions.
Texas (25%):
Texas holds around 25% of the market share, driven by its vast renewable energy resources and significant investments in energy storage. The state's deregulated energy market and large-scale wind farms make it a prime candidate for advanced battery storage to manage intermittent renewable generation and ensure grid stability. Texas has seen considerable growth in utility-scale battery storage projects, particularly in areas with high renewable penetration. The state's focus on energy independence and grid resilience further supports the demand for advanced battery systems.
Key players
- ABB
- AES Energy Storage
- Exide Technologies
- SAFT
- Beckett Energy Systems
- General Electric
- LG Chem
- Toshiba
- Siemens
- BYD Company
- NEC Corporation
- AEG Power Solutions
Competitive Analysis
The US advanced battery energy storage systems market is highly competitive, featuring key players with distinct strengths. ABB, General Electric, and Siemens leverage their extensive industrial expertise and global reach to offer comprehensive energy storage solutions, focusing on grid integration and utility-scale applications. LG Chem and BYD Company lead in lithium-ion battery technologies, known for their high energy density and scalability. AES Energy Storage and SAFT are prominent in deploying advanced storage technologies with an emphasis on large-scale projects and innovative solutions. Exide Technologies and Beckett Energy Systems cater to niche markets with reliable and cost-effective options. NEC Corporation and AEG Power Solutions contribute with cutting-edge technology and diverse product portfolios. This competitive landscape underscores the importance of technological innovation and strategic partnerships in driving market growth.
Recent Developments
In December 2022, the Australian government unveiled a significant initiative to bolster the national grid and stabilize energy prices by constructing eight large-scale batteries across the country. With nearly USD 120 million in funding from the Australian Renewable Energy Agency (Arena), these batteries will be installed in Victoria (Gnarwarre, Moorabool, Mortlake), Queensland (Mount Fox, Western Downs), New South Wales (Liddell), and South Australia (Bungama, Blyth). Each battery will have a storage capacity of 200-300 MWh and feature advanced grid-forming inverter technology, with plans for all units to be operational by 2025.
In February 2023, Power & Air Solutions, a subsidiary of Deutsche Telekom, completed its first battery energy storage system (BESS) installation supplied by Pixii. The system, installed at Deutsche Telekom's main office in Munich, Germany, features a 1 MW conversion capacity and 6 MWh of storage capacity. This installation marks a significant step for Deutsche Telekom in integrating advanced energy storage solutions to enhance energy efficiency and reliability at their facilities.
In January 2024, Grenergy and BYD announced a strategic partnership to deliver 1.1 GWh of energy storage systems (ESS). This collaboration includes the deployment of 2,136 units of BYD’s high-performance MC Cube ESS model, which utilizes Blade batteries renowned for their safety and longevity. The partnership aims to advance energy storage solutions, enhancing grid stability and energy management capabilities.
In January 2023, Sweden’s Sara Kulturhus, a prominent cultural center, became powered by an innovative battery energy storage system (BESS) developed by ABB in collaboration with Skellefteå Kraft. Designed to meet the unique needs of the venue, the BESS includes a transformer, six Northvolt battery packs, ABB’s AC and DC switchgear, and EPC Power inverters. This system provides reliable, eco-friendly electricity, showcasing advanced engineering and tailored solutions for cultural and community facilities.
In May 2022, Toshiba Corporation launched the 125VDC SCiB Energy Storage System (ESS), incorporating Lithium Titanium Oxide (LTO) battery technology with a versatile and expandable cabinet design. The Toshiba 125VDC SCiB ESS is available in capacities of 5kWh, 10kWh, 15kWh, and 20kWh, making it suitable for various applications, including Uninterruptible Power Systems (UPS) and DC Load applications. This system is designed to offer reliable and flexible energy storage solutions for diverse operational needs.
Market Concentration and Characteristics
The US advanced battery energy storage systems market exhibits moderate to high concentration, with several key players dominating the landscape, including ABB, LG Chem, and BYD Company. These major firms lead through technological innovation, extensive R&D investments, and substantial market presence. The market is characterized by a diverse range of technologies and applications, from lithium-ion and flow batteries to mechanical and thermal storage solutions. The competitive environment is driven by the need for scalable, cost-effective solutions that address grid stability, renewable energy integration, and peak shaving. Market characteristics also include rapid technological advancements, evolving regulatory frameworks, and significant investment in infrastructure, reflecting a dynamic and rapidly evolving sector.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Storage Type, Technology and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The US advanced battery energy storage systems market is expected to see substantial growth, driven by the rising need for grid stability and renewable energy integration. As energy storage becomes more economically viable, adoption rates will increase across various sectors.
- Continuous innovations in battery technologies, such as solid-state and flow batteries, will enhance performance, safety, and energy density. These advancements will contribute to more efficient and cost-effective storage solutions.
- The cost of battery storage systems is projected to decrease due to advancements in manufacturing and economies of scale. This reduction in costs will make energy storage solutions more accessible to a broader range of consumers and industries.
- Expanding government incentives and supportive policies will drive market growth. Federal and state-level initiatives aimed at increasing renewable energy usage will bolster the demand for advanced battery storage solutions.
- Significant investments in utility-scale energy storage projects will continue, helping to balance supply and demand and integrate intermittent renewable energy sources into the grid more effectively.
- The residential and commercial sectors will see increased adoption of battery storage systems as consumers seek energy independence and cost savings. Rising electricity prices and power reliability concerns will further fuel this growth.
- The growing electric vehicle market will create additional demand for battery storage systems. Vehicle-to-grid (V2G) technologies will enable EVs to contribute to grid stability and energy storage.
- The integration of advanced energy management systems with battery storage will enhance efficiency and operational control. These systems will optimize energy use, reduce costs, and improve reliability.
- Efforts to modernize the US power grid will drive the deployment of advanced battery storage. Enhanced grid infrastructure will facilitate the integration of diverse energy sources and improve overall grid resilience.
- Increased global competition and international partnerships will stimulate innovation and market expansion. Collaboration between US companies and global players will accelerate the development and deployment of advanced battery technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Renewable Energy Integration
The rapid adoption of solar and wind power in the US creates a need for advanced battery energy storage systems to manage the intermittent nature of renewables, ensuring grid stability and reliability.
Grid Modernization and Resilience
Aging grid infrastructure and the rising frequency of extreme weather events are driving investments in battery storage to provide grid support services like frequency regulation, voltage control, and backup power, enhancing overall grid resilience.
Technological Advancements and Cost Reduction
Continuous improvements in battery chemistry, manufacturing, and system design have increased energy density and lifespan while reducing costs, making advanced battery storage more accessible for utility, commercial, and residential applications.
Supportive Government Policies and Incentives
Federal and state-level incentives, such as the Investment Tax Credit for standalone storage and state storage mandates, are accelerating market growth by reducing financial barriers and encouraging investment in advanced battery systems.
Growth of Electric Vehicles and Vehicle-to-Grid Integration
The expanding electric vehicle market is boosting demand for high-performance battery storage, while emerging vehicle-to-grid technologies enable EVs to contribute to grid stability and energy management.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the US advanced battery energy storage systems market?
What are the primary drivers for growth in this market?
Which states are leading in the adoption of advanced battery energy storage systems?
How do technological advancements impact the market for advanced battery storage systems?
What challenges does the market face despite its growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Lithium-Ion Battery Energy Storage Systems
- 1.2.2 Lead-Acid Battery Energy Storage Systems
- 1.2.3 Sodium Sulfur Battery Energy Storage Systems
- 1.2.4 Nickel Cadmium Battery Energy Storage Systems
- 1.2.5 Other Battery Energy Storage Systems
- 1.3 By Application
- 1.3.1 Transportation (Electric Vehicles)
- 1.3.2 Utility
- 1.3.3 Residential
- 1.3.4 Others
- 1.4 By Storage Type
- 1.4.1 Batteries
- 1.4.2 Flywheels
- 1.4.3 Compressed Air Storage
- 1.4.4 Pumped Hydro-Power
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 2,180.66 million → 2032: USD 5,113.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 US Advanced Battery Energy Storage Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 US Advanced Battery Energy Storage Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 US Advanced Battery Energy Storage Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 US Advanced Battery Energy Storage Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 US Advanced Battery Energy Storage Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 US Advanced Battery Energy Storage Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 US Advanced Battery Energy Storage Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 US Advanced Battery Energy Storage Systems Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 2,180.66 million → 2032: USD 5,113.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 US Advanced Battery Energy Storage Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Lithium-Ion Battery Energy Storage Systems
- 12.3.7.2 Lead-Acid Battery Energy Storage Systems
- 12.3.7.3 Sodium Sulfur Battery Energy Storage Systems
- 12.3.7.4 Nickel Cadmium Battery Energy Storage Systems
- 12.3.7.5 Other Battery Energy Storage Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transportation (Electric Vehicles)
- 12.4.7.2 Utility
- 12.4.7.3 Residential
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Storage Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Batteries
- 12.5.7.2 Flywheels
- 12.5.7.3 Compressed Air Storage
- 12.5.7.4 Pumped Hydro-Power
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 US Advanced Battery Energy Storage Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 US Advanced Battery Energy Storage Systems Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 US Advanced Battery Energy Storage Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 US Advanced Battery Energy Storage Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Tesla
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG Chem
- 18.4 Panasonic
- 18.5 Fluence
- 18.6 ABB
- 18.7 General Electric
- 18.8 Siemens
- 18.9 BYD Company
- 18.10 AES Energy Storage
- 18.11 NEC Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

