
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
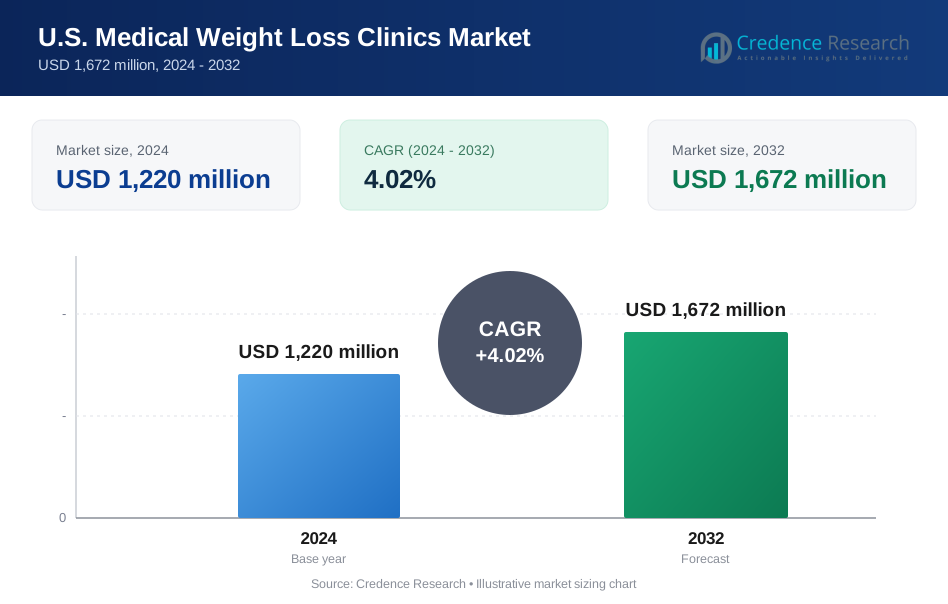
| U.S. Medical Weight Loss Clinics Market Size 2024 | USD 1,220 million |
| U.S. Medical Weight Loss Clinics Market, CAGR | 4.02% |
| U.S. Medical Weight Loss Clinics Market Size 2032 | USD 1,672 million |
Market Overview
The U.S. Medical Weight Loss Clinics Market is projected to grow from USD 1,220 million in 2024 to USD 1,672 million by 2032, registering a CAGR of 4.02% during the forecast period.
The U.S. Medical Weight Loss Clinics Market is experiencing steady growth driven by increasing obesity rates, heightened awareness of associated health risks, and a growing preference for medically supervised weight management programs. Rising adoption of prescription-based treatments, including GLP-1 receptor agonists, is enhancing clinic-based offerings and expanding patient reach. An aging population and the prevalence of chronic conditions such as diabetes and cardiovascular diseases are also prompting individuals to seek professional weight loss support. Furthermore, advancements in telehealth are enabling greater accessibility to medical weight loss services, especially in underserved areas. Clinics are increasingly integrating behavioral counseling, nutritional guidance, and personalized care plans to improve long-term outcomes. The market is also benefiting from supportive reimbursement policies and shifting consumer attitudes favoring clinical interventions over commercial diet programs. As competition intensifies, clinics are leveraging technology and data analytics to offer customized treatment pathways, improve engagement, and ensure compliance, thereby strengthening their position in the evolving healthcare landscape.
The Medical Weight Loss Clinics Market (U.S.) demonstrates strong regional variation, with the South holding the largest share at 33%, followed by the Northeast at 26%, the West at 21%, and the Midwest at 20%. Growth in the South is fueled by rising obesity rates and expanding access to standalone clinics, while the Northeast benefits from established hospital-based programs and higher health awareness. The West leads in wellness-focused, tech-enabled models, and the Midwest sees steady demand driven by chronic disease management and rural outreach. Key players driving market growth include Cleveland Clinic, Stanford Health Care, NYU Langone Hospitals, UCLA Health, Cedars-Sinai, Allegheny Health Network, Medi-Weightloss, Medical Weight Loss Clinic, Rivas Weight Loss, Long Island Weight Loss Institute, Options Medical Weight Loss, and Med-Fit Medical Weight Loss. These providers compete by offering personalized care, leveraging digital platforms, and expanding into underserved areas to strengthen national presence.
Market Insights
- The U.S. Medical Weight Loss Clinics Market is projected to grow from USD 1,220 million in 2024 to USD 1,672 million by 2032, registering a CAGR of 4.02% during the forecast period.
- Rising obesity rates, chronic conditions, and increased awareness of health risks are driving demand for medically supervised weight loss programs across the country.
- The adoption of prescription-based therapies, particularly GLP-1 receptor agonists, is expanding clinical treatment offerings and improving weight loss outcomes.
- Integration of telehealth services is enhancing access to care in rural and underserved regions, strengthening patient engagement and continuity of treatment.
- High treatment costs and limited insurance coverage remain major challenges, making affordability and reimbursement key concerns for long-term patient adherence.
- The South leads the market with 33% share, followed by the Northeast (26%), West (21%), and Midwest (20%), reflecting diverse regional dynamics and healthcare access.
- Key players such as Cleveland Clinic, NYU Langone Hospitals, Medi-Weightloss, and Options Medical Weight Loss are competing through personalized care, digital tools, and nationwide expansion strategies.
Market Drivers
Rising Prevalence of Obesity and Related Health Conditions
The Medical Weight Loss Clinics Market (U.S.) is expanding due to a significant increase in obesity rates and associated comorbidities such as type 2 diabetes, hypertension, and cardiovascular disorders. This surge in health complications is prompting more individuals to seek clinical weight management solutions rather than relying on commercial programs. Medical weight loss clinics offer evidence-based, physician-supervised treatments that address root causes of weight gain and improve long-term health outcomes. Patients increasingly value the safety and personalization these clinics provide. Public health campaigns and rising awareness of obesity-related risks are further encouraging early intervention through medical channels.
- For instance, Cleveland Clinic’s Obesity and Medical Weight Loss Center offers personalized, non-surgical programs that combine nutrition, exercise, behavioral therapy, and prescription medication management, helping thousands of patients not only lose weight but also improve or resolve chronic conditions such as type 2 diabetes and hypertension.
Growing Demand for Prescription-Based Therapies
GLP-1 receptor agonists and other FDA-approved anti-obesity medications are transforming the scope of treatments offered by medical weight loss clinics. The Medical Weight Loss Clinics Market (U.S.) is benefiting from this trend, as clinics incorporate pharmacological options into comprehensive care plans. These therapies are clinically proven to enhance weight loss outcomes, making them an attractive option for patients seeking effective and safe interventions. Clinics are also seeing more insurance support for these prescriptions, which improves affordability and boosts patient enrollment. Physicians use diagnostic assessments to determine the most suitable medications, creating individualized approaches.
Telehealth Integration Enhancing Accessibility and Engagement
Wider integration of telehealth services is transforming patient access across the Medical Weight Loss Clinics Market (U.S.). Virtual consultations and remote monitoring tools now enable clinics to serve patients in both urban and rural areas, removing traditional barriers to care. This digital shift also enhances continuity, allowing clinicians to monitor progress, adjust treatments, and provide timely support. Patients appreciate the convenience and flexibility of hybrid programs combining in-person visits with online follow-ups. It is improving adherence and strengthening patient-provider relationships. Clinics are investing in secure platforms and digital infrastructure to optimize these services.
- For instance, WeightWatchers launched its Virtual Clinic in 2023, offering remote physician consultations and digital prescription management, which led to a 35% increase in patient engagement within six months (WeightWatchers, 2023).
Shifting Consumer Preferences Toward Medically Supervised Programs
Patients are increasingly favoring medical weight loss programs due to dissatisfaction with short-term, unsustainable results from commercial diets. The Medical Weight Loss Clinics Market (U.S.) is seeing a growing preference for physician-led, data-driven interventions that align with personal health goals. Consumers value the credibility, safety, and effectiveness of clinical programs, particularly those offering multidisciplinary care teams. Emotional and psychological support, nutritional counseling, and lifestyle coaching are often integrated, making these programs holistic and outcome-focused. This shift is influencing market competition, prompting clinics to prioritize individualized care and patient satisfaction. It is fostering long-term engagement and encouraging repeat visits.
Market Trends
Integration of GLP-1 Therapies into Clinical Programs
Clinics are increasingly incorporating GLP-1 receptor agonists into their treatment protocols to improve patient outcomes. These medications, originally developed for diabetes, have gained FDA approval for weight management due to their proven efficacy in reducing body weight. The Medical Weight Loss Clinics Market (U.S.) is embracing this trend by pairing pharmacological treatments with behavioral counseling and lifestyle interventions. Clinics report improved retention and success rates with these drug-assisted programs. Patients are showing strong interest in medically supervised options that combine pharmaceutical innovation with clinical oversight.
- For instance, Mayo Clinic began prescribing semaglutide (Wegovy®) for weight management in 2022, reporting average weight loss of up to 15% among patients following a combined regimen of medication and lifestyle modification.
Expansion of Hybrid and Virtual Care Models
The demand for hybrid care models is rising, with clinics offering a mix of in-person consultations and telehealth services. Patients prefer the flexibility of remote access for follow-ups, nutrition advice, and behavior modification support. The Medical Weight Loss Clinics Market (U.S.) is adapting to this shift by deploying digital platforms that enable real-time communication and progress tracking. This model enhances patient engagement and reduces dropout rates. Clinics are leveraging technology to personalize care and maintain consistent contact with clients. It is increasing scalability without compromising quality or supervision.
- For instance, Access Plus Health, which partners with clinics to implement hybrid models that streamline patient engagement and expand care access by integrating telehealth with traditional services.
Focus on Personalized and Data-Driven Treatment Plans
Medical weight loss clinics are moving away from one-size-fits-all approaches by using health data, diagnostics, and metabolic assessments to tailor treatment. The Medical Weight Loss Clinics Market (U.S.) reflects a growing trend toward personalization, where clinicians design weight management plans based on individual profiles, genetic markers, and comorbid conditions. This approach ensures higher treatment efficacy and improves patient satisfaction. Clinics are investing in tools and staff training to support this model. It is positioning personalized care as a competitive differentiator across the market. Patients are responding positively to treatments that reflect their unique health status.
Increased Emphasis on Behavioral and Lifestyle Support
Behavioral modification is gaining traction as an essential component of sustainable weight loss, prompting clinics to embed it into standard care. The Medical Weight Loss Clinics Market (U.S.) is emphasizing counseling, stress management, and habit restructuring alongside medical interventions. Clinics are hiring licensed therapists, health coaches, and nutritionists to provide a multidisciplinary approach. This trend reflects a broader shift toward long-term wellness rather than short-term results. Patients are seeking programs that address the psychological and emotional roots of obesity. It is fostering deeper patient engagement and improving retention and clinical success rates.
Market Challenges Analysis
High Cost of Treatment and Limited Insurance Coverage
Many patients face financial barriers when accessing medical weight loss services due to the high cost of treatment and limited insurance reimbursement. The Medical Weight Loss Clinics Market (U.S.) must address affordability concerns, especially for prescription-based therapies like GLP-1 medications. While some insurance plans offer partial coverage, inconsistencies across providers create gaps in access. Out-of-pocket expenses often deter long-term commitment to clinic-based programs. Clinics must navigate complex reimbursement policies while trying to maintain profitability. It creates a challenge in scaling services equitably across different socioeconomic groups.
Regulatory Hurdles and Clinical Oversight Requirements
Strict regulatory guidelines and the need for qualified medical supervision limit the ability of clinics to expand rapidly. The Medical Weight Loss Clinics Market (U.S.) must comply with evolving federal and state-level healthcare regulations that govern the use of controlled medications and telehealth protocols. Clinics require licensed physicians, registered dietitians, and behavioral health specialists to meet care standards, increasing operational complexity and costs. Staffing shortages and credentialing delays further restrict clinic capacity. It makes market entry difficult for new providers and slows down geographic expansion for established brands.
- For instance, the launch of NovoCare Pharmacy by Novo Nordisk required strict adherence to FDA guidance and quality control standards to ensure regulatory compliance for direct-to-patient delivery of Wegovy®, demonstrating how operational complexity rises as companies expand access while meeting oversight requirements.
Market Opportunities
Rising Demand for Holistic and Preventive Health Solutions
The growing awareness of preventive healthcare presents a major opportunity for the Medical Weight Loss Clinics Market (U.S.). Consumers are shifting focus toward long-term wellness and chronic disease prevention, creating demand for services that extend beyond weight loss. Clinics can expand their offerings to include metabolic health management, nutritional therapy, and mental wellness programs. This holistic approach aligns with patient expectations and differentiates providers from commercial alternatives. It allows clinics to establish recurring patient engagement and improve outcomes. Providers who integrate wellness coaching and lifestyle support can attract a broader client base.
Untapped Potential in Underserved and Rural Areas
Large segments of the U.S. population lack access to medically supervised weight loss services, particularly in rural and underserved regions. The Medical Weight Loss Clinics Market (U.S.) can address this gap by leveraging telehealth and mobile clinics to reach these communities. Expanding into these areas provides an opportunity to build brand presence and patient trust where competition is low. Clinics that offer flexible care models and culturally tailored services can gain early-mover advantage. It supports both growth and social impact. Strategic partnerships with local health providers can further accelerate market entry.
Market Segmentation Analysis:
By Hospital-Based Ownership
Hospital-based clinics play a key role in the Medical Weight Loss Clinics Market (U.S.), leveraging their access to multidisciplinary teams and advanced diagnostic capabilities. These clinics benefit from integrated care models that allow seamless coordination between physicians, dietitians, and behavioral health specialists. Hospitals often attract patients with complex medical conditions who require close monitoring and specialized treatment plans. The presence of accredited facilities and established trust further boosts patient confidence. It enables hospital-based programs to offer comprehensive weight management solutions aligned with broader chronic disease care. These clinics also benefit from insurance partnerships that support long-term patient retention.
By Standalone Ownership
Standalone clinics represent a growing segment in the Medical Weight Loss Clinics Market (U.S.), driven by their ability to offer flexible, patient-centric services. These facilities often provide quicker access, tailored treatment plans, and competitive pricing, appealing to a wide consumer base. Independent providers are agile in adopting new technologies and personalized approaches, including telehealth integration and digital progress tracking. Standalone clinics focus on customer experience and branding, allowing them to differentiate in a competitive landscape. It positions them to attract health-conscious individuals seeking non-hospital environments. Market growth in this segment is fueled by increasing consumer demand for convenience and specialized care.
Segments:
Based on Ownership
- Hospital-based
- Standalone
Based on Geography
- Northeast
- Southeast
- Southwest
- Midwest
- West
Regional Analysis
Northeast
The Northeast holds 26% share of the Medical Weight Loss Clinics Market (U.S.), supported by high urban population density, greater health awareness, and strong insurance coverage. Major metropolitan areas like New York and Boston are home to established hospital-affiliated weight loss programs and advanced specialty clinics. Consumers in this region show a strong preference for clinically supervised treatments over commercial alternatives. The presence of leading academic medical centers also drives innovation in obesity management. It creates opportunities for evidence-based, multidisciplinary care models. The demand for GLP-1 therapies and telehealth-based weight loss programs continues to grow across both urban and suburban populations.
South
The South accounts for 33% share of the Medical Weight Loss Clinics Market (U.S.), driven by higher obesity prevalence and a growing number of lifestyle-related chronic diseases. States such as Texas, Florida, and Georgia are witnessing rapid expansion of standalone clinics offering personalized, cost-effective care. The region’s large and diverse population fuels demand for culturally tailored weight loss programs. Telehealth adoption is improving access in rural areas, where in-person clinics remain limited. It positions providers to bridge critical care gaps. Hospital systems are also launching weight management divisions to capture this expanding segment of the healthcare market.
West
The West holds 21% share of the Medical Weight Loss Clinics Market (U.S.), with California leading clinic expansion due to its progressive health culture and strong demand for preventive care. Consumers in this region prioritize holistic and integrative approaches that combine medical treatment with lifestyle coaching. Standalone clinics are leveraging digital tools and wellness programs to build loyalty and attract younger, tech-savvy patients. Urban centers such as Los Angeles, San Diego, and Seattle serve as growth hubs. It drives the development of hybrid models blending virtual and in-person care. The market remains competitive with ongoing innovation in personalized weight loss services.
Midwest
The Midwest captures 20% share of the Medical Weight Loss Clinics Market (U.S.), supported by expanding insurance access and growing awareness of obesity-related health risks. Cities like Chicago, Minneapolis, and Detroit are seeing increased investment in both hospital-based and standalone clinics. The region’s aging population and prevalence of metabolic conditions create a steady need for long-term, physician-supervised programs. Clinics are working to improve outreach and engagement in rural communities. It helps drive market penetration where access has historically been limited. The Midwest shows steady growth with rising demand for evidence-backed and accessible weight loss solutions.
Key Player Analysis
- Rivas Weight Loss
- NYU Langone Hospitals
- Options Medical Weight Loss
- Stanford Health Care
- Long Island Weight Loss Institute
- Cedars-Sinai
- Medi-Weightloss
- Allegheny Health Network
- Medical Weight Loss Clinic
- UCLA Health
- Med-Fit Medical Weight Loss
- Cleveland Clinic
Competitive Analysis
The Medical Weight Loss Clinics Market (U.S.) features a competitive landscape comprising both hospital-affiliated programs and standalone providers. Leading players such as Cleveland Clinic, Stanford Health Care, and NYU Langone Hospitals offer comprehensive, physician-led services supported by advanced diagnostics and multidisciplinary care teams. Standalone clinics like Medi-Weightloss, Medical Weight Loss Clinic, and Options Medical Weight Loss focus on customized treatment plans, flexible pricing, and strong patient engagement. It allows them to attract a broader demographic seeking accessible care. Clinics are increasingly investing in telehealth platforms, prescription-based therapies, and wellness integrations to enhance outcomes and retention. Strategic expansion into underserved regions and digital transformation are key tactics shaping competition. Brand reputation, clinical outcomes, and patient satisfaction remain critical differentiators. The market continues to evolve as providers compete on innovation, convenience, and personalized care delivery.
Recent Developments
- In January 2024, Hims & Hers Health ventured into the weight loss segment, introducing a subscription-based program that includes virtual medical consultations and prescription treatments such as semaglutide.
- In February 2024, Calibrate, a telehealth firm focused on GLP-1-based weight loss solutions, raised $70 million in Series C funding to expand its clinical services and enhance its digital platform nationwide.
- In March 2024, Red Mountain Weight Loss responded to rising demand in the Southwest by opening five new clinics across Texas, reinforcing its commitment to medically supervised weight loss.
- In April 2024, Sequence Health strengthened its collaboration with WeightWatchers, launching a new hybrid model that combines prescription-based GLP-1 therapies with behavioral coaching.
- In December 2023, the Obesity Care Advocacy Network (OCAN) intensified its efforts to reform healthcare policy by lobbying for broader Medicare coverage of anti-obesity medications, aiming to improve access for aging populations.
Market Concentration & Characteristics
The Medical Weight Loss Clinics Market (U.S.) exhibits a moderately fragmented structure, with a mix of hospital-affiliated programs and independent clinics competing for market share. The presence of large healthcare institutions like Cleveland Clinic and NYU Langone Hospitals provides strong clinical credibility and access to advanced treatment resources. At the same time, standalone providers such as Medi-Weightloss and Options Medical Weight Loss are gaining ground through patient-centric models and flexible service delivery. The market favors players that can offer customized, multidisciplinary care integrating medical, nutritional, and behavioral support. It continues to evolve with growing demand for virtual services and prescription-based therapies, which are reshaping competitive dynamics. Brand reputation, treatment efficacy, and technological integration are critical differentiators. The Medical Weight Loss Clinics Market (U.S.) operates under stringent regulatory oversight, requiring licensed professionals and adherence to safety standards. It fosters a competitive environment focused on innovation, patient outcomes, and expansion into underserved markets.
Report Coverage
The research report offers an in-depth analysis based on Ownership and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for medically supervised weight loss programs will continue to rise due to increasing obesity and related health conditions.
- Clinics will expand the use of GLP-1 and other prescription therapies to improve treatment outcomes.
- Telehealth services will become a standard feature in clinic operations, enhancing access and convenience.
- Integration of behavioral and nutritional counseling will strengthen the effectiveness of care plans.
- More clinics will adopt data-driven tools to create personalized and adaptive weight management programs.
- Providers will increase their presence in rural and underserved regions through virtual and mobile care models.
- The market will see greater involvement from insurance providers, improving affordability and coverage.
- Standalone clinics will continue to innovate in service delivery to compete with hospital-based programs.
- Consumer preference will shift further toward holistic care models focused on long-term wellness.
- Regulatory compliance and clinical oversight will remain crucial for operational sustainability and expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Obesity and Chronic Disease Prevalence
The increasing rates of obesity and related chronic conditions such as type 2 diabetes and cardiovascular disease are prompting more individuals to seek medically supervised weight loss solutions, fueling demand for clinic-based programs.
Adoption of Prescription-Based Therapies (GLP-1 Agonists)
The integration of FDA-approved anti-obesity medications, especially GLP-1 receptor agonists, into clinic offerings is improving weight loss outcomes and attracting patients seeking effective, physician-supervised interventions.
Expansion of Telehealth and Virtual Care Models
Advancements in telehealth are enabling clinics to reach underserved and rural populations, increasing accessibility and patient engagement through hybrid and fully virtual care options.
Shift Toward Personalized and Holistic Care
Consumers are increasingly favoring individualized, multidisciplinary programs that combine medical, nutritional, and behavioral support, driving clinics to differentiate through tailored, outcome-focused care plans.
Supportive Reimbursement and Policy Changes
Gradual improvements in insurance coverage and advocacy for broader reimbursement of anti-obesity treatments are making medical weight loss programs more affordable and accessible, supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Medical Weight Loss Clinics Market (U.S.) market?
What factors are driving the growth of the Medical Weight Loss Clinics Market (U.S.) market?
What are some challenges faced by the Medical Weight Loss Clinics Market (U.S.) market?
Who are the major players in the Medical Weight Loss Clinics Market (U.S.) market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Ownership
- 1.2.1 Hospital-based
- 1.2.2 Standalone
- 1.3 By Service Type
- 1.3.1 Prescription-based Programs
- 1.3.2 Behavioral Counseling & Lifestyle Modification
- 1.3.3 Nutritional Guidance
- 1.3.4 Telehealth/Virtual Care
- 1.4 By Patient Demographics
- 1.4.1 Adults (18-64)
- 1.4.2 Seniors (65+)
- 1.4.3 Adolescents/Teens
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,220 million → 2032: USD 1,672 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global U.S. Medical Weight Loss Clinics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global U.S. Medical Weight Loss Clinics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global U.S. Medical Weight Loss Clinics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global U.S. Medical Weight Loss Clinics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global U.S. Medical Weight Loss Clinics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global U.S. Medical Weight Loss Clinics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global U.S. Medical Weight Loss Clinics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global U.S. Medical Weight Loss Clinics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,220 million → 2032: USD 1,672 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global U.S. Medical Weight Loss Clinics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Ownership - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospital-based
- 12.3.7.2 Standalone
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Prescription-based Programs
- 12.4.7.2 Behavioral Counseling & Lifestyle Modification
- 12.4.7.3 Nutritional Guidance
- 12.4.7.4 Telehealth/Virtual Care
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Patient Demographics - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Adults (18-64)
- 12.5.7.2 Seniors (65+)
- 12.5.7.3 Adolescents/Teens
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global U.S. Medical Weight Loss Clinics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global U.S. Medical Weight Loss Clinics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global U.S. Medical Weight Loss Clinics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Cleveland Clinic
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 NYU Langone Hospitals
- 17.4 Stanford Health Care
- 17.5 UCLA Health
- 17.6 Cedars-Sinai
- 17.7 Medi-Weightloss
- 17.8 Medical Weight Loss Clinic
- 17.9 Options Medical Weight Loss
- 17.10 Rivas Weight Loss
- 17.11 Long Island Weight Loss Institute
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

