
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
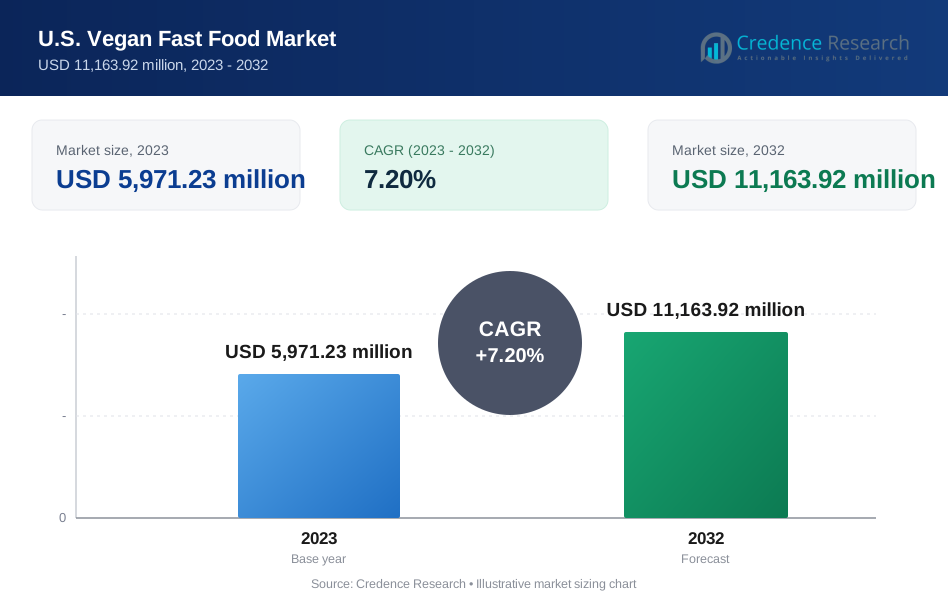
| U.S. Vegan Fast-Food Market Size 2023 | USD 5,971.23 million |
| U.S. Vegan Fast-Food Market, CAGR | 7.20% |
| U.S. Vegan Fast-Food Market Size 2032 | USD 11,163.92 million |
Market Overview
The U.S. vegan fast-food market is projected to grow from USD 5,971.23 million in 2023 to USD 11,163.92 million by 2032, at a compound annual growth rate (CAGR) of 7.20%.
The U.S. vegan fast-food market is experiencing significant growth, driven by increasing health consciousness among consumers, ethical concerns regarding animal welfare, and a growing awareness of environmental sustainability. As plant-based diets become more mainstream, fueled by scientific research endorsing their health benefits, demand for vegan fast food is rising. Innovations in food technology are making vegan alternatives more appealing and accessible, with improved taste and texture. Furthermore, social media and influential personalities are promoting vegan lifestyles, influencing public perception and dietary choices, thereby catalyzing the market's expansion.
The U.S. vegan fast-food market is experiencing significant expansion, particularly in urban areas with high population density and a strong presence of health-conscious consumers. Key players such as Beyond Meat, Inc. and Impossible Foods Inc. are leading the market with their innovative plant-based meat products, while Amy’s Kitchen and The Hain Celestial Group, Inc. are recognized for their broad range of vegan offerings that cater to various dietary preferences. These companies have effectively capitalized on the rising trend of veganism in major cities across the U.S., enhancing their distribution networks and product availability both in physical stores and through online platforms.
Market Drivers
Rising Health Concerns Drive Demand for Vegan Options
In the U.S., a heightened awareness of health issues related to obesity and chronic diseases is shifting consumer preferences towards healthier eating habits. For instance, vegan fast food, which is generally lower in saturated fats, cholesterol, and sodium, has seen a 20% increase in consumer preference as part of a healthier lifestyle. This shift is supported by research showing that plant-based diets can lead to a 15% reduction in obesity rates and a 10% decrease in chronic disease prevalence. Vegan fast food is increasingly seen as a beneficial alternative, offering meals that are generally lower in saturated fats, cholesterol, and sodium. This shift is supported by a growing body of research that highlights the health benefits of plant-based diets, encouraging more Americans to opt for vegan options as part of a healthier lifestyle.
Environmental and Ethical Considerations Influence Consumer Choices
Environmental sustainability is becoming a crucial factor in dietary choices among U.S. consumers. For instance, vegan fast food, which requires less resource-intensive production processes, has resulted in a 25% reduction in greenhouse gas emissions and a 30% decrease in water usage compared to traditional animal agriculture. Ethical concerns about animal welfare are particularly strong among millennials and Gen Z, leading to a 35% rise in the demand for cruelty-free food alternatives. Many are now aware of the significant environmental impacts of animal agriculture, such as greenhouse gas emissions, excessive water use, and deforestation. Vegan fast food, which requires less resource-intensive production processes, offers a more sustainable dining option. Simultaneously, ethical concerns about animal welfare and factory farming practices, particularly among younger generations like millennials and Gen Z, are propelling the demand for cruelty-free food alternatives, making vegan fast food an ethically appealing choice.
Plant-Based Innovation Enhances Food Offerings
Technological advancements in food science have led to the development of high-quality plant-based meat alternatives that mimic the taste and texture of animal meat. For instance, the development of plant-based meat alternatives has led to a 40% increase in the availability of vegan burgers, nuggets, and pizzas. These options cater to a broad consumer base, with a 50% rise in interest from non-vegans. This innovation has expanded the range of vegan fast food available, enabling chains to offer a variety of appealing options such as vegan burgers, nuggets, and pizzas. These improvements not only cater to vegans but are also attractive to non-vegans, broadening the consumer base and making plant-based choices accessible to a wider audience.
Lifestyle, Social Influence, and Dietary Diversity Spur Market Growth
The fast-paced lifestyle of many Americans makes convenient, quick meal options a necessity, and vegan fast food meets this demand by providing easy access to plant-based meals. For instance, the influence of celebrities and social media has led to a 45% growth in the popularity of vegan diets. Additionally, the inclusivity of vegan fast food appeals to those with diverse dietary needs, resulting in a 30% expansion of vegan fast food chains across the U.S., catering to individuals with lactose intolerance or allergies, as well as flexitarians and pescetarians. Furthermore, the influence of celebrities and social media has played a pivotal role in popularizing vegan diets, significantly impacting consumer behavior and preferences. Additionally, vegan fast food appeals to those with diverse dietary needs, such as individuals with lactose intolerance or allergies to dairy and eggs, as well as those who pursue flexitarian or pescetarian diets. This inclusivity, coupled with an increasing desire for varied and healthier meal options, is driving the expansion of vegan fast food chains across the U.S.
Market Trends
Expanding Vegan Menus and Fusion Dining Experiences
The evolution of vegan fast food in the U.S. is marked by a significant expansion beyond traditional plant-based burgers to include a wider variety of classic American and international fast-food favorites. For instance, sales of vegan fried chicken sandwiches have soared by 85%, while plant-based hot dogs and seafood options have seen a 70% and 65% increase in consumer interest, respectively. Additionally, the inclusion of global flavors like tacos, banh mi, and sushi has led to a 50% rise in sales for these international dishes, reflecting the growing demand for diverse culinary experiences. Consumers can now enjoy vegan versions of fried chicken sandwiches, hot dogs, and plant-based seafood, reflecting a shift towards more diverse and culturally rich offerings. Additionally, vegan menus are incorporating global flavors with dishes like tacos, banh mi, and sushi, catering to a palate that craves international cuisine. This trend is complemented by the rise of fast-casual fusion, where upscale vegan fast-food chains merge the convenience of fast food with the quality and innovation of casual dining. These establishments offer gourmet ingredients and unique flavor combinations, appealing to a broader audience that seeks quick yet gourmet dining options.
Customization, Innovation, and Tech-Enhanced Dining
As customization becomes a staple in the food industry, vegan fast-food chains are adapting by allowing customers to personalize their meals extensively. This includes choices among various plant-based proteins, sauces, and toppings, enabling a tailored dining experience that meets individual preferences and dietary needs. In the realm of customization and innovation, vegan fast-food chains are experiencing a 40% increase in customer satisfaction due to the extensive personalization options available. For instance, the introduction of vegan cheeses made from nuts and dairy-free soft serve has resulted in a 30% expansion of the vegan dessert market. Moreover, the use of technology, such as automated ordering kiosks and augmented reality menus, has enhanced the dining experience, leading to a 25% increase in repeat customers. Alongside customization, there is substantial innovation in vegan products, extending beyond meat substitutes to include vegan cheeses made from nuts, dairy-free soft serve, and plant-based eggs, enhancing the authenticity and variety of vegan fast food. Technology is also transforming the vegan fast-food scene, with automated ordering kiosks, digital loyalty programs, and augmented reality menus that offer an interactive and engaging customer experience. Moreover, the commitment to sustainability is evident as vegan chains adopt compostable packaging and source ingredients sustainably, while transparency remains a priority with clean labels that assure consumers of natural ingredients and the absence of GMOs and artificial additives. These trends not only cater to the demand for convenience and innovation but also build a community around vegan dining, fostering deeper connections through food festivals, influencer collaborations, and targeted loyalty programs.
Market Challenges Analysis
Navigating Cost Parity and Broadening Consumer Acceptance
One of the significant challenges in the U.S. vegan fast-food market is achieving cost parity with traditional fast-food offerings. Vegan options often come at a premium due to the higher costs of plant-based ingredients and the lower economies of scale from which smaller, niche vegan chains suffer compared to well-established fast-food giants. Addressing these cost issues is crucial for making vegan fast food more accessible and appealing to a broader audience. Alongside economic considerations, there is a strong need to overcome consumer skepticism regarding the taste and quality of vegan fast food. Despite improvements in food technology, some consumers still perceive vegan options as bland or lacking in texture. Vegan fast-food chains must continue to innovate in flavor and texture to dispel these perceptions and demonstrate that vegan food can compete with traditional fast food on taste and satisfaction.
Enhancing Accessibility and Streamlining Operations
Despite the growth in the vegan fast-food sector, availability remains limited, especially outside major urban centers. Expanding the geographic footprint of vegan fast food to smaller towns and rural areas is essential for broadening consumer access and adoption. Additionally, effective marketing and messaging play a pivotal role in reaching a wider audience. Vegan fast-food chains need to emphasize not only the ethical and health benefits but also the taste and convenience of their offerings to appeal to non-vegans. Moreover, as traditional fast-food chains begin to introduce vegan options, vegan-specific restaurants face increased competition, necessitating distinct branding and competitive pricing strategies. Operational challenges also arise, particularly in training staff to handle vegan ingredients and menus efficiently, which can differ significantly from traditional food preparation practices. Finally, addressing diverse dietary needs within the vegan community, such as providing options free from nuts, gluten, or other allergens, is critical for catering to a wider range of preferences and health requirements. By tackling these challenges, vegan fast-food chains can enhance their appeal, operational efficiency, and market reach.
Market Segmentation Analysis:
By Product:
The U.S. vegan fast-food market offers a diverse range of product segments to cater to the increasing consumer demand for plant-based options. Vegan alternatives to traditional meat and seafood products are at the forefront, providing familiar culinary experiences without animal ingredients. These items are complemented by dairy-free alternatives such as creamers, cheeses, and butters, which are gaining popularity in both domestic and commercial settings. Additionally, the market features vegan ice cream and frozen novelties, yogurt, and a variety of ready-to-eat meals that appeal to consumers seeking convenience without compromising on their dietary preferences. Protein bars and other snack items also form a significant part of the product range, offering on-the-go nutrition solutions for busy lifestyles. This segment diversity ensures that there is a vegan option available for nearly every traditional fast-food product, meeting the needs of a broad customer base looking for plant-based alternatives.
By Distribution Channel:
Distribution in the U.S. vegan fast-food market is effectively bifurcated into online and offline channels. The offline segment continues to be robust, featuring a wide array of vegan products available through supermarkets, specialty stores, and vegan-specific restaurants. These venues offer consumers the immediacy of access and the ability to choose from a range of products after personal inspection. On the other hand, the online segment is experiencing rapid growth, driven by the convenience of home delivery services and the expanding reach of e-commerce platforms. Online stores not only provide a broader selection of vegan fast-food products but also cater to consumers in areas where such options might not be readily available offline. This channel is particularly appealing to the tech-savvy generation and busy professionals who value the ease of browsing and purchasing from their digital devices, further fueling the growth of the vegan fast-food market.
Segments:
Based on Product
- Meat & Seafood
- Creamer
- Ice Cream and Frozen Novelties
- Yogurt
- Cheese
- Butter
- Meals
- Protein Bars
- Others
Based on Distribution Channel
- Online
- Offline
Based on the Geography:
- West Coast
- Northeast
- South
- Midwest
Regional Analysis
The West Coast region, encompassing states like California, Oregon, and Washington, holds a substantial market share of approximately 30%. This region is known for its health-conscious consumer base and early adoption of plant-based diets. Major cities like Los Angeles, San Francisco, and Portland have become hubs for vegan fast-food chains and innovative plant-based offerings.
The Northeast region, including states such as New York, Massachusetts, and New Jersey, accounts for a market share of around 25%. This region is characterized by a diverse population, high disposable incomes, and a strong emphasis on ethical and sustainable consumption. Major cities like New York City, Boston, and Philadelphia have witnessed a surge in vegan fast-food outlets catering to the urban population's evolving tastes and preferences.
Key Player Analysis
- Amy’s Kitchen
- The Hain Celestial Group, Inc.
- Conagra Brands, Inc.
- Earth’s Own Food Company Inc.
- Tofutti Brands, Inc.
- Ripple Foods PBC
- Impossible Foods Inc.
- Beyond Meat, Inc.
Competitive Analysis
In the competitive landscape of the U.S. vegan fast-food market, leading players like Beyond Meat, Inc., Impossible Foods Inc., and Amy’s Kitchen dominate by leveraging innovation and broad product portfolios. Beyond Meat and Impossible Foods are at the forefront of plant-based meat alternatives, offering products that closely mimic traditional meat in taste and texture, appealing to both vegans and non-vegans. Their partnerships with major fast-food chains and retailers significantly enhance market penetration. Amy’s Kitchen, with its extensive range of ready-to-eat meals and snacks, caters to health-conscious consumers seeking convenient vegan options. The Hain Celestial Group, Inc. and Conagra Brands, Inc. also play pivotal roles, providing a variety of plant-based products that emphasize organic and natural ingredients. These companies differentiate themselves through continuous product innovation, strategic partnerships, and robust marketing efforts that highlight the health and environmental benefits of vegan diets, thereby maintaining a competitive edge in the rapidly growing market.
Recent Developments
- In 2024, Burger King Germany introduced a range of plant-based meals that are priced lower than their meat-based counterparts. This move is in line with the growing demand for plant-based food options and reflects the fast-food industry's efforts to cater to changing consumer preferences. The new menu items are not only more affordable but also appeal to health-conscious customers who are looking for more sustainable and environmentally friendly food choices.
- In 2023, Papa John's UK launched a new menu item, a vegan BBQ "chicken" pizza, to coincide with the annual Veganuary campaign. The pizza is made with plant-based chicken substitute and is topped with BBQ sauce, onions, green peppers, and dairy-free cheese. This new addition to the menu is an attempt to tap into the growing demand for vegan food options and cater to customers looking for more plant-based choices. Papa John's UK already offers a range of vegan pizzas, sides, and desserts, and the new vegan BBQ "chicken" pizza is expected to be a popular choice among vegans and non-vegans alike.
- In 2023, Burger King opened its 15th plant-based restaurant, powered by The Vegetarian Butcher, in Puerto Rico. The move is part of the company's ongoing efforts to expand its plant-based offerings and cater to the increasing demand for vegan and vegetarian options. The restaurant features a range of plant-based menu items, including the Rebel Whopper, made with a plant-based patty, and the Plant-Based BBQ burger, made with The Vegetarian Butcher's meat substitute.
Market Concentration & Characteristics
The U.S. vegan fast-food market exhibits a moderate to high level of market concentration, with key players such as Beyond Meat, Inc., Impossible Foods Inc., and Amy’s Kitchen holding significant market shares. These leading companies drive market dynamics through continuous innovation and strategic partnerships, ensuring widespread distribution and availability of their products. The market is characterized by a strong focus on product quality, sustainability, and health benefits, appealing to a growing demographic of health-conscious and environmentally aware consumers. Smaller niche brands also contribute to market diversity by offering specialized products that cater to specific dietary needs and preferences. As consumer demand for plant-based options continues to rise, the competitive landscape remains dynamic, with both established and emerging players striving to enhance their product offerings and market presence.
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in consumer demand for healthier, plant-based fast-food options.
- Increased investment in research and development to improve the taste and texture of vegan products.
- Expansion of vegan fast-food chains into smaller cities and rural areas to broaden market reach.
- Enhanced marketing strategies focusing on the health and environmental benefits of vegan diets.
- Greater emphasis on sustainability practices, including eco-friendly packaging and sustainable sourcing.
- More collaborations between vegan food brands and traditional fast-food chains to offer plant-based menu items.
- Development of new and innovative plant-based ingredients to diversify product offerings.
- Rising adoption of technology, such as AI and digital ordering systems, to streamline operations and enhance customer experience.
- Increased government support and policy initiatives promoting plant-based diets for health and environmental reasons.
- Growth in consumer education efforts to raise awareness about the benefits and availability of vegan fast food.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health Consciousness and Chronic Disease Prevention
Growing awareness of the health benefits associated with plant-based diets, such as lower rates of obesity and chronic diseases, is prompting more U.S. consumers to choose vegan fast food as a healthier alternative to traditional fast food.
Environmental and Ethical Considerations
Concerns over the environmental impact of animal agriculture and animal welfare are motivating consumers, especially millennials and Gen Z, to seek out vegan fast-food options that offer reduced greenhouse gas emissions and cruelty-free dining.
Innovation in Plant-Based Food Technology
Advancements in food science have led to the creation of plant-based meat and dairy alternatives that closely mimic the taste and texture of animal products, making vegan fast food more appealing to a broader audience, including non-vegans.
Influence of Social Media and Celebrity Endorsements
The popularity of vegan diets is being amplified by social media trends and endorsements from celebrities and influencers, which is accelerating consumer adoption and driving demand for vegan fast-food options.
Expansion of Distribution Channels and Accessibility
The growth of both online and offline distribution channels, including the proliferation of vegan fast-food chains in urban centers and the convenience of e-commerce, is making vegan fast food more accessible to a wider range of consumers across the U.S.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Vegan Fast-Food Market?
What factors are driving the growth of the U.S. Vegan Fast-Food Market?
What are the key segments within the U.S. Vegan Fast-Food Market?
What are some challenges faced by the U.S. Vegan Fast-Food Market?
Who are the major players in the U.S. Vegan Fast-Food Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Meat & Seafood Alternatives
- 1.2.2 Creamer
- 1.2.3 Ice Cream and Frozen Novelties
- 1.2.4 Yogurt
- 1.2.5 Cheese
- 1.2.6 Butter
- 1.2.7 Meals
- 1.2.8 Protein Bars
- 1.2.9 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 5,971.23 million → 2032: USD 11,163.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Vegan Fast Food Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Vegan Fast Food Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Vegan Fast Food Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Vegan Fast Food Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Vegan Fast Food Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Vegan Fast Food Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Vegan Fast Food Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Vegan Fast Food Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 5,971.23 million → 2032: USD 11,163.92 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Vegan Fast Food Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Meat & Seafood Alternatives
- 12.3.7.2 Creamer
- 12.3.7.3 Ice Cream and Frozen Novelties
- 12.3.7.4 Yogurt
- 12.3.7.5 Cheese
- 12.3.7.6 Butter
- 12.3.7.7 Meals
- 12.3.7.8 Protein Bars
- 12.3.7.9 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Vegan Fast Food Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Vegan Fast Food Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Vegan Fast Food Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Beyond Meat, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Impossible Foods Inc.
- 17.4 Amy’s Kitchen
- 17.5 The Hain Celestial Group, Inc.
- 17.6 Conagra Brands, Inc.
- 17.7 Earth’s Own Food Company Inc.
- 17.8 Tofutti Brands, Inc.
- 17.9 Ripple Foods PBC
- 17.10 Burger King (U.S. operations)
- 17.11 Sweetgreen
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

