
Market Overview
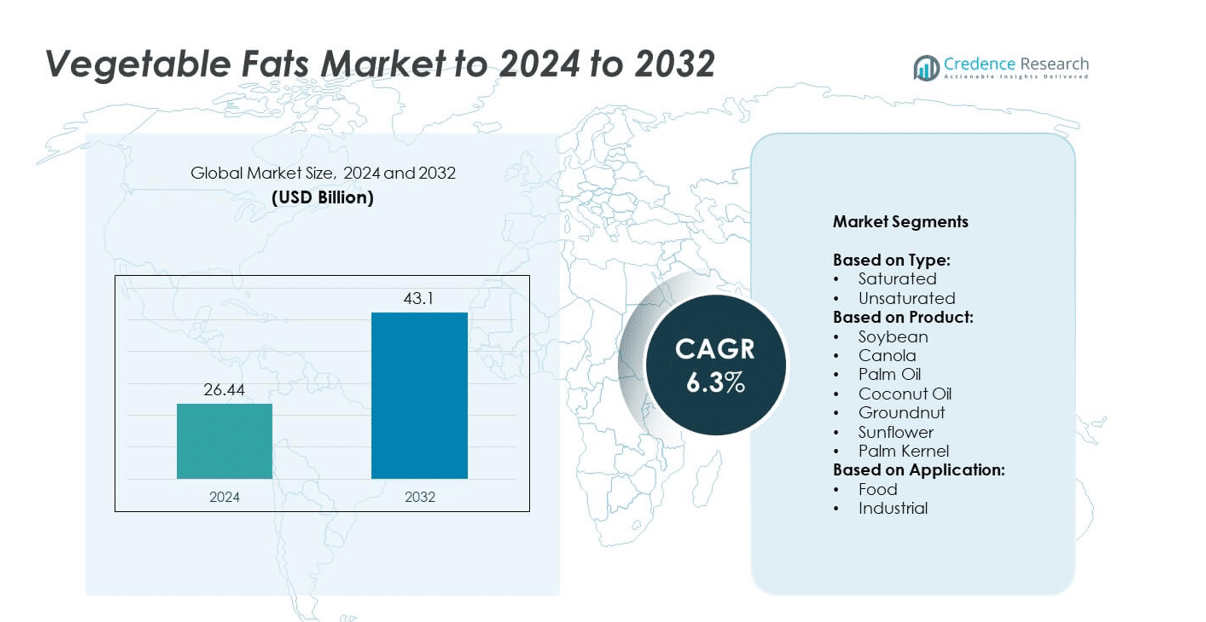
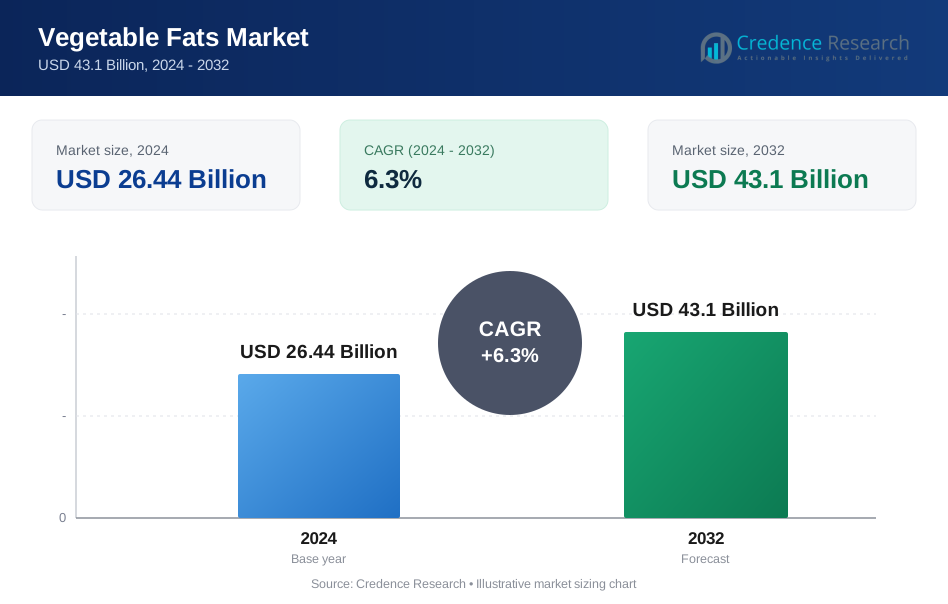
Vegetable Fats Market size was valued at USD 26.44 Billion in 2024 and is anticipated to reach USD 43.1 Billion by 2032, at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Vegetable Fats Market Size 2024 | USD 26.44 Billion |
| Vegetable Fats Market, CAGR | 6.3% |
| Vegetable Fats Market Size 2032 | USD 43.1 Billion |
The vegetable fats market is shaped by leading players such as Mars, Incorporated, Cargill, Unilever, Bunge Ltd., Wilmar International, Nestlé, IOI Corporation Berhad, Archer Daniels Midland Company, AAK AB, and Mondelez International, Inc. These companies focus on expanding production capacities, developing trans-fat-free solutions, and adopting sustainable sourcing practices to meet rising global demand. Strategic collaborations and investments in R&D help them strengthen their presence in food, confectionery, and biodiesel sectors. Asia Pacific emerged as the leading region, accounting for over 35% of the market share in 2024, supported by large-scale palm oil production, high consumption of processed foods, and expanding biofuel mandates in countries like Indonesia and India.
Market Insights
- The vegetable fats market was valued at USD 26.44 Billion in 2024 and is projected to reach USD 43.1 Billion by 2032, growing at a CAGR of 6.3%.
- Rising demand for processed foods, plant-based alternatives, and biofuel production is fueling market growth globally.
- Trends include increasing adoption of sustainable and certified palm oil, and innovation in trans-fat-free and low-saturated-fat formulations.
- The market is moderately consolidated, with key players focusing on capacity expansion, strategic partnerships, and R&D investments to strengthen their competitive position.
- Asia Pacific held the largest share with over 35% in 2024, followed by North America at 28% and Europe at 26%, while palm oil led the product segment with more than 40% share.
Market Segmentation Analysis:
By Type
Saturated vegetable fats dominated the market in 2024, accounting for over 55% share. Their dominance is driven by extensive use in bakery, confectionery, and processed foods for their stability and longer shelf life. Palm oil is a major contributor due to its wide availability and cost-effectiveness, supporting mass production of packaged foods. Rising demand in developing countries, where affordability and high caloric value are key, is strengthening growth. Industrial applications like cosmetics and soaps also rely heavily on saturated fats, adding to their share in the market.
- For instance, Perfat Technologies developed a fiber-reinforced gelled vegetable oil that achieves an approximately 80% reduction in saturated fat content compared to traditional solid fats like palm oil or butter.
By Product
Palm oil led the product segment in 2024, holding more than 40% market share. Its versatility in food processing, cooking, and packaged goods manufacturing makes it the most widely used vegetable fat. High yield per hectare and year-round harvesting drive its large-scale production and competitive pricing. Demand from Asia-Pacific, particularly Indonesia and Malaysia, continues to fuel its global share. Palm oil’s role in biodiesel production also adds momentum, as governments push for renewable energy adoption. However, sustainability certifications and deforestation concerns are shaping responsible sourcing strategies among producers.
- For instance, According to a WWF Palm Oil Scorecard case study, LG H&H aims to increase its ratio of RSPO-certified sustainable palm oil purchases from 61.5% in 2022 to 70% by 2025.
By Application
The food segment was the leading application area, accounting for over 70% share in 2024. Vegetable fats are key ingredients in bakery, confectionery, dairy alternatives, and frying oils. Growing demand for processed and convenience foods in emerging economies is driving market growth. Rising vegan and plant-based trends are also boosting adoption of vegetable fats as alternatives to animal fats. The segment benefits from continuous innovations in texture modification and trans-fat-free formulations, meeting health-conscious consumer preferences. Food manufacturers increasingly invest in functional fat blends to improve taste, shelf life, and stability.
Key Growth Drivers
Rising Demand for Processed Foods
Growing consumption of processed and convenience foods is a major driver for vegetable fats. They are used in bakery, confectionery, frying oils, and ready-to-eat meals due to their functional properties. Rising urbanization and changing lifestyles are boosting demand for affordable, stable fat sources. Emerging economies, particularly in Asia-Pacific, are witnessing rapid expansion in foodservice and packaged goods sectors. This trend ensures sustained growth for vegetable fats, especially palm oil and soybean-based products. The increasing adoption of trans-fat-free formulations further supports market expansion across multiple food categories.
- For instance, in Malaysia, the MSPO (Malaysian Sustainable Palm Oil) certification covered over 5.03 million hectares of oil palm plantations as of mid-2025, an increase from previous years.
Expansion of Plant-Based and Vegan Diets
The growing popularity of plant-based diets is significantly fueling vegetable fat demand. Consumers seek alternatives to animal fats for health, sustainability, and ethical reasons. Vegetable fats are preferred for dairy-free spreads, chocolates, and meat alternatives, providing desirable texture and taste. Food manufacturers are investing in R&D to create innovative fat blends that mimic traditional dairy and animal fats. Rising awareness about cholesterol management and heart health is also supporting adoption. This shift toward plant-derived fats is expected to sustain growth throughout the forecast period.
- For instance, Bunge completed the commissioning of a new multi-oil refinery in Kandla, Gujarat, in early 2013, with a capacity of 1,200 tonnes per day.
Government Support and Biodiesel Demand
Government policies encouraging renewable energy production are boosting vegetable fat consumption in biodiesel. Palm oil, soybean oil, and canola oil are key raw materials for biofuel production. Mandates for blending biofuels with conventional diesel in Europe, the U.S., and Asia drive additional demand. This reduces reliance on fossil fuels while supporting agricultural sectors. The dual application of vegetable fats in food and fuel markets ensures a steady revenue stream. Rising focus on energy security and reducing greenhouse gas emissions continues to promote biofuel adoption globally.
Key Trends & Opportunities
Shift Toward Sustainable and Certified Sourcing
Sustainability has become a major focus in the vegetable fats market. Producers are investing in certified sustainable palm oil (CSPO) and deforestation-free supply chains. Consumer awareness about environmental impact is encouraging food brands to adopt ethical sourcing practices. Certification programs such as RSPO are gaining traction among manufacturers. This creates opportunities for suppliers who prioritize traceability and eco-friendly production. Companies emphasizing green and transparent sourcing are expected to gain a competitive advantage and improve brand loyalty, especially in developed markets.
- For instance, Wilmar, alongside major suppliers like Apical, KPN, and Musim Mas, is a key contributor to Indonesia's national biodiesel supply. For 2024, the government allocated 13.4 million kiloliters to support its B35 mandate, a figure that was finalized in December 2023.
Innovation in Fat Blends and Functional Products
Manufacturers are focusing on developing functional fat blends that enhance food quality and health benefits. Non-hydrogenated, trans-fat-free, and low-saturated-fat products are in demand due to health-conscious consumers. New formulations provide improved texture, stability, and nutritional profiles for bakery and confectionery applications. Innovations in enzymatic interesterification and fractionation technologies are enabling tailored fat solutions. These developments allow manufacturers to cater to specific dietary needs and clean-label requirements. Functional fats are becoming key differentiators for premium food brands seeking to attract health-aware buyers.
- For instance, Gemini Edibles & Fats India Limited (GEF India) is building a new edible oils refinery in Telangana with 700 tonnes per day capacity.
Key Challenges
Price Volatility of Raw Materials
Fluctuating prices of vegetable oil crops pose a significant challenge to market stability. Weather disruptions, geopolitical tensions, and changes in trade policies impact supply and cost. This directly affects the margins of manufacturers relying on palm oil, soybean oil, and sunflower oil. Price spikes often lead to reformulations or substitution with cheaper alternatives, affecting product quality. The market remains vulnerable to agricultural yield variations, making long-term cost planning difficult for producers. Managing procurement risks and securing stable supply chains is crucial for industry players.
Environmental and Sustainability Concerns
Deforestation linked to palm oil plantations has drawn global criticism, affecting market reputation. Pressure from governments, NGOs, and consumers is forcing companies to adopt strict sustainability measures. Non-compliance can lead to brand boycotts and regulatory penalties. Transitioning to certified sustainable production increases costs for suppliers, impacting profitability. Balancing affordability and sustainability remains challenging, especially in price-sensitive markets. Companies that fail to address these concerns risk losing market share to competitors with stronger environmental commitments and transparent sourcing practices.
Regional Analysis
North America
North America held around 28% share of the vegetable fats market in 2024, driven by high demand for processed foods and bakery products. The U.S. dominates consumption, supported by a strong packaged food industry and growing adoption of plant-based alternatives. Rising health awareness is boosting demand for trans-fat-free and non-hydrogenated oils. The biodiesel sector also contributes significantly to consumption, particularly soybean oil-based biodiesel. Canada follows with steady growth due to rising preference for healthier cooking oils and vegan diets. Technological advancements in fat modification processes further support product innovation and growth in the region.
Europe
Europe accounted for approximately 26% of the vegetable fats market in 2024, supported by mature food processing industries and stringent regulations on trans fats. Germany, France, and the U.K. lead demand, particularly for palm oil substitutes and sustainable fat options. The region shows high adoption of certified sustainable palm oil due to strong environmental regulations. Growth in the confectionery and bakery sector continues to fuel consumption of cocoa butter equivalents and specialty fats. Expansion of biodiesel production, particularly in Germany, also drives vegetable oil utilization. Clean-label and organic trends remain strong, boosting demand for high-quality fat sources.
Asia Pacific
Asia Pacific dominated the market with over 35% share in 2024, making it the largest regional segment. China, India, and Indonesia are key consumers due to rising population and rapid urbanization. High production and export of palm oil from Malaysia and Indonesia strengthen regional dominance. Growing demand for affordable cooking oils and processed foods supports market growth. Expanding biofuel mandates in countries like Indonesia further drive palm oil consumption. Local manufacturers focus on cost-effective production and export opportunities, while multinational players invest in capacity expansion to meet surging domestic and international demand.
Latin America
Latin America captured nearly 7% of the vegetable fats market in 2024, with Brazil and Argentina leading regional consumption and production. The region benefits from large-scale soybean cultivation, which supports both domestic use and exports. Growing food processing industries and rising fast-food culture are driving demand for vegetable oils in cooking and frying applications. Expanding biodiesel production in Brazil adds additional consumption for soybean oil. Economic growth and increasing middle-class population are expected to support steady demand. However, price volatility and export dependency pose challenges to long-term market stability in the region.
Middle East & Africa
Middle East & Africa held about 4% share of the vegetable fats market in 2024, driven by rising demand for affordable edible oils and growing urban population. Gulf countries are key importers, relying heavily on palm oil and sunflower oil for food applications. South Africa leads consumption within Africa, supported by expanding food manufacturing capabilities. Increasing adoption of vegetable oils in confectionery and bakery sectors is fueling growth. Government efforts to improve food security and processing capacity are boosting regional imports and distribution networks. Limited domestic production makes the region reliant on global supply chains.
Market Segmentations:
By Type:
- Saturated
- Unsaturated
By Product:
- Soybean
- Canola
- Palm Oil
- Coconut Oil
- Groundnut
- Sunflower
- Palm Kernel
By Application:
- Food
- Industrial
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the vegetable fats market features leading players such as Mars, Incorporated, IOI Corporation Berhad, Unilever, Cargill, Incorporated, Nestlé, Olam International Ltd., Bunge Ltd., Wilmar International Ltd, Loders Croklaan, The Kraft Heinz Company, Nisshin Oillio Group, Ltd., KTC, AAK AB, Archer Daniels Midland Company, Mondelez International, Inc., and Fuji Oil Holdings, Inc. The market is moderately consolidated, with major participants focusing on expanding production capacities and strengthening global supply chains to meet rising demand. Companies invest heavily in research and development to develop trans-fat-free and specialty fat blends for bakery, confectionery, and processed food applications. Strategic collaborations, acquisitions, and sustainability initiatives are key competitive strategies to secure long-term growth. Players are also emphasizing traceability and certified sustainable sourcing to meet consumer expectations and regulatory requirements. Continuous innovation in fat modification technologies and growing focus on health-oriented products help companies maintain a competitive edge.
Key Player Analysis
- Mars, Incorporated
- IOI Corporation Berhad
- Unilever
- Cargill, Incorporated
- Nestlé
- Olam International Ltd.
- Bunge Ltd.
- Wilmar International Ltd
- Loders Croklaan
- The Kraft Heinz Company
- Nisshin Oillio Group, Ltd.
- KTC
- AAK AB
- Archer Daniels Midland Company
- Mondelez International, Inc.
- Fuji Oil Holdings, Inc
Recent Developments
- In 2024, Cargill became the first global edible oils supplier to achieve the World Health Organization (WHO) best-practice standard for eliminating industrially produced trans-fatty acids (iTFA) across its entire edible oils portfolio.
- In 2023, KTC, a U.K.-based oil manufacturer, launched a new line of palm oil products in the U.K. market.
- In 2022, Adani Wilmar Limited (AWL), Wilmar expanded its distribution network in India, reaching over 113 million households and strengthening its edible oils business.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The vegetable fats market is expected to grow steadily, supported by rising processed food consumption.
- Demand for plant-based and vegan alternatives will continue to boost vegetable fat usage.
- Technological advances in fat modification will improve product quality and functionality.
- Sustainable and certified sourcing practices will become a key focus for manufacturers.
- Palm oil will remain the leading product, but alternatives will gain traction due to sustainability concerns.
- Biodiesel production will create additional demand for soybean and canola oils.
- Health-conscious consumers will drive growth of trans-fat-free and low-saturated-fat products.
- Asia Pacific will maintain its position as the largest and fastest-growing regional market.
- Strategic partnerships and capacity expansions will enhance global supply chain stability.
- Innovation in functional fat blends will create new opportunities for premium food and bakery products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Vegetable Fats Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Vegetable Fats Market projected to grow between 2025 and 2032?
Which Vegetable Fats Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Vegetable Fats Market?
Which region commanded the largest share of the Vegetable Fats Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vegetable Fats Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vegetable Fats Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 26.44 Billion → 2032: USD 43.1 Billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vegetable Fats Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vegetable Fats Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vegetable Fats Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vegetable Fats Market Drivers
- 3.3 Vegetable Fats Market Restraints & Challenges
- 3.4 Vegetable Fats Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vegetable Fats Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vegetable Fats Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vegetable Fats category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vegetable Fats Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vegetable Fats Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vegetable Fats market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vegetable Fats Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vegetable Fats Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vegetable Fats Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vegetable Fats (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vegetable Fats Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vegetable Fats Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vegetable Fats Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vegetable Fats Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vegetable Fats Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vegetable Fats Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vegetable Fats Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vegetable Fats Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vegetable Fats Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
