
Market Overview:
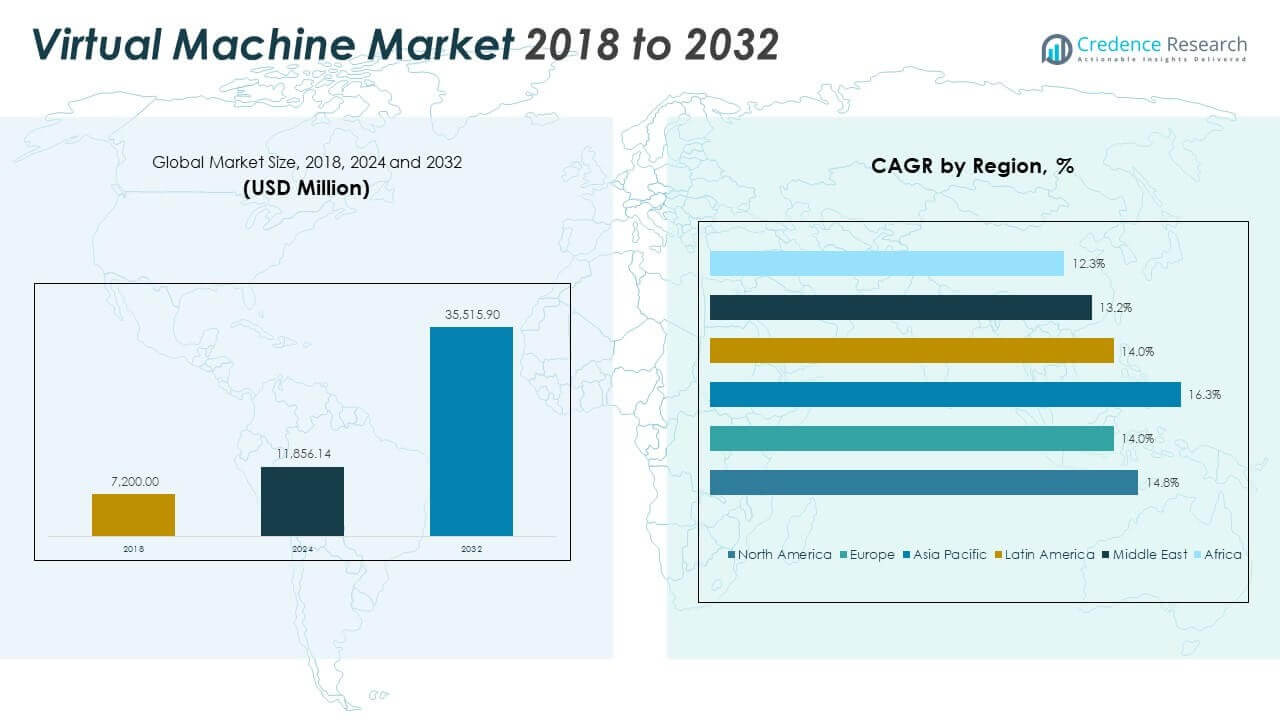
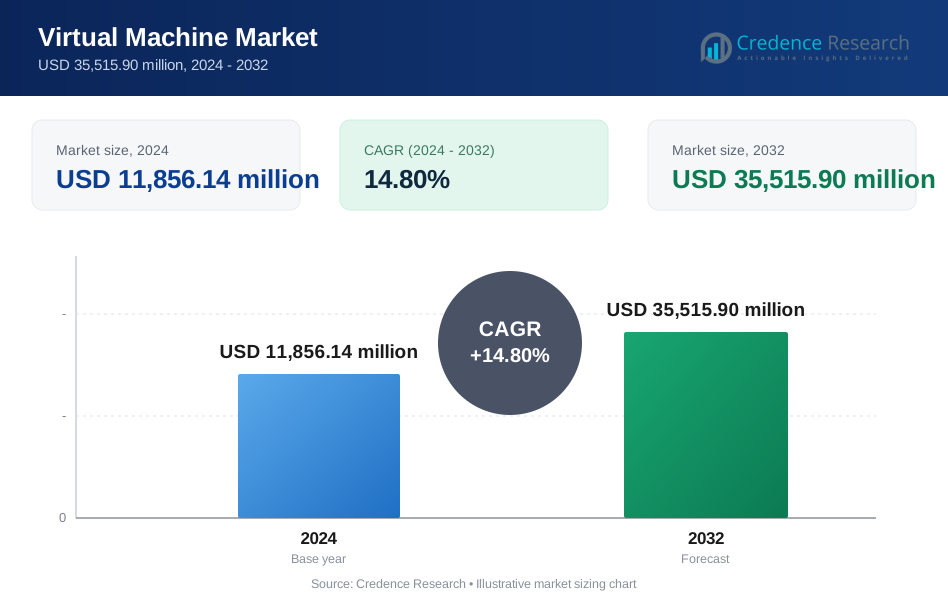
The Virtual Machine Market size was valued at USD 7,200.00 million in 2018 to USD 11,856.14 million in 2024 and is anticipated to reach USD 35,515.90 million by 2032, at a CAGR of 14.80% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Virtual Machine Market Size 2024 | USD 11,856.14 Million |
| Virtual Machine Market, CAGR | 14.80% |
| Virtual Machine Market Size 2032 | USD 35,515.90 Million |
Strong demand for flexible and efficient IT infrastructure drives market growth. Enterprises use virtual machines to reduce hardware dependence and improve resource use. Cloud adoption accelerates usage across public, private, and hybrid environments. Organizations rely on virtual machines for faster application rollout and safer testing. Remote work models increase demand for virtual desktops and secure access. DevOps practices also expand usage across development and testing workflows. Improved workload control supports uptime and service quality. Cost control remains a core decision factor.
North America leads the market due to early cloud adoption and large data center capacity. The United States drives usage across technology, finance, and healthcare sectors. Europe follows with steady adoption supported by digital transformation and data compliance needs. Asia Pacific is emerging fast, led by China, India, and Southeast Asia. Rapid digitalization and cloud investment support regional growth. Latin America, the Middle East, and Africa show gradual expansion through cloud partnerships and IT modernization.
Market Insights:
- The Virtual Machine Market was valued at USD 7,200.00 million in 2018, USD 11,856.14 million in 2024, and is projected to reach USD 35,515.90 million by 2032, growing at a CAGR of 14.80%.
- In 2024, North America held the largest market share at 37.5%, followed by Europe at 24.4% and Asia Pacific at 24.3%, driven by early cloud adoption, enterprise IT spending, and regulatory readiness.
- Asia Pacific is the fastest-growing region with a 16.3% CAGR, supported by strong cloud migration in China, India, and Southeast Asia.
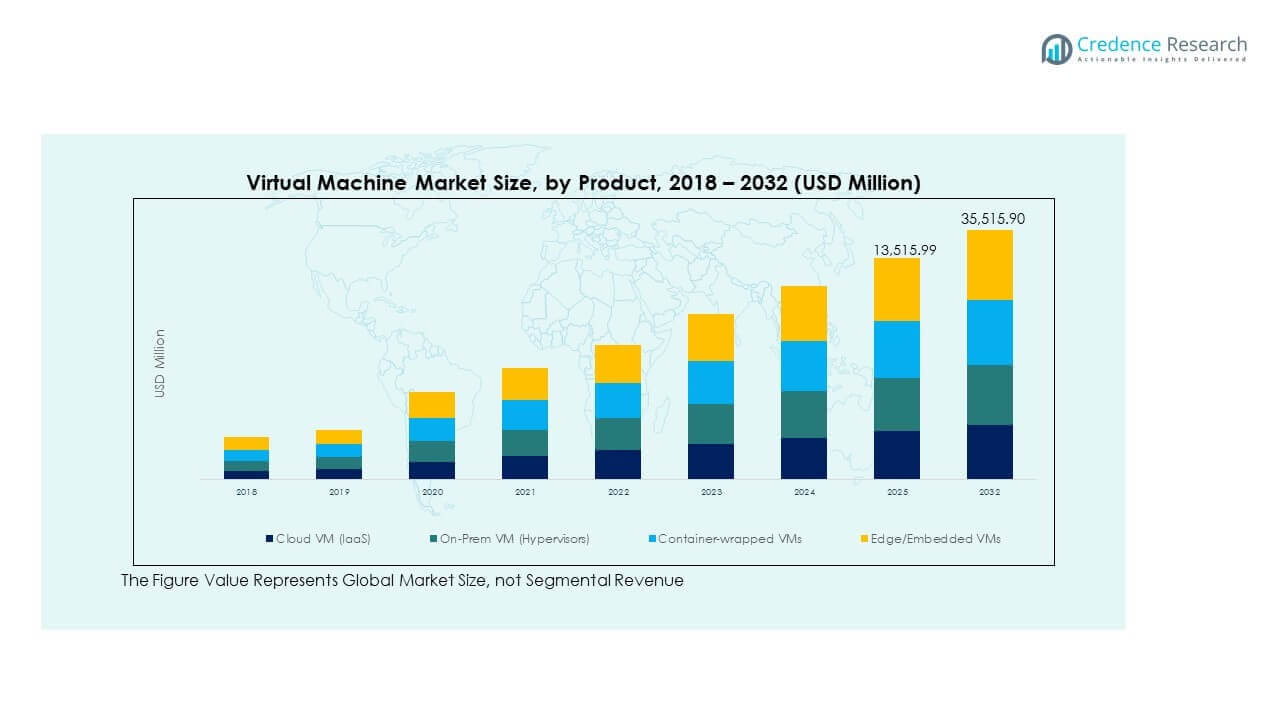
- Cloud VM (IaaS) accounted for the largest product share in 2024, representing approximately 30–32% of the total market due to its scalability and enterprise adoption.
- On-Prem VM (Hypervisors) and Container-wrapped VMs followed, with combined shares of over 40%, supported by hybrid infrastructure needs and DevOps environments.
Market Drivers
Increasing Need for Efficient Resource Utilization Across Diverse IT Environments
Businesses seek to reduce hardware costs and improve server efficiency by adopting virtual machines. Running multiple operating systems on a single machine enables better utilization of computing power. This efficiency supports lean IT operations and reduces total cost of ownership. The Virtual Machine Market gains from enterprises aiming to reduce physical server count and optimize rack space. It supports simplified data center management and centralized control. Organizations value resource pooling and dynamic allocation for variable workloads. This enhances agility and uptime for mission-critical services. Cost efficiency and operational flexibility are top purchase drivers.
- For instance, Dell’s PowerEdge R720 server running VMware vSphere 5 has been used in enterprise environments to consolidate multiple Exchange workloads, reducing hardware footprint and improving power efficiency, with reported deployments supporting thousands of users per host.
Rapid Expansion of Cloud Services and Scalable Computing Infrastructure
Public and private cloud services rely heavily on virtual machines to deliver scalable infrastructure. Cloud service providers use VMs to isolate client workloads and improve service uptime. The shift to multi-cloud and hybrid deployments reinforces the need for consistent VM provisioning. Cloud-based VMs simplify workload migration and global service delivery. The Virtual Machine Market benefits from cloud-native applications and container orchestration tools. Demand rises as enterprises digitize backend systems and launch remote platforms. VM scalability aligns well with unpredictable user traffic and compute-intensive tasks. It supports both horizontal and vertical scaling strategies in cloud architectures.
Growing Demand for DevOps, CI/CD, and Testing Environments in Software Development
Software developers depend on virtual machines to create repeatable, isolated environments for testing and deployment. VMs help simulate different operating systems and configurations during software builds. The ability to create snapshots, rollbacks, and cloned environments improves debugging accuracy. The Virtual Machine Market grows with increasing use of CI/CD pipelines in agile workflows. It enables automation and speed in software release cycles. VMs offer flexibility across development, staging, and production environments. DevOps teams leverage virtual machines to improve deployment reliability. It also supports application sandboxing and pre-release compatibility testing.
- For instance, VMware vSphere snapshots are commonly used in CI/CD pipelines to enable fast rollback during test cycles. In benchmark tests using FIO with 16KB block size, virtualized environments demonstrated consistent I/O throughput suited for development workloads.
Rising Adoption of Remote Work and Virtual Desktop Infrastructure (VDI)
The shift toward remote and hybrid work models has created demand for virtual desktop solutions. Enterprises deploy VMs to securely host desktops and apps for remote users. Virtual machines help protect sensitive data while enabling remote access through secure tunnels. The Virtual Machine Market grows as VDI adoption expands across healthcare, education, and finance. IT teams benefit from centralized management, policy enforcement, and real-time patching. It reduces the need for endpoint maintenance and limits device-level vulnerabilities. VMs support bring-your-own-device (BYOD) setups without compromising enterprise security. VDI solutions improve workforce mobility and productivity.
Market Trends
Increased Adoption of Open-Source Hypervisors and Community-Driven Virtualization Tools
Enterprises are turning to open-source hypervisors like KVM and Xen for cost-effective VM deployment. These tools offer greater customization and avoid vendor lock-in. Community-driven support accelerates feature innovation and vulnerability patching. The Virtual Machine Market witnesses steady interest in non-proprietary VM ecosystems. Organizations use open-source stacks for internal labs, edge devices, and scalable systems. These hypervisors integrate well with Linux-based automation tools. The trend aligns with broader adoption of open infrastructure and cost optimization strategies. Open-source VMs gain traction in educational institutions, startups, and SMEs.
- For instance, Red Hat migrated its RHEL 6 virtualization platform to KVM, replacing Xen as the default hypervisor. This shift enabled scalable deployments with improved isolation and throughput, with benchmark tests showing KVM matching or exceeding Xen performance in enterprise workloads.
Integration of Artificial Intelligence and Automation for Virtual Machine Optimization
AI tools are being deployed to manage VM workload balancing, fault detection, and predictive scaling. These systems monitor resource usage and adjust VM allocation automatically. The Virtual Machine Market sees vendors embedding AI into orchestration and monitoring platforms. Automated tuning of CPU, memory, and storage use boosts performance. It reduces downtime, manual intervention, and misconfigurations. AI-driven tools also improve energy efficiency by dynamically powering down idle VMs. Enterprises use AI to anticipate resource needs based on usage patterns. These trends support more self-healing and intelligent virtual environments.
- For instance, a CNN-LSTM framework forecasted VM resource utilization across CPU and memory metrics, helping reduce load balancing issues and over-provisioning during hybrid cloud simulations.
Edge Virtualization is Enabling Lightweight VM Use in Low-Latency Environments
Edge computing drives demand for VMs that run on compact, distributed infrastructure. Lightweight virtual machines are being deployed near IoT endpoints and 5G base stations. The Virtual Machine Market adapts to performance requirements in low-bandwidth, high-response areas. Edge VMs support content delivery, real-time analytics, and localized processing. These environments prioritize small footprint, fast boot times, and secure isolation. Vendors offer micro-VMs to support high availability in constrained locations. Growth of autonomous systems, industrial automation, and AR/VR further supports this trend. Virtualization at the edge ensures seamless compute availability without centralized dependencies.
Rise of Virtual Machines in Cybersecurity Labs and Digital Forensics Environments
Cybersecurity teams use isolated VMs to test malware, simulate attacks, and perform reverse engineering. VMs protect physical systems while enabling in-depth behavioral analysis. The Virtual Machine Market benefits from expanded use in cyber ranges and forensics training labs. Analysts deploy disposable VMs to examine unknown files and track attack vectors. VM snapshots help capture system states during intrusion simulations. Government agencies and enterprises use VMs to improve incident response and analyst training. Controlled environments limit exposure during vulnerability testing. Demand for safe, reproducible environments drives adoption in security operations centers.
Market Challenges Analysis
Resource Overhead and Performance Bottlenecks in High-Density Virtual Environments
While virtual machines improve flexibility, they also introduce latency and resource overhead. Running multiple VMs on a single host strains CPU, memory, and storage subsystems. Performance degradation becomes evident in I/O-heavy or real-time applications. The Virtual Machine Market faces challenges when organizations try to scale without adequate infrastructure planning. Oversubscription of resources can lead to slow responses and unstable workloads. Managing VM sprawl and ensuring resource fairness remains difficult. Operators must implement strict governance, monitoring, and capacity planning protocols. Performance tuning across hosts requires specialized skills and consistent optimization.
Security Risks Due to VM Escape, Misconfigurations, and Hypervisor Vulnerabilities
Virtual environments can introduce new cybersecurity risks if not properly configured. VM escape attacks, where a guest VM gains access to the host, pose serious threats. Misconfigured virtual switches, outdated hypervisors, or weak isolation increase exposure. The Virtual Machine Market must address risks linked to multi-tenancy and unauthorized access. Admin interfaces and API endpoints become attack surfaces. Organizations struggle to maintain patch hygiene across large VM fleets. Regulatory compliance also becomes complex in dynamic, virtualized networks. Effective segmentation, encryption, and monitoring are critical to mitigate risks.
Market Opportunities
Expansion of Virtual Machines in Emerging Markets Through Affordable Cloud Offerings
Cloud providers are introducing region-specific services to support SMBs and startups in developing countries. These providers offer VM-based solutions that reduce IT investment costs and improve access to modern tools. The Virtual Machine Market gains traction in regions like Southeast Asia, Latin America, and Africa. Localized datacenters and hybrid cloud services create new demand for VMs in education, retail, and e-commerce. This supports digital growth in underserved markets.
Growing Use of Virtual Machines in Education, Simulation, and Skill-Based Labs
Academic institutions and online learning platforms use VMs for teaching software, coding, and cybersecurity. Virtual labs help replicate real-world environments for practical training. The Virtual Machine Market benefits from rising demand for remote, scalable, and resettable setups. Students can access hands-on learning without the need for physical labs. VMs support certifications, simulations, and sandbox testing across disciplines.
Market Segmentation Analysis:
By Product
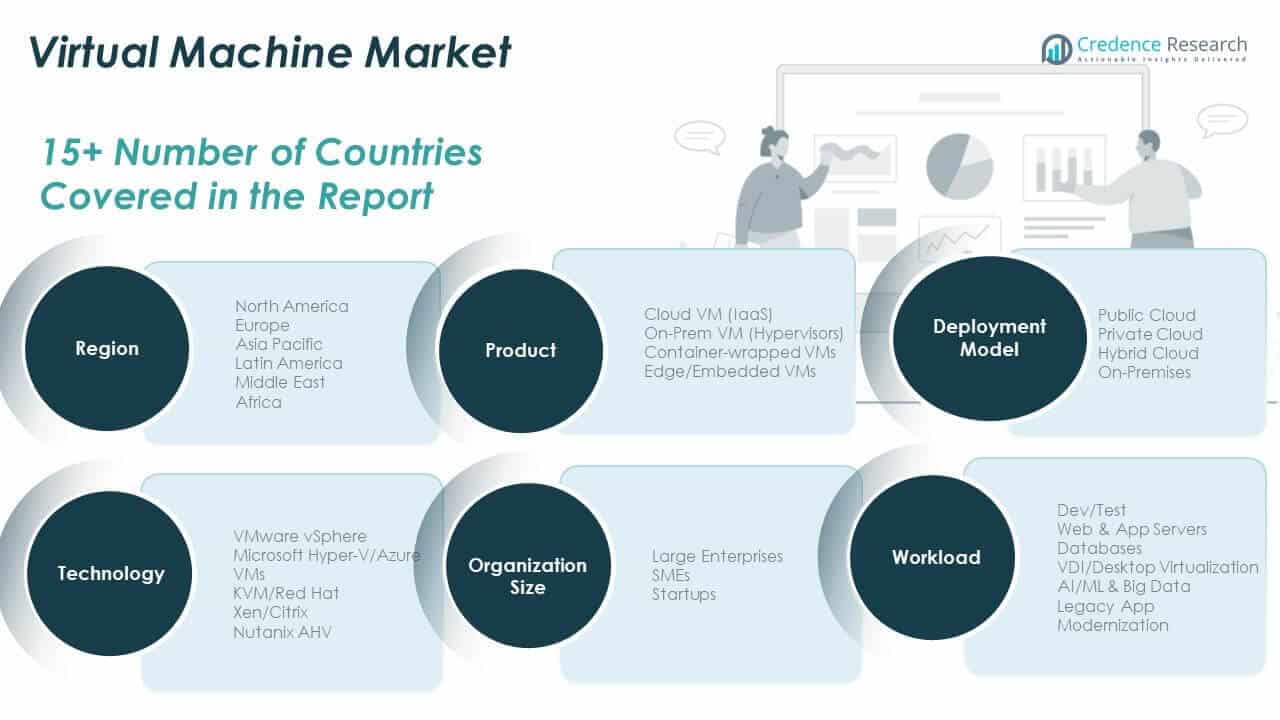
The Virtual Machine Market is driven by strong adoption of Cloud VM (IaaS) across enterprises seeking scalable infrastructure. It supports dynamic workloads and enables global access with minimal physical investment. On-Prem VM (Hypervisors) continues to serve sectors with strict regulatory and security requirements. Container-wrapped VMs are gaining momentum among DevOps teams managing microservices. Edge/Embedded VMs are emerging in real-time, localized computing environments like retail, telecom, and industrial automation.
- For instance, AWS commits to 99.99% monthly uptime for EC2 in multi-AZ deployments under its SLA. This supports dynamic workloads and enables global access with minimal physical investment, reinforcing its role in virtualized cloud environments.
By Deployment Model
Public cloud remains the dominant deployment model due to flexibility, ease of access, and cost advantages. Hybrid cloud deployment is rising quickly as businesses balance workload placement between cloud and on-premises systems. Private cloud serves industries with sensitive data and compliance needs. On-premises models continue in legacy-heavy IT environments that prioritize in-house control and fixed infrastructure.
By Technology
VMware vSphere leads the technology landscape due to its robust enterprise-grade virtualization tools. Microsoft Hyper-V and Azure VMs follow closely, especially among Windows-centric IT infrastructures. KVM / Red Hat offer open-source flexibility and are preferred in Linux-based ecosystems. Xen / Citrix solutions support desktop virtualization and secure remote access. Nutanix AHV is expanding its footprint in hyper-converged and multi-cloud environments.
- For instance, Hyper-V in Windows Server 2022 supports up to 24 TB RAM per VM, enabling high-performance virtualization for memory-intensive applications. KVM / Red Hat provide open-source flexibility and remain preferred in Linux-based environments for their scalability and integration features.
By Organization Size
Large enterprises account for the largest share of adoption, driven by complex and global IT operations. SMEs are embracing virtual machines to reduce physical infrastructure costs while maintaining scalability. Startups leverage VMs for rapid application development, testing, and cloud-native deployments, often using lightweight and modular architectures.
By Workload
Development and testing environments are the most common VM workloads, offering isolated and repeatable setups. Web and application servers follow as core business functions shift online. Databases, VDI, and AI/ML workloads require high performance and resource flexibility. Legacy app modernization also drives VM usage, helping businesses shift from outdated systems without full replatforming.
Segmentation:
By Product
- Cloud VM (IaaS)
- On-Prem VM (Hypervisors)
- Container-wrapped VMs
- Edge/Embedded VMs
By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- On-Premises
By Technology
- VMware vSphere
- Microsoft Hyper-V / Azure VMs
- KVM / Red Hat
- Xen / Citrix
- Nutanix AHV
By Organization Size
- Large Enterprises
- SMEs
- Startups
By Workload
- Dev/Test
- Web & App Servers
- Databases
- VDI / Desktop Virtualization
- AI/ML & Big Data
- Legacy App Modernization
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Virtual Machine Market size was valued at USD 2,728.80 million in 2018 to USD 4,441.24 million in 2024 and is anticipated to reach USD 13,286.56 million by 2032, at a CAGR of 14.8% during the forecast period. North America holds the largest share of the global Virtual Machine Market, accounting for approximately 37.5% in 2024. This leadership is supported by a mature cloud ecosystem, extensive data center presence, and strong enterprise IT budgets. The U.S. remains the primary driver, with high adoption across BFSI, healthcare, and technology sectors. Virtual desktop infrastructure and cloud-native application development are widespread across organizations. Key players like Microsoft, VMware, and AWS maintain aggressive innovation cycles in this region. Regulatory compliance requirements also push virtualization adoption across sensitive industries. Demand for hybrid cloud strategies continues to strengthen the regional market outlook.
Europe
The Europe Virtual Machine Market size was valued at USD 1,828.80 million in 2018 to USD 2,890.20 million in 2024 and is anticipated to reach USD 8,159.87 million by 2032, at a CAGR of 14.0% during the forecast period. Europe represents around 24.4% of the global market share in 2024. The region shows consistent growth due to digital transformation in manufacturing, government, and financial services. Countries like Germany, the UK, and France invest in hybrid cloud infrastructure and edge computing deployments. GDPR and other regional compliance laws encourage secure virtual environments and controlled data flows. European enterprises are embracing container-wrapped VMs and open-source hypervisors for cost optimization. Green IT initiatives also favor virtual machines due to reduced energy consumption and hardware consolidation. Growth in remote work has further driven demand for virtual desktops across public and private sectors.
Asia Pacific
The Asia Pacific Virtual Machine Market size was valued at USD 1,670.40 million in 2018 to USD 2,879.21 million in 2024 and is anticipated to reach USD 9,564.46 million by 2032, at a CAGR of 16.3% during the forecast period. Asia Pacific holds a 24.3% market share in 2024, emerging as the fastest-growing regional segment. Strong cloud adoption in China, India, Japan, and Southeast Asia is propelling virtualization demand. Governments and telecom firms invest heavily in data center infrastructure to support digital economies. SMEs in the region use virtual machines to scale operations without high capital investment. Demand is rising in e-commerce, fintech, and mobile services where agility is crucial. Regional tech vendors offer competitive virtualization platforms, driving local adoption. The need for low-latency edge computing also boosts interest in embedded VMs for real-time applications.
Latin America
The Latin America Virtual Machine Market size was valued at USD 561.60 million in 2018 to USD 917.55 million in 2024 and is anticipated to reach USD 2,588.04 million by 2032, at a CAGR of 14.0% during the forecast period. The region contributes around 7.7% to the global market share in 2024. Growth is led by Brazil and Mexico, where cloud migration efforts and IT modernization are underway. Enterprises seek cost-effective infrastructure to support development and testing workloads. Regional data center expansions by global providers support wider VM deployments. Startups in fintech, education, and logistics are adopting virtual environments for flexible scaling. Connectivity improvements also support broader use of cloud-hosted virtual desktops. Public cloud partnerships with regional telcos are making virtualization more accessible to mid-sized businesses.
Middle East
The Middle East Virtual Machine Market size was valued at USD 252.00 million in 2018 to USD 386.43 million in 2024 and is anticipated to reach USD 1,033.71 million by 2032, at a CAGR of 13.2% during the forecast period. It holds a 3.3% market share in 2024, driven by cloud-first strategies across the UAE, Saudi Arabia, and Israel. Governments and enterprises are adopting virtual machines to streamline infrastructure modernization. Demand is strong across oil & gas, banking, and defense sectors that need secure, isolated compute environments. Regional data centers by AWS, Oracle, and Microsoft support VM growth across IaaS and hybrid models. Initiatives like smart cities and AI innovation hubs are boosting reliance on scalable virtual environments. The region also focuses on private cloud and on-prem VM deployment due to data localization policies.
Africa
The Africa Virtual Machine Market size was valued at USD 158.40 million in 2018 to USD 341.50 million in 2024 and is anticipated to reach USD 883.25 million by 2032, at a CAGR of 12.3% during the forecast period. Africa accounts for a 2.9% share of the global market in 2024. Growth is fueled by expanding digital infrastructure in South Africa, Nigeria, and Kenya. Cloud adoption is increasing among telecom, public services, and SMEs seeking flexible IT tools. Virtual machines offer low-cost compute options for startups and educational institutions. International cloud providers are partnering with regional players to deploy local services. Demand for remote learning and e-health platforms supports VDI and lightweight VM use. Despite infrastructure challenges, the region presents long-term potential for virtualization technology expansion.
Key Player Analysis:
- VMware (Broadcom)
- Microsoft (Hyper‑V / Azure VMs)
- Amazon Web Services (EC2)
- Google Cloud (Compute Engine)
- Oracle (VM / Cloud Infrastructure)
Competitive Analysis:
The Virtual Machine Market features a competitive landscape led by global technology providers offering full-stack virtualization and cloud platforms. VMware (Broadcom) holds a strong enterprise presence with its vSphere ecosystem and hybrid cloud integration. Microsoft continues to expand Hyper-V and Azure VM services through broad compatibility and enterprise adoption. Amazon Web Services dominates the IaaS space with EC2, while Google Cloud gains traction with Compute Engine for developers and AI workloads. Oracle strengthens its position with VM services integrated into its cloud infrastructure. It shows rising competition from open-source solutions like KVM and Red Hat, favored for customization and lower TCO. The market sees active strategies in mergers, new product rollouts, and regional expansions. Players focus on workload optimization, AI-based VM orchestration, and container integration. Strong brand ecosystems, pricing models, and partnerships determine long-term positioning in this market.
Recent Developments:
- In October 2025, Cisco launched the Nexus N9100 switch series, powered by NVIDIA Spectrum-X Ethernet silicon, integrated with NVIDIA for AI infrastructure. This supports NVIDIA Cloud Partner-compliant AI factories and high-speed fabrics for virtual machine workloads.
- In August 2025, Amazon Web Services launched a new VMware service offering VMware Cloud Foundation integration as the last major cloud provider to do so, following Microsoft Azure and Google Cloud VMware Engine.
Report Coverage:
The research report offers an in-depth analysis based on Product, Deployment Model, Organization Size, Technology and Workload. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Cloud-native adoption will drive high demand for scalable virtual machines in IaaS and hybrid setups.
- AI and automation will enhance VM lifecycle management, improving workload orchestration and resource efficiency.
- Edge and embedded VMs will expand in smart factories, telecom, and real-time analytics environments.
- Container-wrapped VMs will gain traction as enterprises balance security and portability in microservice deployment.
- Growth in DevOps and CI/CD pipelines will support VM use for testing, staging, and pre-production workloads.
- Virtual Desktop Infrastructure (VDI) will see steady adoption in remote-first and security-sensitive sectors.
- Open-source hypervisors will increase market competition, especially among SMEs and tech startups.
- Large enterprises will continue to dominate usage due to extensive virtualization across global operations.
- Demand from Asia Pacific will outpace other regions, driven by digital infrastructure and cloud service expansion.
- Regulatory compliance and data localization will increase private and hybrid cloud VM deployments globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Need for Efficient Resource Utilization Across Diverse IT Environments
Organizations are adopting virtual machines to reduce hardware costs and maximize server efficiency by running multiple operating systems on a single machine. This enables better utilization of computing resources, supports lean IT operations, and reduces total cost of ownership, making VMs attractive for enterprises seeking to optimize infrastructure.
Rapid Expansion of Cloud Services and Scalable Computing Infrastructure
The proliferation of public, private, and hybrid cloud services relies heavily on virtual machines to deliver scalable, flexible infrastructure. Cloud-based VMs enable workload migration, global service delivery, and support unpredictable user traffic, driving market growth as enterprises digitize operations.
Growing Demand for DevOps, CI/CD, and Testing Environments in Software Development
Software development teams use virtual machines to create isolated, repeatable environments for testing, deployment, and debugging. The rise of CI/CD pipelines and agile workflows increases VM adoption, as they enable automation, faster release cycles, and reliable application rollouts.
Rising Adoption of Remote Work and Virtual Desktop Infrastructure (VDI)
The shift to remote and hybrid work models has accelerated demand for virtual desktop solutions, with enterprises deploying VMs to securely host desktops and applications for remote users. This supports centralized management, enhances security, and improves workforce mobility and productivity.
Expansion of Virtual Machines in Emerging Markets Through Affordable Cloud Offerings
Cloud providers are introducing cost-effective VM-based solutions in developing regions, enabling SMBs and startups to access modern IT tools without significant capital investment. This expansion supports digital growth in regions like Southeast Asia, Latin America, and Africa, broadening the global market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Virtual Machine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Virtual Machine Market projected to grow between 2024 and 2032?
Which Virtual Machine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Virtual Machine Market?
Who are the leading companies in the Virtual Machine Market?
Which region commanded the largest share of the Virtual Machine Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Cloud VM (IaaS)
- 1.2.2 On-Prem VM (Hypervisors)
- 1.2.3 Container-wrapped VMs
- 1.2.4 Edge/Embedded VMs
- 1.3 By Workload
- 1.3.1 Dev/Test
- 1.3.2 Web & App Servers
- 1.3.3 Databases
- 1.3.4 VDI / Desktop Virtualization
- 1.3.5 AI/ML & Big Data
- 1.3.6 Legacy App Modernization
- 1.4 By Technology
- 1.4.1 VMware vSphere
- 1.4.2 Microsoft Hyper-V / Azure VMs
- 1.4.3 KVM / Red Hat
- 1.4.4 Xen / Citrix
- 1.4.5 Nutanix AHV
- 1.5 By Deployment Model
- 1.5.1 Public Cloud
- 1.5.2 Private Cloud
- 1.5.3 Hybrid Cloud
- 1.5.4 On-Premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,856.14 million → 2032: USD 35,515.90 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Virtual Machine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Virtual Machine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Virtual Machine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Virtual Machine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Virtual Machine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Virtual Machine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Virtual Machine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Virtual Machine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,856.14 million → 2032: USD 35,515.90 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Virtual Machine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cloud VM (IaaS)
- 12.3.7.2 On-Prem VM (Hypervisors)
- 12.3.7.3 Container-wrapped VMs
- 12.3.7.4 Edge/Embedded VMs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Workload - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dev/Test
- 12.4.7.2 Web & App Servers
- 12.4.7.3 Databases
- 12.4.7.4 VDI / Desktop Virtualization
- 12.4.7.5 AI/ML & Big Data
- 12.4.7.6 Legacy App Modernization
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 VMware vSphere
- 12.5.7.2 Microsoft Hyper-V / Azure VMs
- 12.5.7.3 KVM / Red Hat
- 12.5.7.4 Xen / Citrix
- 12.5.7.5 Nutanix AHV
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Model - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Public Cloud
- 12.6.7.2 Private Cloud
- 12.6.7.3 Hybrid Cloud
- 12.6.7.4 On-Premises
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Virtual Machine Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Virtual Machine Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Virtual Machine Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 VMware (Broadcom)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Microsoft
- 17.4 Amazon Web Services
- 17.5 Google Cloud
- 17.6 Oracle
- 17.7 Red Hat (IBM)
- 17.8 Citrix
- 17.9 Nutanix
- 17.10 Huawei
- 17.11 Dell Technologies
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

