
Market Overview
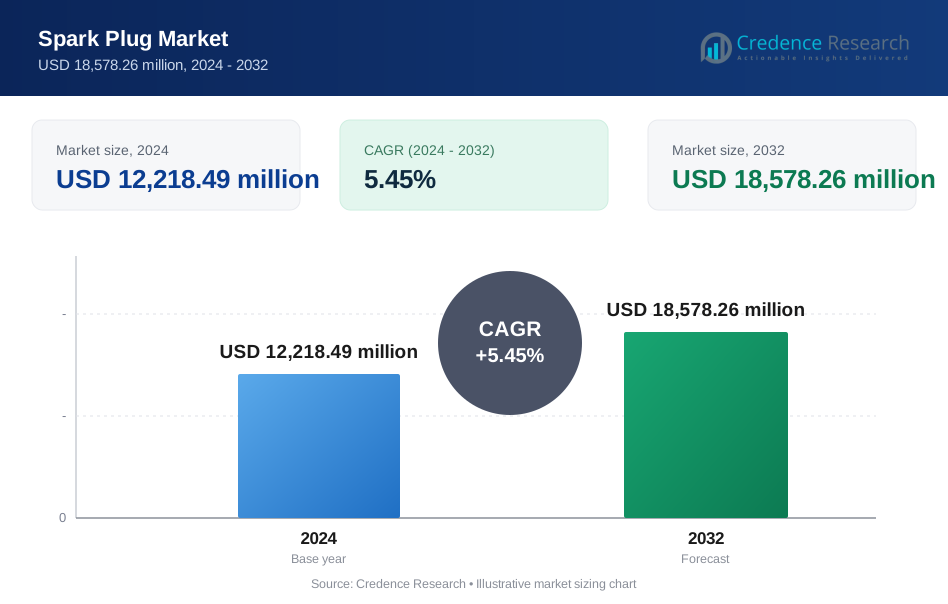
The Spark Plug Market size was valued at USD 10,420.00 million in 2018, increasing to USD 12,218.49 million in 2024, and is anticipated to reach USD 18,578.26 million by 2032, growing at a CAGR of 5.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spark Plug Market Size 2024 | USD 12,218.49 million |
| Spark Plug Market, CAGR | 5.45% |
| Spark Plug Market Size 2032 | USD 18,578.26 million |
The global Spark Plug Market is dominated by key players such as NGK Spark Plug Co., Ltd., Denso Corporation, Robert Bosch GmbH, BorgWarner Inc., Federal-Mogul Corporation, and Valeo, which collectively account for a significant share of global revenue. These companies focus on advanced material technologies, OEM collaborations, and aftermarket expansion to strengthen their market presence. NGK and Denso lead in production scale and innovation, particularly in iridium and platinum spark plugs, enhancing durability and engine performance. Regionally, Asia Pacific holds the dominant position with 50% of the global market share in 2024, driven by massive vehicle production, growing two-wheeler demand, and established manufacturing hubs across China, Japan, and India.

Market Insights
- The Spark Plug Market was valued at USD 12,218.49 million in 2024 and is projected to reach USD 18,578.26 million by 2032, growing at a CAGR of 5.45%, with Asia Pacific holding around 50% of the global share.
- Market growth is primarily driven by rising vehicle production, the dominance of internal combustion engines, and expanding aftermarket demand in developing economies.
- Trends such as the increasing adoption of iridium and platinum spark plugs and the shift toward high-performance and hybrid vehicle applications are shaping market innovation.
- The market is moderately consolidated, with key players like NGK, Denso, Bosch, BorgWarner, and Federal-Mogul leading through technological advancements, OEM partnerships, and product diversification.
- North America and Europe collectively account for over 39% of the market share, while the hot spark plug segment dominates with 52.7% of total revenue in 2024, supported by strong demand in passenger and two-wheeler applications.
Market Segmentation Analysis:
By Type
The Hot Spark Plug segment leads the global spark plug market, accounting for around 52.7% of total revenue in 2024. This dominance is driven by its extensive use in passenger cars and two-wheelers, where efficient heat retention enhances combustion and prevents fouling in low-speed engines. Hot spark plugs are cost-effective and offer reliable performance, making them the preferred choice for standard internal combustion engines. Meanwhile, Cold Spark Plugs cater to high-performance and turbocharged engines, offering superior heat dissipation under heavy load conditions and gaining gradual adoption in the premium vehicle category.
- For instance, NGK Spark Plugs, a key player in the market, offers hot spark plugs that cover 95% of import and domestic vehicles, highlighting their broad adoption for reliable performance in everyday vehicles.
By Electrode Material
The Copper electrode material segment dominates the market with the largest share in 2024, owing to its high thermal conductivity, affordability, and suitability for mass-market vehicles. Platinum plugs hold a moderate share, supported by growing demand for long-life components and reduced maintenance intervals. The Iridium segment is the fastest-growing, driven by its exceptional durability, fuel efficiency benefits, and rising integration in premium and hybrid vehicles. Other materials, including nickel alloys and multi-electrode designs, serve niche applications across performance and specialty vehicles.
- For instance, iridium spark plugs are increasingly integrated into hybrid engines due to their longer service life and better combustion efficiency, aligning with stricter emission standards and consumer demand for premium performance in models like Toyota's hybrid series.
By End-use
The Automotive sector represents the dominant end-use segment, capturing 83.5% of the global spark plug market in 2024. Growth is fueled by increasing vehicle production, expanding fleets, and the continued reliance on gasoline-powered engines, especially in developing economies. The Marine segment follows, driven by growing recreational boating and commercial vessel operations that require durable ignition solutions for harsh environments. The Others category, including small engines and power equipment, contributes a steady demand base supported by agriculture and industrial applications.
Key Growth Drivers
Rising Vehicle Production and ICE Dominance
The continued expansion of the automotive industry, particularly in emerging economies, is a primary driver of the spark plug market. Despite the rise of electric vehicles, internal combustion engines (ICE) still dominate global vehicle production. Increasing consumer demand for passenger and light commercial vehicles supports steady replacement cycles and aftermarket sales. Additionally, growing industrialization and urban mobility have further stimulated demand for gasoline-powered vehicles, ensuring consistent consumption of spark plugs across both OEM and aftermarket channels.
- For instance, in the U.S., ICE vehicles still account for over 80 % of the overall vehicle parc despite electrification advances, ensuring large-scale ongoing demand for ignition system components like spark plugs.
Technological Advancements in Spark Plug Design
Continuous innovation in spark plug materials and design enhances performance, efficiency, and durability. Advanced materials such as iridium and platinum are gaining traction due to their superior heat resistance, improved ignition reliability, and extended service life. These innovations contribute to better fuel combustion and reduced emissions, aligning with stringent environmental standards. Automakers increasingly adopt high-performance spark plugs to meet modern engine requirements, thereby accelerating product upgrades and supporting long-term market growth.
- For instance, DENSO's Iridium TT Spark Plug features the world's smallest diameter center electrode at 0.4mm and a needle-like 0.7mm platinum ground electrode, offering a service life of up to 120,000 km, which is more than three times longer than standard nickel plugs.
Expanding Aftermarket and Maintenance Demand
The growing global vehicle fleet and increasing average vehicle age have fueled demand in the aftermarket segment. Regular maintenance and replacement needs of spark plugs, particularly in regions with high vehicle usage, sustain steady revenue flows. Additionally, the availability of diverse spark plug types at affordable prices enhances consumer accessibility. Rising awareness of vehicle efficiency and performance optimization also drives owners to opt for periodic replacements, further strengthening aftermarket growth potential across both developed and developing economies.

Key Trends & Opportunities
Shift Toward High-Performance and Iridium Spark Plugs
A key market trend involves the growing adoption of iridium and multi-electrode spark plugs that deliver improved durability and combustion efficiency. Manufacturers are focusing on developing high-performance products suitable for hybrid and downsized turbocharged engines. This shift presents significant opportunities for premium plug producers as automakers demand components that extend maintenance intervals and optimize fuel economy. The trend aligns with consumer preferences for reliability and lower operational costs, positioning advanced spark plugs as a key opportunity area.
- For instance, Bosch has engineered iridium spark plugs with nickel-coated housing for corrosion protection and advanced insulator designs, specifically tailored for turbocharged GDI engines to resist mega knocking and ensure durability.
Growth Potential in Emerging Economies
Emerging markets across Asia Pacific, Latin America, and Africa present vast opportunities due to rising vehicle ownership, industrialization, and expanding transportation networks. Increased investments in automotive manufacturing and infrastructure have spurred regional vehicle demand, particularly in the two-wheeler and passenger car segments. Additionally, the growing aftermarket distribution network in these regions supports widespread availability of spark plugs, offering a lucrative opportunity for global manufacturers to establish localized production and distribution facilities to enhance competitiveness.
- For instance, in the Asia Pacific region, NGK Spark Plug Co., Ltd. increased its production capacity in China in 2021 to meet growing demand driven by a surge in vehicle production and two-wheeler sales.
Key Challenges
Rising Adoption of Electric Vehicles
The accelerating shift toward electric mobility poses a major long-term challenge for the spark plug market. Electric vehicles (EVs) do not use spark plugs, and their increasing market penetration directly reduces demand from the automotive segment. Government incentives and emission regulations are encouraging OEMs to transition toward EV production, gradually curbing ICE vehicle output. While hybrid vehicles partially offset this impact, the long-term outlook indicates a gradual decline in spark plug demand as full electrification gains momentum globally.
Fluctuating Raw Material Prices and Supply Chain Constraints
Volatility in raw material prices particularly for platinum, iridium, and nickel creates cost uncertainties for spark plug manufacturers. These fluctuations, combined with global supply chain disruptions, can impact production costs and profit margins. The dependency on specific high-grade materials also increases vulnerability to market instability. Furthermore, logistics challenges and geopolitical tensions affecting key suppliers exacerbate the issue, compelling manufacturers to explore alternative materials, regional sourcing, and strategic inventory management to mitigate supply-related risks.
Regional Analysis
North America
The North America spark plug market was valued at USD 2,240.30 million in 2018, increasing to USD 2,573.14 million in 2024, and is anticipated to reach USD 3,903.33 million by 2032, expanding at a CAGR of 5.5%. The region holds nearly 21% of the global market share in 2024. Growth is driven by a well-established automotive sector, rising demand for vehicle maintenance, and the strong presence of leading manufacturers such as ACDelco, BorgWarner, and Autolite. The U.S. dominates the regional market, supported by a large vehicle fleet and a robust aftermarket network.
Europe
The Europe spark plug market stood at USD 1,917.28 million in 2018, reached USD 2,123.24 million in 2024, and is forecast to attain USD 2,967.93 million by 2032, growing at a CAGR of 4.4%. Europe accounts for around 18% of the global market share in 2024, supported by premium automakers and advanced engine technology adoption. Germany, France, and the UK remain key contributors, with strong OEM integration and preference for platinum and iridium spark plugs. However, the region’s gradual transition toward electric mobility may slightly restrain long-term growth.
Asia Pacific
Asia Pacific dominates the global spark plug market, valued at USD 5,074.54 million in 2018, growing to USD 6,082.93 million in 2024, and projected to reach USD 9,740.60 million by 2032, registering the highest CAGR of 6.1%. The region represents nearly 50% of the global market share in 2024. Growth is fueled by large-scale vehicle production in China, Japan, India, and South Korea, along with surging demand for two-wheelers and compact cars. Expanding manufacturing bases of NGK, Denso, and Weichai Power further strengthen regional competitiveness and export capacity.
Latin America
The Latin America spark plug market was valued at USD 562.68 million in 2018, reached USD 652.35 million in 2024, and is expected to hit USD 907.92 million by 2032, growing at a CAGR of 4.3%. The region holds about 7% of the global market share in 2024, driven by automotive production recovery in Brazil and Mexico. Rising vehicle parc, aftermarket expansion, and replacement part demand support steady growth. While economic challenges persist, the region’s relatively low EV adoption ensures continued reliance on conventional spark plugs for combustion-based engines.
Middle East
The Middle East spark plug market was valued at USD 405.34 million in 2018, reached USD 445.90 million in 2024, and is anticipated to grow to USD 613.18 million by 2032, at a CAGR of 4.2%. The region accounts for around 4% of the global market share in 2024. Growth is driven by increasing vehicle ownership, a growing aftermarket network, and rising demand for high-performance vehicles across GCC nations such as Saudi Arabia and the UAE. Import dependency and gradual EV introduction slightly limit long-term expansion.
Africa
The Africa spark plug market was valued at USD 219.86 million in 2018, rose to USD 340.95 million in 2024, and is projected to reach USD 445.31 million by 2032, growing at a CAGR of 3.0%. The region holds around 3% of the global market share in 2024. Market growth is supported by the expanding vehicle fleet, increasing aftermarket activity, and rising urbanization across South Africa, Egypt, and Nigeria. However, limited automotive manufacturing infrastructure and slower economic growth constrain large-scale expansion, keeping Africa as an emerging yet potential growth frontier.

Market Segmentations:
By Type
- Hot Spark Plug
- Cold Spark Plug
By Electrode Material:
- Copper
- Platinum
- Iridium
- Others
By End-use
- Automotive
- Marine
- Others
By Sales Channel:
- Original Equipment Manufacturer (OEM)
- Aftermarket
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Spark Plug Market is moderately consolidated, with key players including NGK Spark Plug Co., Ltd., Denso Corporation, Robert Bosch GmbH, BorgWarner Inc., Federal-Mogul Corporation, ACDelco, and Valeo dominating global sales. These companies compete through technological innovation, material advancements, and strong OEM partnerships. Leading manufacturers focus on expanding their product portfolios with iridium and platinum spark plugs to enhance fuel efficiency, durability, and emission performance. Strategic mergers, regional expansions, and R&D investments remain central to maintaining competitiveness. Asian manufacturers such as NGK and Denso lead in production capacity and global reach, while European and American firms emphasize precision engineering and aftermarket service networks. The market also witnesses increasing collaboration between automotive OEMs and spark plug producers to develop advanced ignition systems compatible with hybrid powertrains, reflecting a shift toward efficiency, longevity, and regulatory compliance in the evolving automotive ecosystem.
Key Player Analysis
- NGK Spark Plug Co., Ltd. (Japan)
- Denso Corporation (Japan)
- Robert Bosch GmbH (Germany)
- BorgWarner Inc. (USA)
- Federal-Mogul Corporation (USA)
- ACDelco (USA)
- Autolite (USA)
- E3 Spark Plugs (USA)
- Magneti Marelli S.p.A. (Italy)
- Valeo (France)
- Hyundai Motor Company (South Korea)
- Weichai Power Co., Ltd. (China)
- Brisk (Czech Republic)
- Enerpulse Technologies (USA)
- Zhuzhou Torch Spark Plug Co., Ltd. (China)
- Hella KGaA Hueck & Co. (Germany)
- Pulstar (USA)
- Stitt Spark Plug Company (USA)
Recent Developments
- In September 2025, Denso Corporation entered into an agreement to transfer its spark plug and exhaust gas sensor business to Niterra Co., Ltd. (formerly NGK Spark Plug Co., Ltd.) as part of its strategic initiative to strengthen focus on vehicle electrification and sustainable mobility solutions.
- In May 2025, Tan Chong Trading Sdn Bhd (TCT) launched the “Torch” spark plug in Malaysia through a partnership with WEICHAI Torch Technology Co. Ltd., introducing a premium ignition technology to the Malaysian aftermarket.
Report Coverage
The research report offers an in-depth analysis based on Type, Electrode Material, End Use, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The spark plug market will continue to grow steadily, supported by sustained demand for internal combustion engine vehicles in developing regions.
- Advancements in iridium and platinum materials will enhance plug durability and performance efficiency.
- The aftermarket segment will expand due to increasing vehicle age and maintenance awareness.
- Hybrid vehicle adoption will create new opportunities for specialized spark plug designs.
- Asia Pacific will remain the leading regional market, driven by high vehicle production and population growth.
- Manufacturers will focus on reducing emissions and improving ignition efficiency through advanced technologies.
- Partnerships between OEMs and component suppliers will intensify to meet evolving emission standards.
- The gradual shift toward electric vehicles will pose long-term challenges but sustain short- to mid-term demand.
- Digital retail platforms and e-commerce channels will strengthen aftermarket distribution.
- Continuous R&D investment will drive innovation in high-performance and fuel-efficient ignition systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for spark plugs by 2032?
At what Compound Annual Growth Rate is the Spark Plug Market projected to grow between 2025 and 2032?
What is the expected CAGR for the spark plug market from 2024 to 2032?
What are the primary factors driving market growth?
What regional market holds the largest share?
What are the market challenges?
Who are the leading companies in the Spark Plug Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Spark Plug Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Spark Plug Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,218.49 million → 2032: USD 18,578.26 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Spark Plug Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Spark Plug Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Spark Plug Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Spark Plug Market Drivers
- 3.3 Spark Plug Market Restraints & Challenges
- 3.4 Spark Plug Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Spark Plug Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Spark Plug Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Spark Plug category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Spark Plug Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Spark Plug Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Spark Plug market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Spark Plug Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Spark Plug Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Spark Plug Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Spark Plug (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Spark Plug Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Spark Plug Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Spark Plug Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Spark Plug Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Spark Plug Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Spark Plug Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Spark Plug Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Spark Plug Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Spark Plug Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
