
Market Overview
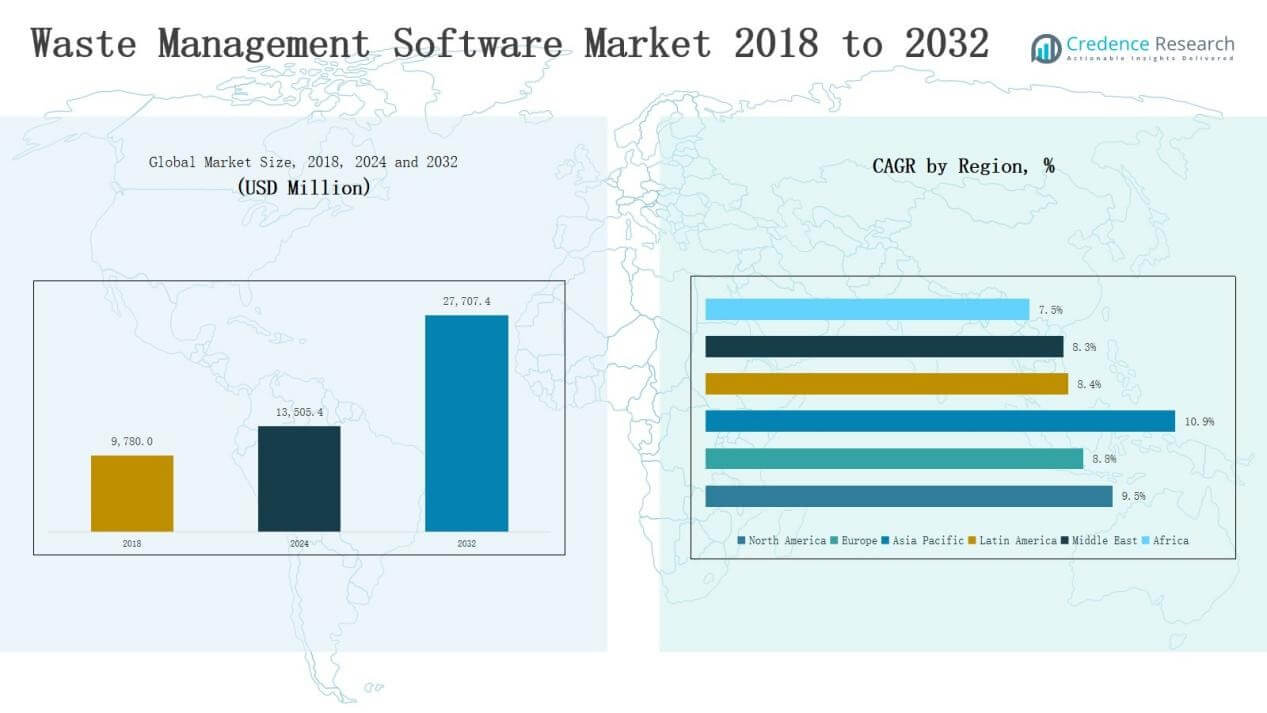
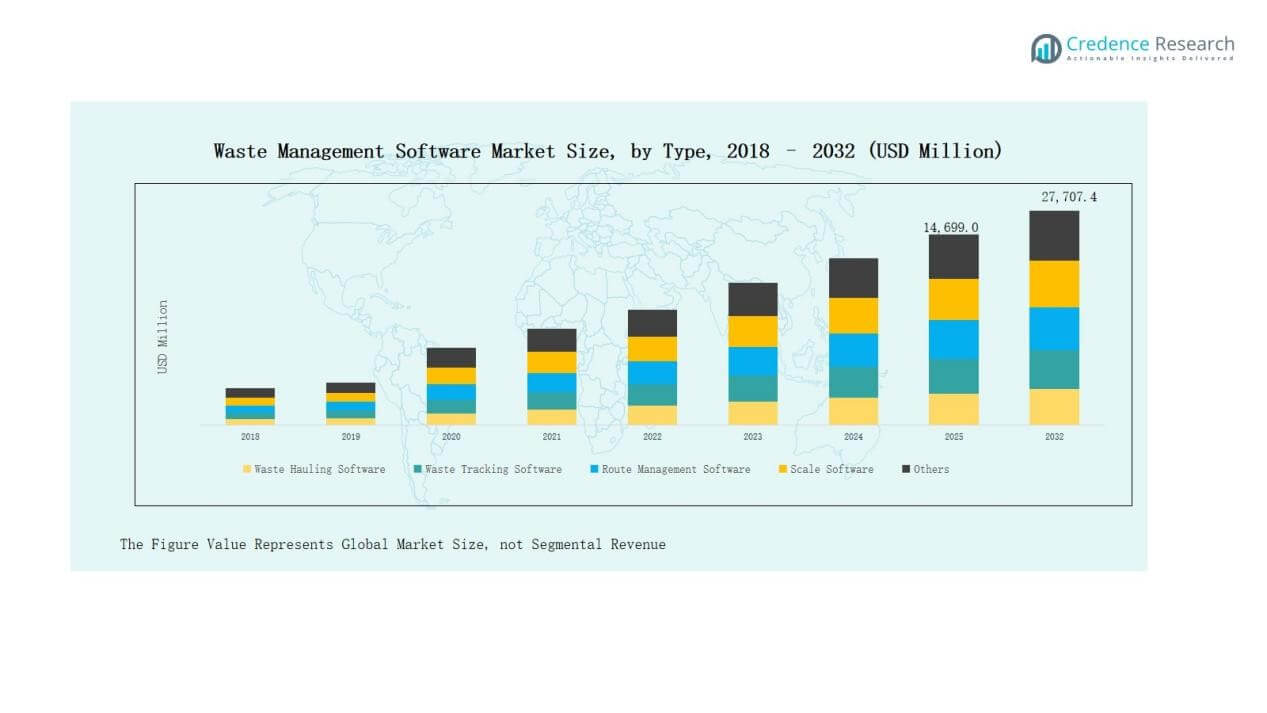
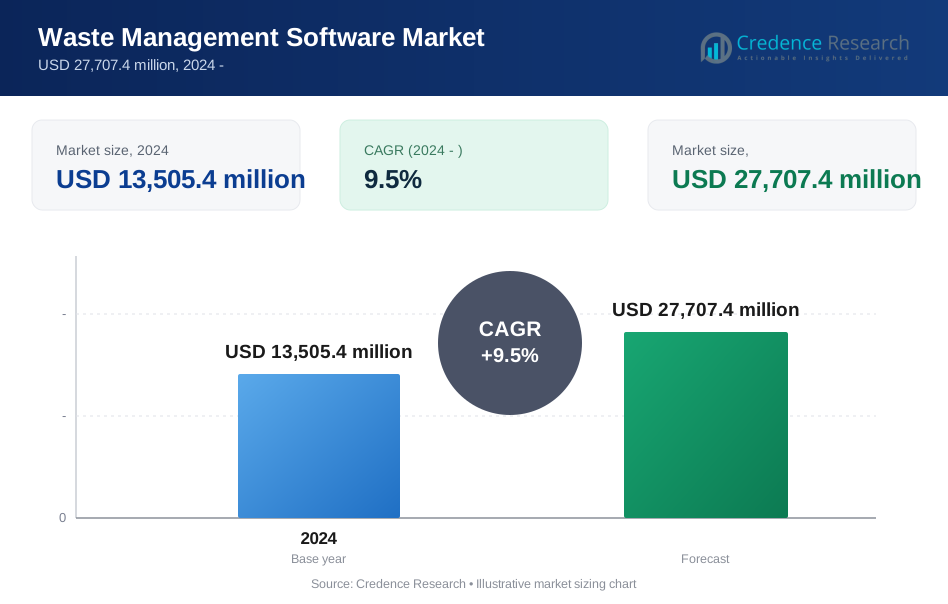
Waste Management Software Market size was valued at USD 9,780.0 million in 2018 to USD 13,505.4 million in 2024 and is anticipated to reach USD 27,707.4 million by 2032, at a CAGR of 9.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Waste Management Software Market Size 2024 | USD 13,505.4 Million |
| Waste Management Software Market, CAGR | 9.5% |
| Waste Management Software Market Size 2032 | USD 27,707.4 Million |
The Waste Management Software Market is shaped by established players such as Wastebits, AMCS Group, TRUX, WAM Software, Sequoia Waste Solutions, SEE Forge, Thoughtful Systems, DesertMicro, SFS Chemical Safety, and Delta Equipment Systems, Inc. These companies compete through advanced product portfolios, cloud-based solutions, and integration with IoT and RFID technologies to improve efficiency and compliance. Strategic partnerships with municipalities, industrial operators, and healthcare providers strengthen their market presence, while smaller vendors focus on cost-effective and niche applications. North America leads the global market with a 36% share in 2024, driven by early technology adoption, strong regulatory frameworks, and large-scale municipal projects.
Market Insights
- The Waste Management Software Market grew from USD 9,780.0 million in 2018 to USD 13,505.4 million in 2024, and is expected to reach USD 27,707.4 million by 2032.
- Leading players include Wastebits, AMCS Group, TRUX, WAM Software, Sequoia Waste Solutions, SEE Forge, Thoughtful Systems, DesertMicro, SFS Chemical Safety, and Delta Equipment Systems, Inc.
- Waste hauling software leads with 28% share in 2024, while cloud-based solutions dominate the component segment with 63% share, reflecting a strong digital transformation trend.
- The municipal application segment holds the highest share at 41% in 2024, supported by increasing adoption of digital platforms for collection efficiency, compliance, and reduced operational costs.
- North America leads with 36% share in 2024, followed by Europe at 28% and Asia Pacific at 22%, with APAC expected to grow the fastest at 9% CAGR.
Market Segment Insights
By Software Type
Waste hauling software leads the market with a 28% share in 2024, driven by the growing need for optimized logistics and automated billing solutions in waste collection services. Route management software follows closely, supported by rising demand for efficient fleet scheduling in urban areas. Recycling software also shows strong momentum as governments enforce stricter sustainability and circular economy policies. The segment continues to evolve with scale and tracking software providing enhanced transparency in landfill management and waste monitoring.
By Application
The municipal segment dominates with a 41% share in 2024, as city authorities increasingly adopt digital tools to streamline collection, improve compliance, and reduce operational costs. Manufacturing follows, propelled by strict regulations on industrial waste handling and reporting. Healthcare emerges as a growing segment, reflecting higher adoption of tracking solutions for hazardous waste. Retail and other commercial applications also support growth due to rising emphasis on compliance and eco-friendly practices.
- For instance, New York City’s Department of Sanitation deployed smart waste bins equipped with sensors from Bigbelly, which helped reduce the frequency of waste collections. The manufacturer reports that its technology can reduce collection trips by as much as 80%, which, in turn, cuts fuel use.
By Component
Cloud-based software accounts for a 63% share in 2024, making it the dominant component segment. The shift is driven by its scalability, real-time data access, and cost-efficiency, which strongly appeal to both public and private operators. On-premise solutions retain relevance in organizations with strict data security policies, though their adoption is slowing. The continued preference for cloud deployment highlights the industry’s move toward digital transformation and integrated waste management systems.
- For instance, Google Cloud’s deployment with Veolia has enabled AI-driven waste tracking and optimization across multiple regions, allowing more accurate forecasting and recycling efficiency.
Market Overview
Key Growth Drivers
Rising Urbanization and Waste Volumes
The increasing pace of urbanization worldwide is leading to higher municipal solid waste generation, creating significant pressure on waste collection and disposal systems. Cities face challenges in managing growing waste volumes while maintaining efficiency and compliance with environmental standards. Waste management software addresses these needs by optimizing route planning, enhancing collection monitoring, and improving reporting systems. Municipal authorities and private operators increasingly adopt these solutions to streamline operations and reduce costs, making urban waste growth a key driver of market expansion.
- For instance, Rubicon Technologies partnered with the City of Houston in 2022 to integrate its RUBICONSmartCity platform, enabling real-time tracking of over 390 city waste and recycling trucks and improving route efficiency.
Stringent Environmental Regulations
Governments are tightening environmental regulations related to waste disposal, recycling, and emissions, compelling organizations to adopt digital solutions. Compliance requirements such as waste tracking, documentation, and hazardous material handling create strong demand for advanced management platforms. Waste management software ensures accuracy in reporting and reduces compliance risks, while enabling organizations to align with sustainability goals. Industries such as manufacturing and healthcare are particularly focused on these solutions to meet regulatory standards. This regulatory push continues to fuel software adoption across multiple sectors.
- For instance, in 2018, the U.S. Environmental Protection Agency (EPA) launched its electronic Manifest (e-Manifest) system, requiring companies nationwide to digitally track hazardous waste shipments, which has accelerated the adoption of waste management platforms.
Digital Transformation in Waste Management
The industry is undergoing a digital transformation, with increasing investment in cloud-based platforms, IoT integration, and data analytics. Organizations seek greater operational visibility and control through real-time tracking, predictive maintenance, and automated billing. Waste management software enables integration with RFID tags, GPS systems, and mobile applications, improving accuracy and efficiency. The adoption of digital solutions reduces manual errors and enhances customer service, making technology transformation one of the most influential growth drivers shaping the competitive landscape.
Key Trends & Opportunities
Integration of IoT and Smart Sensors
The adoption of IoT and smart sensor technologies is transforming waste management into a more data-driven and predictive system. Sensors embedded in bins provide real-time information on fill levels, enabling optimized collection schedules and reducing unnecessary trips. When combined with waste management software, these technologies improve efficiency, cut fuel costs, and lower carbon emissions. This trend presents opportunities for vendors to integrate advanced IoT solutions into their platforms, positioning them as essential partners in the shift toward smart city infrastructure.
- For instance, Bridgera implemented an IoT-based system providing real-time analytics to waste management teams, streamlining operations and enhancing the experience for both residents and collection drivers.
Growth in Recycling and Circular Economy Initiatives
Global emphasis on recycling and circular economy policies is generating new opportunities for specialized waste management solutions. Recycling-focused software supports better tracking of recyclable materials, ensures regulatory compliance, and improves profitability for recycling operators. Governments and corporations are investing heavily in recycling programs to reduce landfill dependency. This creates strong demand for digital platforms that can optimize material recovery and reporting processes. Vendors offering tailored recycling solutions are well-positioned to capture growth as sustainability becomes a priority worldwide.
- For instance, in 2024, Microsoft announced an update to its Cloud for Sustainability platform that helps companies track, manage, and report material recovery data in real time.
Key Challenges
High Implementation and Integration Costs
The adoption of waste management software often involves significant initial costs for licensing, training, and system integration. Smaller municipalities and private operators face budgetary constraints that limit adoption despite the long-term benefits. The complexity of integrating software with existing infrastructure and hardware, such as GPS and RFID, further raises expenses. These financial barriers slow adoption, particularly in developing regions, where cost sensitivity is high. Vendors must address affordability and scalability to expand their customer base effectively.
Data Security and Privacy Concerns
As cloud-based platforms dominate the market, data security and privacy concerns have become critical challenges. Waste management software stores sensitive information related to municipalities, industries, and consumer operations. Breaches or unauthorized access could result in regulatory penalties and reputational damage. Organizations in sectors like healthcare and manufacturing are especially cautious about adopting cloud-based platforms due to compliance risks. Ensuring robust cybersecurity measures and adherence to data protection laws is essential for vendors to maintain trust and expand adoption.
Resistance to Technology Adoption
Despite the benefits, many organizations and municipalities remain hesitant to shift from traditional practices to digital waste management systems. Resistance often arises from lack of awareness, limited technical expertise, or concerns about operational disruptions during transition. In some regions, workforce training and cultural barriers further slow implementation. This reluctance reduces the speed of market penetration for new solutions. Vendors must invest in awareness campaigns and provide seamless onboarding processes to overcome adoption resistance and unlock growth potential.
Regional Analysis
North America
North America dominates the Waste Management Software Market with a 36% share in 2024, supported by advanced infrastructure and early adoption of digital technologies. The market is projected to grow from USD 4,897.0 million in 2024 to USD 10,030.9 million by 2032, reflecting a CAGR of 9.5%. Strong regulatory frameworks, large-scale municipal projects, and increasing use of cloud-based platforms drive growth. The U.S. leads the region due to extensive waste volumes and smart city initiatives. Canada and Mexico follow with rising investments in automation and recycling-focused software.
Europe
Europe holds a 28% share in 2024, reaching USD 3,821.7 million, and is expected to climb to USD 7,452.0 million by 2032 at a CAGR of 8.8%. The region benefits from strict environmental regulations and circular economy policies, pushing municipalities and private operators to adopt advanced waste management solutions. Countries such as Germany, the UK, and France lead adoption due to established recycling frameworks. Cloud-based software demand is increasing rapidly, supported by EU-driven sustainability goals and investments in smart infrastructure.
Asia Pacific
Asia Pacific accounts for a 22% share in 2024, with revenues growing from USD 3,023.1 million in 2024 to USD 6,911.1 million by 2032 at the fastest CAGR of 10.9%. Rapid urbanization, expanding industrial bases, and government investments in smart waste management systems are fueling adoption. China, Japan, and India are key growth engines due to rising waste volumes and strict regulations on industrial and hazardous waste. Emerging economies in Southeast Asia further contribute, adopting cloud-based and IoT-integrated software to modernize collection and disposal systems.
Latin America
Latin America represents a 6% share in 2024, valued at USD 815.6 million, and is forecast to reach USD 1,548.3 million by 2032 at a CAGR of 8.4%. The region is increasingly focused on modernizing its waste management systems, with Brazil and Argentina driving software adoption. Growth is supported by urban expansion, improved recycling initiatives, and government efforts to upgrade municipal infrastructure. However, limited budgets in smaller cities remain a barrier. Vendors targeting affordable, cloud-based solutions are well-positioned to capture opportunities in this region.
Middle East
The Middle East captures a 5% share in 2024, with revenues of USD 572.5 million, projected to grow to USD 1,078.0 million by 2032 at a CAGR of 8.3%. GCC countries lead the market due to strong investments in smart city projects and infrastructure modernization. Waste tracking and route optimization software are in high demand to manage rising urban waste volumes. Israel and Turkey also contribute to regional adoption, supported by regulatory compliance needs and sustainability programs. Growing emphasis on eco-friendly practices creates long-term opportunities for vendors.
Africa
Africa holds a 3% share in 2024, valued at USD 375.5 million, and is projected to expand to USD 687.2 million by 2032 at a CAGR of 7.5%. South Africa leads the regional market, followed by Egypt, driven by initiatives to improve municipal waste management systems. Adoption is gradually increasing as governments and private operators invest in digital solutions to address rising waste volumes and compliance requirements. However, high implementation costs and limited technical expertise slow adoption. Cloud-based, low-cost platforms are expected to play a crucial role in unlocking growth in Africa.
Market Segmentations:
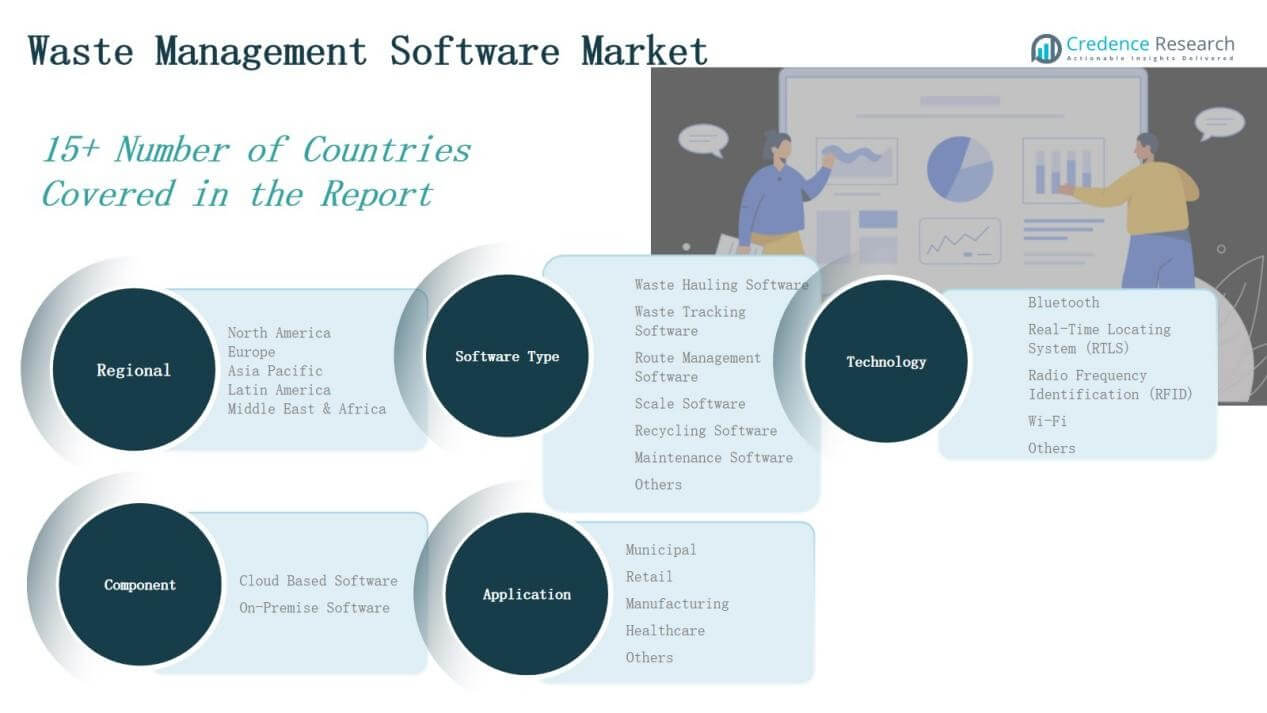
By Software Type
- Waste Hauling Software
- Waste Tracking Software
- Route Management Software
- Scale Software
- Recycling Software
- Maintenance Software
- Others
By Application
- Municipal
- Retail
- Manufacturing
- Healthcare
- Others
By Component
- Cloud-Based Software
- On-Premise Software
By Technology
- Bluetooth
- Real-Time Locating System (RTLS)
- Radio Frequency Identification (RFID)
- Wi-Fi
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Waste Management Software Market features a mix of global leaders and regional providers competing through technology innovation, service reliability, and customer-centric solutions. Key players such as Wastebits, AMCS Group, TRUX, WAM Software, and Sequoia Waste Solutions strengthen their positions with comprehensive product portfolios covering waste hauling, tracking, and recycling management. Cloud-based offerings, integration with IoT and RFID, and mobile-enabled platforms are central to competitive differentiation. Companies also focus on partnerships with municipalities, industrial clients, and private waste operators to expand adoption. Smaller vendors such as SEE Forge, Thoughtful Systems, and DesertMicro emphasize cost-effective solutions tailored for niche markets. Mergers, acquisitions, and product upgrades remain common strategies to extend geographic presence and improve scalability. With rising demand for compliance-driven and eco-friendly solutions, competition continues to intensify, prompting players to invest in advanced analytics, route optimization, and sustainability-focused features to maintain long-term market relevance.
Key Players
- Wastebits
- AMCS Group
- SEE Forge
- TRUX
- WAM Software, Inc.
- Thoughtful Systems, Inc.
- Sequoia Waste Solutions
- DesertMicro
- SFS Chemical Safety
- Delta Equipment Systems, Inc.
Recent Developments
- In October 2024, Tomra Systems ASA acquired C-trace GmbH, a German provider of digital waste-management solutions, to strengthen its waste management software capabilities and expand its digital sustainability offerings.
- In May 2025, AMCS Groupcompleted two strategic acquisitions. The company acquired Selected Interventions(London-based) and Mandalay Technologies (Australia-based), expanding its software and data capabilities.
- In May 2025, WasteLinq(Houston-based waste management software firm) introduced a free versionof its digital platform for waste generators. This move helps broaden access to modern waste software tools.
- In July 2025, the Solid Waste Association of North America (SWANA)entered a corporate partnership with Paradigm Software, L.L.C.®. The goal is to advance safety and tech in waste and resource management, with SWANA sponsoring safety awards and events supported by Paradigm's software suite.
Report Coverage
The research report offers an in-depth analysis based on Software Type, Application, Component, Technology, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of cloud-based platforms will continue to expand across all regions.
- Municipalities will increasingly rely on digital tools to streamline waste collection.
- Recycling-focused software will gain momentum due to circular economy initiatives.
- Integration of IoT devices and smart sensors will enhance real-time monitoring.
- AI-driven analytics will support predictive maintenance and route optimization.
- Healthcare and manufacturing sectors will adopt advanced tracking for hazardous waste.
- Partnerships between software providers and municipal governments will strengthen.
- Mobile-enabled solutions will see higher usage among small and mid-sized operators.
- Cybersecurity measures will become a critical focus in cloud deployments.
- Emerging economies will adopt affordable and scalable platforms to modernize operations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Waste Volumes
Rapid urbanization is increasing municipal solid waste generation, putting pressure on cities to manage larger waste volumes efficiently. Waste management software helps optimize collection routes, monitor operations, and reduce costs, making it essential for municipalities and private operators facing growing urban waste challenges.
Stringent Environmental Regulations
Governments are enforcing stricter regulations on waste disposal, recycling, and emissions, requiring organizations to adopt digital solutions for compliance. Waste management software enables accurate tracking, documentation, and reporting, helping industries and municipalities meet regulatory standards and avoid penalties.
Digital Transformation and Cloud Adoption
The shift toward cloud-based platforms, IoT integration, and data analytics is transforming waste management operations. Cloud-based software offers scalability, real-time data access, and cost efficiency, driving widespread adoption among public and private sector operators seeking operational visibility and automation.
Growth in Recycling and Circular Economy Initiatives
Global emphasis on recycling and circular economy policies is increasing demand for specialized waste management software. These platforms support material tracking, regulatory compliance, and profitability for recycling operators, aligning with sustainability goals and reducing landfill dependency.
Integration of IoT and Smart Sensors
The adoption of IoT devices and smart sensors in waste bins and collection vehicles enables real-time monitoring and predictive analytics. This integration with waste management software optimizes collection schedules, reduces fuel costs, and supports smart city initiatives, enhancing operational efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Waste Management Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Waste Management Software Market projected to grow between 2025 and 2032?
Which Waste Management Software Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Waste Management Software Market?
Who are the leading companies in the Waste Management Software Market?
Which region commanded the largest share of the Waste Management Software Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Cloud-Based Software
- 1.2.2 On-Premise Software
- 1.3 By Technology
- 1.3.1 Bluetooth
- 1.3.2 Real-Time Locating System (RTLS)
- 1.3.3 Radio Frequency Identification (RFID)
- 1.3.4 Wi-Fi
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Municipal
- 1.4.2 Retail
- 1.4.3 Manufacturing
- 1.4.4 Healthcare
- 1.4.5 Others
- 1.5 By Software Type
- 1.5.1 Waste Hauling Software
- 1.5.2 Waste Tracking Software
- 1.5.3 Route Management Software
- 1.5.4 Scale Software
- 1.5.5 Recycling Software
- 1.5.6 Maintenance Software
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13,505.4 million → 2032: USD 27,707.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Waste Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Waste Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Waste Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Waste Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Waste Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Waste Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Waste Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Waste Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13,505.4 million → 2032: USD 27,707.4 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Waste Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Cloud-Based Software
- 12.3.6.2 On-Premise Software
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Bluetooth
- 12.4.6.2 Real-Time Locating System (RTLS)
- 12.4.6.3 Radio Frequency Identification (RFID)
- 12.4.6.4 Wi-Fi
- 12.4.6.5 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Municipal
- 12.5.6.2 Retail
- 12.5.6.3 Manufacturing
- 12.5.6.4 Healthcare
- 12.5.6.5 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Software Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Waste Hauling Software
- 12.6.6.2 Waste Tracking Software
- 12.6.6.3 Route Management Software
- 12.6.6.4 Scale Software
- 12.6.6.5 Recycling Software
- 12.6.6.6 Maintenance Software
- 12.6.6.7 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Waste Management Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Waste Management Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Waste Management Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Waste Management Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Wastebits
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 AMCS Group
- 18.4 TRUX
- 18.5 WAM Software, Inc.
- 18.6 Sequoia Waste Solutions
- 18.7 SEE Forge
- 18.8 Thoughtful Systems, Inc.
- 18.9 DesertMicro
- 18.10 SFS Chemical Safety
- 18.11 Delta Equipment Systems, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

