
Market Overview
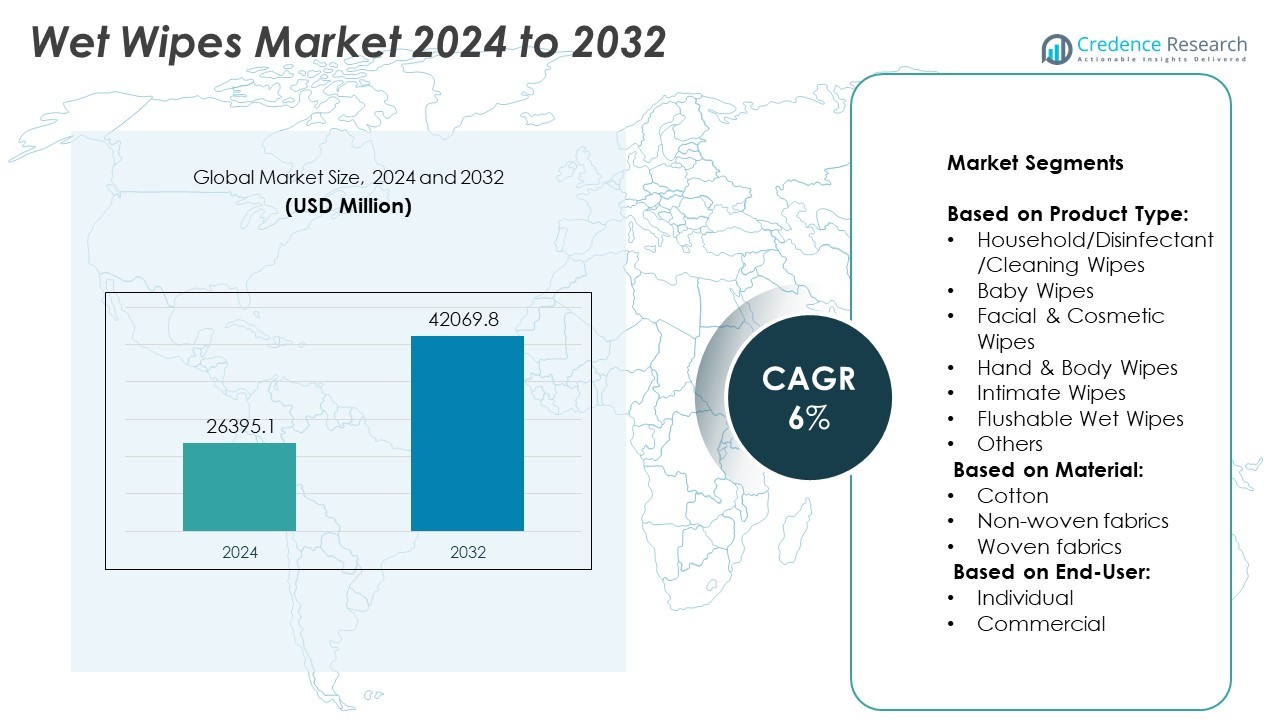
Wet Wipes Market size was valued at USD 26395.1 million in 2024 and is anticipated to reach USD 42069.8 million by 2032, at a CAGR of 6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wet Wipes Market Size 2024 | USD 26395.1 Million |
| Wet Wipes Market, CAGR | 6% |
| Wet Wipes Market Size 2032 | USD 42069.8 Million |
The Wet Wipes market advances through rising demand for convenient hygiene solutions, driven by urban lifestyles, health awareness, and expanding baby care needs. Consumers seek portable, skin-safe, and biodegradable products, pushing manufacturers to innovate in formulation and packaging. Growing adoption of disinfectant wipes in households and healthcare supports volume growth, while premium cosmetic and intimate wipes gain traction in developed markets. Trends favor natural ingredients, eco-friendly materials, and functional variants tailored for travel, sports, or beauty routines.
The Wet Wipes market shows strong presence in North America and Europe due to advanced hygiene standards, established retail infrastructure, and consumer preference for premium personal care products. Asia-Pacific emerges as a fast-growing region supported by urbanization and rising disposable incomes. Latin America and the Middle East & Africa offer gradual expansion opportunities through increased healthcare and household applications. Key players influencing global competition include Procter & Gamble, Kimberly-Clark, Unilever, and Johnson & Johnson, each leveraging strong brand portfolios and wide distribution networks.
Market Insights
- The Wet Wipes market was valued at USD 26,395.1 million in 2024 and is projected to reach USD 42,069.8 million by 2032, growing at a CAGR of 6% during the forecast period.
- Rising consumer focus on personal hygiene, convenient cleaning solutions, and baby care needs continues to drive product demand across multiple segments.
- Biodegradable wipes, natural ingredient formulations, and sustainable packaging dominate recent trends, with growing demand from eco-conscious consumers.
- Leading companies such as Procter & Gamble, Kimberly-Clark, and Unilever maintain competitive strength through product innovation and global distribution networks.
- Environmental regulations, concerns over sewer system clogging, and raw material price volatility act as key restraints in production and market expansion.
- North America leads the market due to high hygiene awareness and advanced retail infrastructure, while Asia-Pacific shows rapid growth through rising urbanization and income levels.
- Manufacturers continue to invest in e-commerce channels, subscription models, and region-specific product formats to reach diverse consumer bases efficiently.
Market Drivers
Rising Demand for Convenient Personal Hygiene Products Among Urban Consumers
The Wet Wipes market benefits from increased consumer preference for portable, disposable hygiene solutions. Urbanization and busy lifestyles push individuals to seek quick and effective alternatives to traditional cleaning methods. Wet wipes offer an on-the-go solution for facial cleansing, hand sanitization, and intimate care, meeting rising hygiene standards. Demand rises across age groups, particularly among working professionals and travelers. The market aligns with consumer habits that favor time-saving personal care formats. It responds to hygiene-conscious behavior influenced by pandemic-era health practices.
- For instance, Johnson & Johnson introduced its Cottontouch Baby Wipes made with 100% cotton and clinically proven to maintain skin pH, with over 12 million units sold globally in the first six months.
Expanding Infant and Baby Care Sector Driving Product Adoption
The Wet Wipes market experiences sustained growth through the baby care segment, where hygiene and skin safety remain primary concerns. Parents increasingly opt for dermatologically tested, fragrance-free wipes that protect sensitive skin. Major brands launch products with plant-based ingredients to meet natural care preferences. Baby wipes see consistent demand in hospitals, households, and daycare centers. It supports the market's expansion through high-volume, frequent-use consumer behavior. Growth in birth rates across emerging economies further strengthens product penetration.
- For instance, PDI Healthcare’s Super Sani-Cloth® Germicidal Disposable Wipe achieves broad-spectrum efficacy, verified to inactivate 34 different microorganisms-including SARS-CoV-2 and Candida auris-within a 2-minute contact time on hard, nonporous surfaces, according to its official product claims.
Healthcare and Medical Applications Enhancing Institutional Consumption
The Wet Wipes market gains traction in healthcare settings, where disinfectant and medical wipes play a vital role in infection control. Hospitals and clinics require sterile solutions for cleaning equipment, patient skin, and surfaces. It addresses the growing need for cross-contamination prevention and compliance with hygiene standards. Medical wipes infused with alcohol or chlorhexidine attract institutional buyers seeking effective antiseptic alternatives. The demand also extends to elderly care facilities, where adult incontinence wipes support both hygiene and dignity. This segment contributes significantly to bulk procurement and repeat usage.
Shift Toward Biodegradable and Sustainable Wipe Materials
The Wet Wipes market responds to environmental concerns by embracing biodegradable, plastic-free materials. Consumers show strong interest in flushable, compostable wipes that reduce landfill impact. Regulatory frameworks in Europe and North America promote the use of eco-labeled products. It encourages manufacturers to innovate with cellulose-based fibers and water-based formulations. Sustainability becomes a differentiating factor in brand positioning and retail shelf placement. Retailers and e-commerce platforms feature green-labeled wipes more prominently to align with consumer values.
Market Trends
Surge in Demand for Natural and Organic Ingredients in Wipe Formulations
The Wet Wipes market shows a strong shift toward plant-based and chemical-free ingredients to meet clean label demands. Consumers increasingly avoid wipes containing alcohol, parabens, and artificial fragrances due to skin sensitivity and long-term health concerns. Brands reformulate products with aloe vera, chamomile, coconut oil, and bamboo extracts to ensure gentler application. It reflects growing awareness of dermatological safety and environmental sustainability. Organic certification and dermatologist-tested labels play a larger role in influencing buyer choices. Product differentiation relies heavily on natural origin claims across retail and e-commerce platforms.
- For instance, Nivea launched its Biodegradable Cleansing Wipes made from 100% plant fibers and plastic-free materials, reaching over 2,500 retail locations across Europe, as stated in its official sustainability disclosures.
Growing Popularity of Functional Wipes with Specialized Applications
The Wet Wipes market trends toward multifunctional variants designed for specific needs such as makeup removal, surface disinfection, and fitness use. Brands launch niche formats like menthol-infused sports wipes or antibacterial wipes for public transportation hygiene. It addresses changing consumer routines that prioritize targeted utility in compact formats. Product innovation supports expansion into travel kits, gym bags, and school packs. Functional segmentation allows manufacturers to capture value across non-traditional personal care spaces. The market witnesses higher margins in premium, purpose-driven wipe categories.
- For instance, Clorox released its Scentiva Disinfecting Wipes infused with Tuscan Lavender & Jasmine, tested to kill 99.9% of bacteria and viruses, and distributed the product across more than 4,500 retail outlets across the U.S.
Rise of Sustainable Packaging and Plastic-Free Product Formats
The Wet Wipes market adapts to environmental mandates by embracing recyclable, refillable, and compostable packaging formats. Traditional plastic tubs and pouches are replaced with paper-based wrappers and biodegradable dispensers. It aligns with government regulations and retailer pressure to reduce single-use plastic waste. Consumer preference for eco-conscious brands supports investment in low-impact material technologies. Product labeling now emphasizes sustainability credentials, including FSC certification and water-based printing. Packaging innovations influence both brand perception and shelf appeal.
Expansion of Direct-to-Consumer and E-commerce Sales Channels
The Wet Wipes market embraces digital-first strategies to capitalize on growing online demand. Direct-to-consumer brands offer subscription-based delivery of personal and baby wipes to build customer retention. It benefits from detailed product filtering, reviews, and personalized hygiene bundles. E-commerce platforms enable rapid entry of emerging brands targeting niche preferences. Online promotions, influencer endorsements, and social media marketing amplify product visibility. The shift supports rapid innovation cycles and lower distribution costs compared to traditional retail channels.
Market Challenges Analysis
Environmental Concerns and Regulatory Pressure on Disposal Practices
The Wet Wipes market faces scrutiny due to its environmental impact, particularly concerning plastic content and non-biodegradable waste. Many conventional wipes contain synthetic fibers that contribute to sewer blockages and marine pollution. Governments and environmental groups intensify campaigns to ban or restrict non-flushable wipes. It must comply with evolving legislation in Europe and North America, which mandates clearer labeling and material disclosures. Brands incur higher production costs when shifting to biodegradable materials or gaining eco-certifications. These challenges affect pricing strategies and long-term supply chain planning.
Rising Raw Material Costs and Disruptions in Global Supply Chains
The Wet Wipes market encounters pressure from volatile raw material prices, particularly for nonwoven fabrics, resins, and packaging substrates. Increased demand for hygiene products during global health events amplifies pressure on manufacturing capacity. It struggles to balance cost-efficiency with consistent product quality across regional markets. Delays in logistics and sourcing, especially from Asia-Pacific suppliers, disrupt inventory planning and affect delivery timelines. Smaller players face higher risks of supply gaps due to limited procurement flexibility. These cost-related constraints reduce competitiveness and challenge sustained profitability.
Market Opportunities
Product Innovation in Biodegradable and Skin-Sensitive Wipe Solutions
The Wet Wipes market holds strong potential in developing biodegradable and dermatologically safe products that align with environmental and health-conscious preferences. Consumer interest in flushable, compostable, and plastic-free wipes opens opportunities for new material technologies. Brands can invest in cellulose-based fibers and plant-derived formulations to replace synthetic blends. It benefits from demand in baby care, feminine hygiene, and sensitive skin segments where safety and sustainability drive loyalty. Companies that secure eco-certifications and dermatological validations gain a competitive edge in regulated and premium markets. Product differentiation through skin-specific formulations and green packaging enhances shelf visibility and consumer trust.
Rising Penetration in Emerging Economies with Expanding Middle Class
The Wet Wipes market can expand rapidly in regions such as Southeast Asia, Latin America, and Africa, where hygiene awareness and disposable income continue to rise. Urbanization and lifestyle changes in these economies drive demand for affordable, accessible personal care products. It can tap into new retail partnerships, localized branding, and region-specific formats to reach underserved populations. Growth in modern retail infrastructure and mobile commerce supports brand outreach across rural and semi-urban areas. Manufacturers that adapt to price sensitivity and local preferences secure long-term volume gains. These markets offer strong growth potential across baby care, medical, and household cleaning segments.
Market Segmentation Analysis:
By Product Type:
Baby wipes account for a significant share due to consistent demand from households, maternity clinics, and childcare facilities. Parents prioritize safety, softness, and skin-friendliness, encouraging manufacturers to develop fragrance-free and hypoallergenic variants. Household/disinfectant/cleaning wipes gain traction in both residential and institutional cleaning routines where quick sanitation is required. Facial and cosmetic wipes expand through beauty retail channels, targeting makeup removal, skin hydration, and on-the-go freshness. The Wet Wipes market also sees growing demand for hand & body wipes, particularly in travel, fitness, and outdoor segments. Intimate wipes cater to niche health and hygiene needs, while flushable wet wipes offer convenience but face regulatory scrutiny in urban wastewater systems. Other variants include specialty wipes for pets, footwear, and automotive cleaning.
- For instance, PDI Healthcare Super Sani-Cloth wipes, a widely used disinfectant in hospitals, are supplied in high volume (over 500 million annually) and are known for their rapid efficacy against a broad range of pathogens. Specifically, they achieve a 2-minute kill time against over 30 pathogens, a claim validated through clinical lab testing. This rapid action is crucial for maintaining hygiene in fast-paced healthcare environments.
By Material:
Non-woven fabrics dominate due to their cost efficiency, absorbency, and adaptability across personal care and cleaning applications. It allows customization in terms of texture, strength, and softness, meeting diverse product performance needs. Cotton-based wipes appeal to environmentally conscious users who prefer biodegradable and skin-safe materials, particularly in premium baby and facial care lines. Woven fabrics offer higher strength and durability, making them suitable for heavy-duty cleaning and reusable wipe formats. Manufacturers focus on combining material sustainability with functional integrity to meet rising consumer expectations.
- For instance, Albaad Cotton-Like Eco Wipes are produced with certified 100% cotton fiber, achieving a breakdown time of under 60 days in industrial compostability trials and distributed across more than 20 European markets.
By End-User:
Individual consumers drive most of the Wet Wipes market volume, especially in personal hygiene and household maintenance. It aligns with lifestyle habits, self-care routines, and daily cleaning needs. Commercial usage expands steadily across healthcare, hospitality, foodservice, and transportation sectors. These environments require reliable, high-volume disinfecting and cleaning solutions that comply with hygiene regulations. Commercial segments present strong opportunities for recurring bulk orders and long-term supplier contracts.
Segments:
Based on Product Type:
- Household/Disinfectant/Cleaning Wipes
- Baby Wipes
- Facial & Cosmetic Wipes
- Hand & Body Wipes
- Intimate Wipes
- Flushable Wet Wipes
- Others
Based on Material:
- Cotton
- Non-woven fabrics
- Woven fabrics
Based on End-User:
- Individual
- Commercial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Wet Wipes market, accounting for 31.6% of global revenue in 2024. The region’s leadership is driven by high consumer awareness, advanced retail infrastructure, and demand for hygiene-focused personal care products. Baby wipes and disinfectant household wipes dominate usage due to established parenting practices, hospital protocols, and household cleaning standards. Consumers in the United States and Canada prioritize dermatologically tested, eco-labeled products, pushing manufacturers to innovate in sustainable packaging and biodegradable materials. It also benefits from strong online retail penetration, where brands offer subscription-based delivery and tailored product bundles. Institutional buyers, including healthcare and hospitality sectors, contribute to recurring demand across commercial end-user segments.
Europe
Europe represents the second-largest Wet Wipes market, contributing 28.4% of the global share. The region enforces strict environmental and product safety regulations that shape both product development and labeling. Demand for biodegradable, plastic-free, and flushable wipes continues to grow, driven by consumer preference and policy mandates under the EU Single-Use Plastics Directive. Countries such as Germany, France, and the UK lead in adopting natural fiber wipes, especially in baby care, intimate hygiene, and household cleaning categories. It also sees increasing demand for facial and cosmetic wipes from the region’s well-established skincare and beauty industries. Retailers across Europe focus on clean label transparency, prompting product reformulation and innovation in raw material sourcing.
Asia-Pacific
Asia-Pacific holds a significant growth position, currently representing 21.9% of the global Wet Wipes market. Rapid urbanization, population growth, and rising middle-class incomes in China, India, Indonesia, and Southeast Asia drive volume sales across both baby wipes and general-purpose hygiene wipes. It experiences strong uptake of household cleaning wipes and hand & body wipes due to lifestyle modernization and higher hygiene awareness, especially post-pandemic. E-commerce and organized retail sectors play a key role in expanding product access and awareness. Local and international manufacturers invest in affordable, multi-pack options tailored to regional preferences and price sensitivity. Governments promote public health campaigns, further supporting demand in institutional and healthcare settings.
Latin America
Latin America contributes 9.2% to the global Wet Wipes market, with Brazil and Mexico as the largest consumers. Regional demand centers around baby wipes, facial wipes, and general-purpose household variants, particularly in urban zones. It gains support from modern trade formats, including supermarkets and pharmacy chains, which offer private-label and economy-priced products. Manufacturers focus on improving distribution networks and adapting packaging sizes to suit varying income levels. Environmental awareness is rising, although sustainable wipe adoption remains limited to premium segments. Commercial applications in hospitality and public healthcare present steady opportunities for mid-sized suppliers.
Middle East & Africa
The Middle East & Africa region holds 8.9% of the Wet Wipes market, supported by growing hygiene awareness and urban expansion in Gulf Cooperation Council (GCC) countries and parts of North Africa. Baby wipes dominate consumption, particularly among high-income households, while facial and hand wipes gain momentum in retail and personal care channels. It shows potential in sectors such as hospitality, transportation, and healthcare where hygiene standards evolve. Religious tourism in countries like Saudi Arabia further increases short-term demand for portable hygiene products. Domestic manufacturing remains limited, prompting high reliance on imports across key product categories. Retailers promote smaller packaging formats for cost accessibility in lower-income areas.
Key Player Analysis
- Nice-Pak Products
- Kimberly-Clark
- Estee Lauder
- Beiersdorf
- Reckitt Benckiser
- Sani Professional
- Unilever
- Cascades
- PDI
- Johnson & Johnson
- Seventh Generation
- Clorox
- Procter & Gamble
- Kirkland Signature
- Essity
Competitive Analysis
The Wet Wipes market features strong competition among leading players including Nice-Pak Products, Kimberly-Clark, Estee Lauder, Beiersdorf, Reckitt Benckiser, Sani Professional, Unilever, Cascades, PDI, Johnson & Johnson, Seventh Generation, Clorox, Procter & Gamble, Kirkland Signature, and Essity.These companies compete on innovation, sustainability, pricing strategies, and product range diversification. Leading brands invest in biodegradable materials, skin-safe formulations, and recyclable packaging to address growing environmental concerns and regulatory demands. They maintain strong distribution networks across supermarkets, pharmacies, and e-commerce platforms, ensuring high product availability and visibility. Several players focus on specialized segments such as baby care, cosmetic wipes, and disinfectant formats to secure consumer loyalty. R&D investment enables continuous development of dermatologically tested and multi-functional products, appealing to both individual and institutional buyers. Manufacturers adopt regional branding strategies and promotional campaigns to align with cultural preferences and regulatory standards. Competitive advantage also stems from private-label partnerships and healthcare sector contracts, especially in North America and Europe. Market leaders leverage digital marketing and subscription models to build direct-to-consumer engagement, expanding recurring revenue streams.
Recent Developments
- In April 2025, Essity reported a 0.4% increase in net sales compared to a year earlier, amounting to SEK 34,976 million in the first quarter. Organic sales grew by 2.1%, with strong gains in Health & Medical and Consumer Goods segments.
- In February 2023, The Honest Company, Inc. released its Clean Conscious Wipes. This mild cleaner makes these compostable wipes safe for sensitive skin. They are also made plastic-free, quaternary-free, perfume-free, chlorine-free processing, and parabens-free
- In June 2023 US-based plastic packaging products manufacturer Berry Global Inc launched its new wipes materials for hard-surface disinfecting, sustainable range.
Market Concentration & Characteristics
The Wet Wipes market shows moderate concentration, with a mix of multinational corporations and specialized regional players shaping competitive dynamics. Leading companies such as Procter & Gamble, Kimberly-Clark, and Unilever hold strong brand equity, advanced distribution networks, and consistent R&D capabilities. It features product diversity across personal care, household cleaning, healthcare, and cosmetic segments, supported by continuous innovation in formulation and packaging. Market characteristics include high volume turnover, price sensitivity in emerging regions, and premiumization trends in developed economies. Sustainability expectations influence product development, with biodegradable materials and recyclable packaging becoming standard in new launches. Consumer demand fluctuates by application, with baby wipes maintaining consistent use, while disinfectant and facial wipes respond to seasonal and health-driven demand. Manufacturers prioritize dermatological safety, environmental compliance, and convenience features such as resealable packs and multi-use formats. The market supports private label expansion, particularly through supermarkets and e-commerce platforms targeting budget-conscious consumers.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biodegradable and plastic-free wet wipes will continue to rise due to stricter environmental regulations and consumer awareness.
- Baby wipes will remain a stable revenue segment driven by consistent global birth rates and hygiene priorities.
- Growth in disinfectant and antibacterial wipes will sustain due to ongoing focus on public health and sanitation standards.
- Manufacturers will expand product portfolios with skin-sensitive, pH-balanced, and dermatologically tested formulations.
- E-commerce and direct-to-consumer sales will grow rapidly, supported by subscription models and digital marketing.
- Emerging markets will offer high growth potential with increasing urbanization, disposable income, and hygiene education.
- Premiumization will drive demand for specialty wipes, including organic, cosmetic, and fitness-focused variants.
- Innovation in packaging will focus on resealable, recyclable, and travel-friendly formats to enhance usability and reduce waste.
- Institutional demand from healthcare, hospitality, and transportation sectors will support commercial product lines.
- Private label brands will gain traction by offering competitive pricing and customized regional assortments.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Busy Lifestyles
Increasing urban populations and fast-paced lifestyles are driving demand for convenient, portable hygiene solutions such as wet wipes, as consumers seek quick alternatives to traditional cleaning methods.
Expansion of Baby Care and Infant Hygiene
Consistent global birth rates and heightened parental focus on skin safety and hygiene are fueling steady demand for baby wipes, especially those with natural and dermatologically tested formulations.
Healthcare and Institutional Adoption
Hospitals, clinics, and elderly care facilities are increasingly using disinfectant and medical wipes for infection control and hygiene compliance, supporting bulk procurement and repeat usage in the commercial segment.
Shift Toward Biodegradable and Sustainable Products
Rising environmental awareness and stricter regulations are pushing manufacturers to innovate with biodegradable materials and eco-friendly packaging, attracting eco-conscious consumers and meeting regulatory requirements.
Growth of E-commerce and Direct-to-Consumer Channels
The proliferation of online retail and subscription models is making wet wipes more accessible, enabling brands to reach diverse consumer bases efficiently and respond quickly to changing preferences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wet Wipes market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wet Wipes Market projected to grow between 2025 and 2032?
Which Wet Wipes market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wet Wipes market?
Who are the leading companies in the Wet Wipes Market?
Which region commanded the largest share of the Wet Wipes market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Individual
- 1.2.2 Commercial
- 1.3 By Material
- 1.3.1 Cotton
- 1.3.2 Non-woven fabrics
- 1.3.3 Woven fabrics
- 1.4 By Product Type
- 1.4.1 Household/Disinfectant/Cleaning Wipes
- 1.4.2 Baby Wipes
- 1.4.3 Facial & Cosmetic Wipes
- 1.4.4 Hand & Body Wipes
- 1.4.5 Intimate Wipes
- 1.4.6 Flushable Wet Wipes
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 26,395.1 million → 2032: USD 42,069.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wet Wipes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wet Wipes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wet Wipes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wet Wipes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wet Wipes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wet Wipes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wet Wipes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wet Wipes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 26,395.1 million → 2032: USD 42,069.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wet Wipes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Individual
- 12.3.7.2 Commercial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cotton
- 12.4.7.2 Non-woven fabrics
- 12.4.7.3 Woven fabrics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Household/Disinfectant/Cleaning Wipes
- 12.5.7.2 Baby Wipes
- 12.5.7.3 Facial & Cosmetic Wipes
- 12.5.7.4 Hand & Body Wipes
- 12.5.7.5 Intimate Wipes
- 12.5.7.6 Flushable Wet Wipes
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wet Wipes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wet Wipes Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wet Wipes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wet Wipes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Procter & Gamble
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kimberly-Clark
- 18.4 Unilever
- 18.5 Johnson & Johnson
- 18.6 Clorox
- 18.7 Essity
- 18.8 Nice-Pak Products
- 18.9 Beiersdorf
- 18.10 Reckitt Benckiser
- 18.11 PDI
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

