
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Animal Feed Enzymes Market Size 2024 | USD 1,200.5 million |
| Animal Feed Enzymes Market, CAGR | 5.69% |
| Animal Feed Enzymes MarketSize 2032 | USD 1,861.1 million |
Market Overview
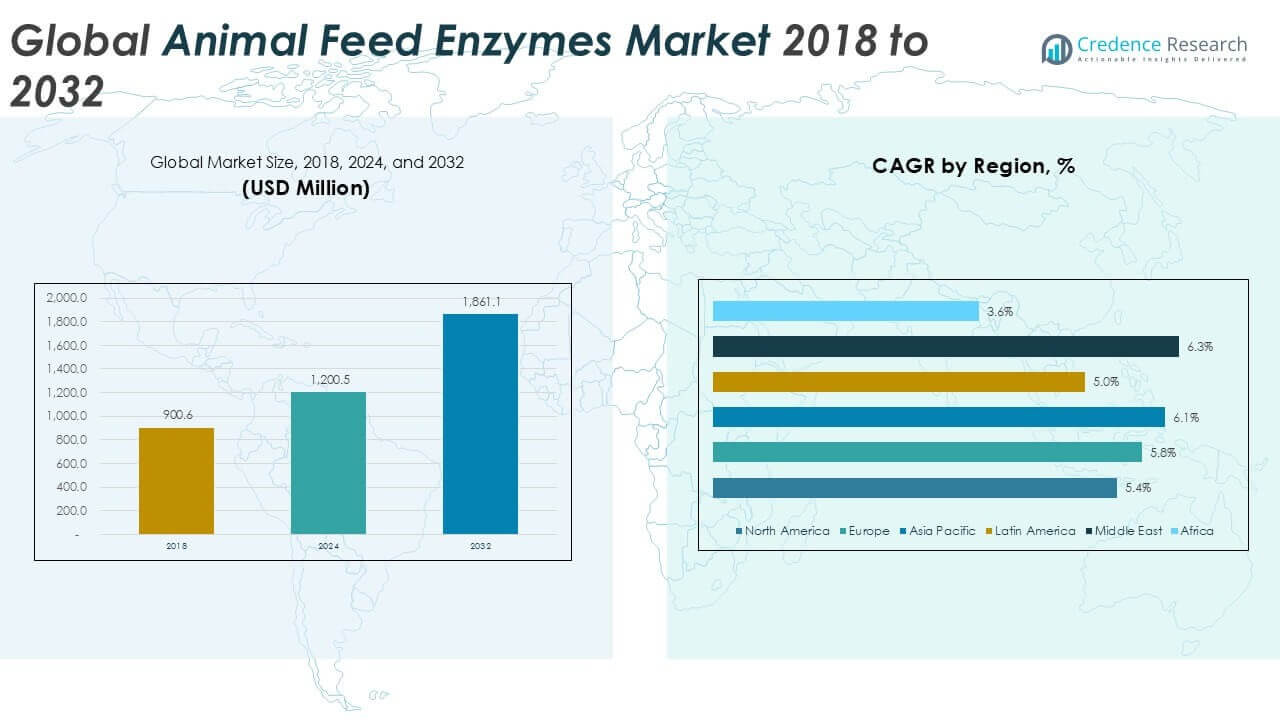
The Global Animal Feed Enzymes Market is projected to grow from USD 1,200.5 million in 2024 to an estimated USD 1,861.1 million by 2032, with a compound annual growth rate (CAGR) of 5.69% from 2025 to 2032.
One of the key drivers for this market is the rising focus on sustainable livestock production and reducing the environmental impact of animal farming. Enzymes such as phytase, protease, and carbohydrase help optimize feed utilization and reduce phosphorus and nitrogen emissions. Trends indicate a growing preference for enzyme blends tailored to specific species and feed formulations. Furthermore, increasing consumer awareness regarding meat quality and food safety is encouraging producers to adopt enzyme-based solutions that enhance gut health and immunity, thereby minimizing antibiotic use. Technological advancements in enzyme formulation and delivery mechanisms are also supporting market growth.
Geographically, Asia Pacific dominates the animal feed enzymes market due to the large-scale livestock industry in countries like China, India, and Vietnam. North America and Europe follow closely, driven by stringent regulations on animal nutrition and the push for antibiotic alternatives. Key players operating in the global market include BASF SE, DSM Nutritional Products, Novozymes A/S, DuPont de Nemours Inc., and Adisseo, all actively involved in expanding their product portfolios and regional presence.
Market Insights
- The Global Animal Feed Enzymes Market is set to grow from USD 1,200.5 million in 2024 to USD 1,861.1 million by 2032, at a CAGR of 5.69%.
- Rising demand for high-efficiency animal nutrition and cost-effective feed solutions continues to drive enzyme adoption across livestock sectors.
- Growing focus on sustainable farming practices and reduced environmental impact boosts demand for enzymes like phytase and protease.
- Shift toward antibiotic-free feed solutions increases enzyme usage to support gut health and animal immunity.
- Inconsistent regulatory frameworks across regions and lengthy product approval processes restrict market entry and innovation.
- Limited awareness among small-scale farmers and lack of access to technical knowledge hinder broader adoption in developing regions.
- Asia Pacific dominates the global market with over 36% share in 2024, followed by Europe and North America, driven by large-scale livestock production and regulatory support.
Market Drivers
Rising Demand for Cost-Effective and Nutrient-Efficient Animal Feed Solutions
The Global Animal Feed Enzymes Market is witnessing growth due to the need for more efficient and economical livestock feeding practices. Feed enzymes such as phytase, protease, and carbohydrase help break down complex nutrients, allowing animals to absorb essential proteins and minerals more effectively. It helps reduce feed waste and improves the overall feed conversion ratio. With rising prices of conventional feed ingredients like corn and soybean, livestock producers seek enzyme-based alternatives to optimize nutritional value and reduce overall feed costs. The industry benefits from growing commercial livestock farming, which prioritizes high-performance feed inputs. This shift drives consistent demand for tailored enzyme formulations suited to specific animal species and diets.
- For instance, in 2024, the global commercial livestock population reached approximately 25 billion animals, driving demand for enzyme-based feed solutions.
Global Push for Sustainable Livestock Production and Environmental Compliance
Sustainability and environmental regulations are becoming critical factors in shaping the Global Animal Feed Enzymes Market. Enzymes play a vital role in reducing the ecological footprint of livestock farming by lowering phosphorus and nitrogen emissions. It supports compliance with stringent global regulations aimed at controlling nutrient runoffs and greenhouse gas emissions. Countries in the European Union and parts of North America enforce strict standards for livestock waste management, encouraging the use of enzyme-enhanced feed. Sustainability goals in corporate livestock operations further drive enzyme adoption. This trend aligns with broader environmental commitments and industry efforts to improve production efficiency while minimizing environmental harm.
- For instance, in 2023, over 15,000 livestock farms in the European Union adopted enzyme-enhanced feed to comply with environmental regulations.
Increasing Demand for Antibiotic Alternatives in Animal Nutrition
The restriction on antibiotic growth promoters in animal feed across several regions has opened new avenues for the Global Animal Feed Enzymes Market. Consumers and regulators push for safer and more natural feed solutions that maintain animal health and productivity. It leads to the adoption of enzymes that enhance gut health, digestion, and immunity without the need for antibiotics. This shift is particularly strong in developed markets where food safety concerns and consumer preferences influence production choices. Enzymes offer a viable solution to maintain performance levels in livestock while meeting new regulatory norms. Their role in promoting gut microflora balance and nutrient availability strengthens their market position.
Technological Innovations in Enzyme Formulation and Delivery Systems
Advancements in biotechnology and enzyme delivery systems support the evolving needs of the Global Animal Feed Enzymes Market. Producers now develop enzyme blends that target specific nutritional challenges in different animal species. It allows precise application and improved enzyme stability during feed processing and digestion. Microencapsulation and thermostable enzyme technologies improve enzyme survivability and efficiency under varying feed manufacturing conditions. These innovations increase the effectiveness of feed enzymes in commercial settings. Research partnerships between feed producers and biotech firms also accelerate innovation pipelines. Enhanced performance and ease of application make modern enzyme products more attractive to feed manufacturers worldwide.
Market Trends
Expansion of Species-Specific and Customized Enzyme Blends
Manufacturers are focusing on species-specific enzyme formulations to address the unique digestive needs of poultry, swine, ruminants, and aquaculture. This trend is reshaping the Global Animal Feed Enzymes Market by offering precision nutrition tailored to each animal group. It allows producers to achieve better feed efficiency and growth performance. Customized enzyme blends improve digestibility of target feed components, reducing nutrient loss and enhancing feed conversion rates. Companies invest in R\&D to design solutions compatible with regional feed ingredients and livestock practices. This approach enables product differentiation and stronger market penetration across diverse geographies.
- For instance, Novozymes and DSM together launched more than 40 new animal feed enzyme products between 2017 and 2023, many of which are customized for specific species such as poultry and swine, reflecting the industry's commitment to targeted enzyme solutions.
Increased Adoption of Thermostable and pH-Resistant Enzymes
Thermostable and pH-resistant enzyme technologies are gaining traction across the animal feed industry. These innovations help enzymes withstand high temperatures during pelleting and remain active in varying pH conditions in the animal gut. The Global Animal Feed Enzymes Market benefits from this trend as feed manufacturers demand solutions that ensure consistent performance. It improves enzyme efficiency throughout feed processing and digestion. Companies continue to introduce next-generation enzyme variants with higher stability and longer shelf life. These advancements support product reliability and operational efficiency for feed producers.
- For instance, in 2023, AB Enzymes reported commercializing more than 15 million tons of animal feed globally that incorporated their thermostable enzyme blends, designed specifically to retain efficacy during high-temperature feed-pelleting processes.
Integration of Enzymes into Antibiotic-Free Feed Programs
The shift toward antibiotic-free animal production is strengthening demand for enzyme-based solutions that support animal health and performance. The Global Animal Feed Enzymes Market sees greater interest in products that enhance gut microbiota and nutrient absorption without synthetic additives. It aligns with consumer preferences for natural and residue-free meat and dairy products. Enzymes now form a core part of integrated gut health strategies alongside probiotics and organic acids. Feed manufacturers reformulate products to meet clean-label standards while maintaining efficiency. This trend is especially strong in Europe, North America, and parts of Asia.
Emergence of Digital Tools for Feed Optimization and Enzyme Application
Digitalization is influencing enzyme usage by improving formulation precision and feed monitoring. Advanced software tools enable real-time nutrient profiling and enzyme dosage adjustments based on animal age, health, and feed composition. It supports better decision-making and reduces overuse of feed additives. The Global Animal Feed Enzymes Market benefits from data-driven approaches that enhance product performance and reduce feed costs. Companies integrate enzyme products with digital platforms to offer complete nutritional solutions. This trend reflects a broader move toward smart livestock management and precision farming.
Market Challenges
Regulatory Variability and Lack of Uniform Standards Across Regions
The Global Animal Feed Enzymes Market faces challenges due to inconsistent regulatory frameworks across major markets. Approval processes and usage guidelines for feed enzymes vary significantly between regions, creating barriers for global manufacturers. It delays product launches and complicates compliance strategies for companies operating in multiple countries. Stringent safety assessments and long authorization timelines in the EU, for example, can hinder innovation and market entry. These regulatory hurdles increase costs and limit the availability of advanced enzyme products in certain markets. Companies must invest heavily in legal and scientific resources to navigate complex and evolving regulations.
- For instance, in 2024, the average authorization time for new feed enzyme products in the European Union reached 540 days, with companies investing approximately 12 million US dollars in legal and scientific resources to secure product approval.
Limited Awareness and Technical Knowledge Among End Users
Low awareness of enzyme benefits and limited technical expertise among small and medium-sized livestock producers pose a major challenge. Many farmers lack access to reliable information on enzyme usage and dosage optimization. The Global Animal Feed Enzymes Market experiences slower adoption in developing regions where traditional feeding practices still dominate. It creates a knowledge gap that reduces the effectiveness of enzyme-based nutrition. Inadequate extension services and limited access to training further restrict widespread usage. Addressing this challenge requires targeted educational initiatives and stronger collaboration between feed companies and agricultural stakeholders.
Market Opportunities
Expansion of Enzyme Use in Emerging Livestock Markets
Rising demand for animal protein in emerging economies presents a strong growth opportunity for the Global Animal Feed Enzymes Market. Rapid urbanization, population growth, and income increases drive meat and dairy consumption in Asia, Latin America, and Africa. It creates a favorable environment for modern feed practices and enzyme adoption. Governments and private investors are improving livestock infrastructure and supporting feed industry development. These regions offer untapped potential for enzyme manufacturers to expand distribution and educate producers. Strategic partnerships with local feed producers can help accelerate adoption and increase market penetration.
Innovation in Enzyme Combinations and Functional Additives
Advances in enzyme technology create new opportunities to offer multifunctional feed solutions. Combining enzymes with probiotics, organic acids, or immune-supporting additives can deliver comprehensive animal nutrition benefits. The Global Animal Feed Enzymes Market can capitalize on this trend by offering integrated solutions that meet complex nutritional and health needs. It allows manufacturers to differentiate their products and offer higher value to feed producers. The growing demand for clean-label and antibiotic-free products further boosts the relevance of innovative enzyme combinations. Investment in R\&D and product customization will unlock new growth areas for both global and regional players.
Market Segmentation Analysis
By Type
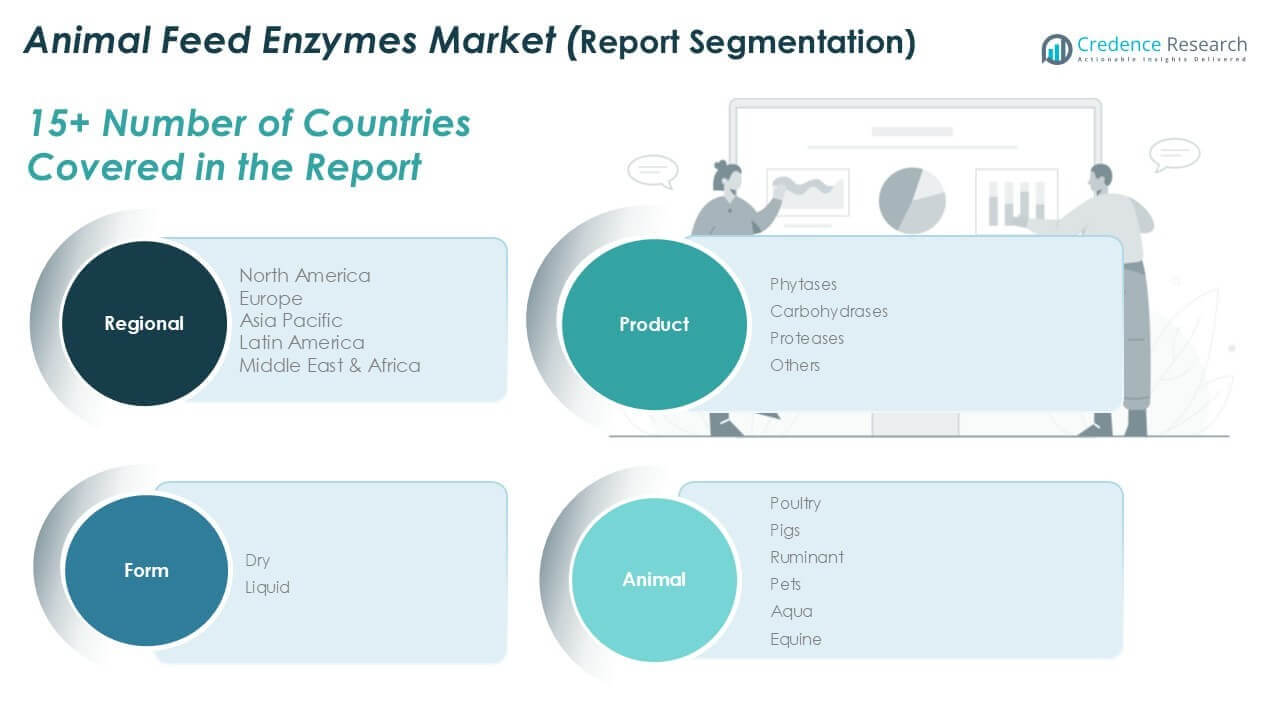
The Global Animal Feed Enzymes Market is segmented by type into phytases, carbohydrases, proteases, and others. Phytases hold a significant revenue share due to their ability to enhance phosphorus availability in plant-based feeds. It helps reduce the need for inorganic phosphate supplements, making feed more cost-efficient and environmentally sustainable. Carbohydrases, including amylase and xylanase, play a key role in breaking down complex carbohydrates, improving energy utilization. Proteases support protein digestion and are gaining traction in high-protein diets. The others segment includes lipases and other niche enzymes used in specialty feeds. Growing demand for multi-enzyme formulations continues to influence product innovation across this segment.
- For instance, company disclosures from leading animal nutrition firms indicate that global phytase enzyme production reached approximately 45,000 metric tons in 2023, underscoring its prominence in feed formulations.
By Form
By form, the market is classified into dry and liquid enzymes. Dry enzymes dominate the segment due to their longer shelf life, ease of handling, and compatibility with feed manufacturing processes such as pelleting. It offers stability during storage and transport, making it preferred in large-scale operations. Liquid enzymes, though less prevalent, are gaining interest due to their fast dispersion and high solubility in certain applications. These are often used in precision feeding systems and smaller farms requiring flexible formulations. Form selection depends on feed type, processing conditions, and end-user preferences across regions.
- For instance, government export data show that over 80,000 metric tons of dry animal feed enzymes were shipped globally in 2023, highlighting the dominance of this form in commercial feed supply chains
By Animal
The Global Animal Feed Enzymes Market is divided by animal type into poultry, pigs, ruminants, pets, aqua, and equine. Poultry holds the largest revenue share due to its high feed consumption and short production cycles. It creates strong demand for enzyme supplementation to improve feed efficiency and growth rates. Pigs follow as another key segment, where enzymes enhance protein and energy digestibility. Ruminants, including cattle and sheep, use enzymes to improve fiber digestion. The aqua segment is growing due to increased focus on sustainable fish and shrimp farming. Pets and equine represent smaller but emerging markets for specialty enzyme-based nutrition.
Segments
Based on Type
- Phytases
- Carbohydrases
- Proteases
- Others
Based on Form
- Dry
- Liquid
Based on Animal
- Poultry
- Pigs
- Ruminant
- Pets
- Aqua
- Equine
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Animal Feed Enzymes Market
The North America Animal Feed Enzymes Market was valued at USD 195.93 million in 2024 and is projected to reach USD 297.77 million by 2032, growing at a CAGR of 5.4%. It holds approximately 16.3% of the global market share. The demand is driven by the strong presence of commercial livestock farms in the U.S. and Canada, which prioritize high-efficiency feed additives. It also benefits from regulatory support encouraging reduced use of antibiotics in feed. Poultry and swine production remain key sectors adopting enzyme solutions. Advanced feed processing technologies and the presence of major feed manufacturers support consistent market growth.
Europe Animal Feed Enzymes Market
Europe’s Animal Feed Enzymes Market accounted for USD 262.61 million in 2024 and is expected to reach USD 409.43 million by 2032, expanding at a CAGR of 5.8%. It represents about 21.9% of the global market. Countries such as Germany, France, and the Netherlands drive enzyme adoption through strict regulations on feed safety and environmental compliance. The market benefits from strong demand for antibiotic-free meat and a well-established commercial feed sector. It shows consistent growth in enzyme usage across poultry and swine applications. The presence of leading global enzyme producers further strengthens the regional supply chain.
Asia Pacific Animal Feed Enzymes Market
The Asia Pacific Animal Feed Enzymes Market stood at USD 431.23 million in 2024 and is projected to reach USD 688.59 million by 2032, with a CAGR of 6.1%. It commands the largest regional share at 36.4% of the global market. Rapid growth in livestock production, especially in China, India, and Southeast Asia, fuels enzyme demand. Feed manufacturers seek cost-effective solutions to improve feed conversion and reduce input costs. It also reflects growing awareness of feed efficiency and sustainable practices. Expansion in aquaculture and poultry sectors boosts regional market opportunities.
Latin America Animal Feed Enzymes Market
Latin America’s Animal Feed Enzymes Market was valued at USD 101.19 million in 2024 and is projected to reach USD 148.89 million by 2032, growing at a CAGR of 5.0%. The region contributes around 8.5% to the global market. Brazil and Mexico lead enzyme adoption due to their growing livestock and poultry industries. Producers focus on improving animal health and reducing feed waste through enzyme supplementation. It remains a developing market with increasing demand for modern feed solutions. Government incentives for sustainable agriculture support the shift toward enzyme-based nutrition.
Middle East Animal Feed Enzymes Market
The Middle East Animal Feed Enzymes Market reached USD 132.52 million in 2024 and is anticipated to grow to USD 214.58 million by 2032, registering the highest CAGR among all regions at 6.3%. It accounts for about 7.1% of the global market. Countries such as Saudi Arabia and the UAE invest heavily in livestock modernization and feed efficiency. It sees rising interest in enzymes due to limited arable land and the need for optimal feed utilization. Import-dependent feed industries are turning to enzymes to boost nutritional efficiency. Growth is also supported by expanding poultry operations and national food security strategies.
Africa Animal Feed Enzymes Market
Africa’s Animal Feed Enzymes Market was valued at USD 77.06 million in 2024 and is projected to reach USD 101.80 million by 2032, growing at a CAGR of 3.6%. The region holds the smallest share of the global market at approximately 4.1%. Limited infrastructure and low awareness hinder enzyme adoption in many parts of the continent. However, South Africa and Egypt show rising interest in enzyme-based feed to improve livestock productivity. It remains a largely untapped market with long-term growth potential. International development programs and knowledge transfer initiatives may accelerate enzyme adoption in the coming years.
Key players
- AB Enzymes
- BASF SE
- Adisseo France SAS
- Alltech Inc.
- Associated British Foods PLC
- Azelis Holdings SA
- Bio-Cat
- Novus International, Inc
- DSM NV
- Elanco Animal Health
- Kerry Group
- Antozyme Biotech
Competitive Analysis
The Global Animal Feed Enzymes Market is characterized by the presence of several established players with diverse product portfolios and strong distribution networks. Companies such as BASF SE, DSM NV, and Adisseo France SAS lead the market through continuous innovation, partnerships, and expansion in high-growth regions. It reflects a balanced mix of multinational corporations and specialized biotechnology firms competing on technological capabilities and cost efficiency. Players like AB Enzymes and Alltech Inc. focus on species-specific solutions and sustainable feed alternatives. New entrants face high barriers due to regulatory complexities and the need for advanced R\&D infrastructure. Strategic mergers, acquisitions, and product diversification continue to shape the competitive landscape.
Recent Developments
- In March 2025, AB Enzymes unveiled a refreshed corporate design to solidify its image as a complete enzyme supplier, following its global expansion and integration with Roal Oy. This rebranding effort reflects the company's growth, expertise, and commitment to innovation. The alignment with Roal Oy, which became AB Enzymes Finland Oy in September 2024, further strengthens AB Enzymes' position in the market.
- In Q1 2025, Adisseo reported a 7% increase in specialty feed revenue and a 5% rise in gross profit, supported by strong performance from its enzyme products like Selisseo® and feed digestibility enhancers.
Market Concentration and Characteristics
The Global Animal Feed Enzymes Market exhibits moderate to high market concentration, with a few major players holding a significant share. It features a competitive environment shaped by innovation, regulatory compliance, and species-specific product development. Companies compete on the basis of enzyme efficacy, product stability, and compatibility with diverse feed formulations. The market favors firms with strong R&D capabilities and established relationships with feed manufacturers and livestock producers. It remains dynamic, with ongoing investments in biotechnology and tailored enzyme blends driving differentiation. Entry barriers include regulatory approvals, technological expertise, and distribution infrastructure, which limit the number of new entrants.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, Animal and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Governments and producers will prioritize enzyme-based solutions to reduce environmental impact and meet global sustainability goals in animal agriculture.
- Countries in Asia Pacific, Latin America, and the Middle East will drive growth as commercial livestock operations adopt modern feed technologies to boost efficiency.
- Enzymes will gain greater importance in antibiotic-free feed programs by improving gut health, nutrient absorption, and animal performance naturally.
- Future products will feature improved thermal stability, pH resistance, and species-specific action, enhancing enzyme efficiency in diverse feed processing environments.
- Digital platforms will support precise enzyme dosing and performance monitoring, helping producers optimize formulations based on real-time animal data.
- The enzyme market will expand into non-traditional segments like aquaculture and pet food, where digestibility and nutrient optimization remain critical.
- Major companies will continue forming alliances with feed producers, research institutions, and tech firms to accelerate product development and market penetration.
- Manufacturers will adapt to evolving global regulations by investing in compliant enzyme solutions, supported by robust documentation and product traceability.
- End-consumers will influence upstream practices, encouraging enzyme use to reduce chemical residues and support transparency in meat and dairy production.
- Ongoing research in enzyme engineering and microbiology will drive the development of next-generation enzymes tailored to complex feed matrices and evolving market needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Animal Feed Enzymes Market in 2023 and what is its forecast for 2032?
Which enzyme types are most commonly used in animal feed?
Which region currently dominates the global animal feed enzymes market?
Who are the major players in the animal feed enzymes industry?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Animal Feed Enzymes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Animal Feed Enzymes Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: NULL → forecast year: NULL)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Animal Feed Enzymes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Animal Feed Enzymes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Animal Feed Enzymes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Animal Feed Enzymes Market Drivers
- 3.3 Animal Feed Enzymes Market Restraints & Challenges
- 3.4 Animal Feed Enzymes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Animal Feed Enzymes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Animal Feed Enzymes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Animal Feed Enzymes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Animal Feed Enzymes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Animal Feed Enzymes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Animal Feed Enzymes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Animal Feed Enzymes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Animal Feed Enzymes Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Animal Feed Enzymes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Animal Feed Enzymes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Animal Feed Enzymes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Animal Feed Enzymes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Animal Feed Enzymes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Animal Feed Enzymes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Animal Feed Enzymes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Animal Feed Enzymes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Animal Feed Enzymes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Animal Feed Enzymes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Animal Feed Enzymes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
