
Market overview
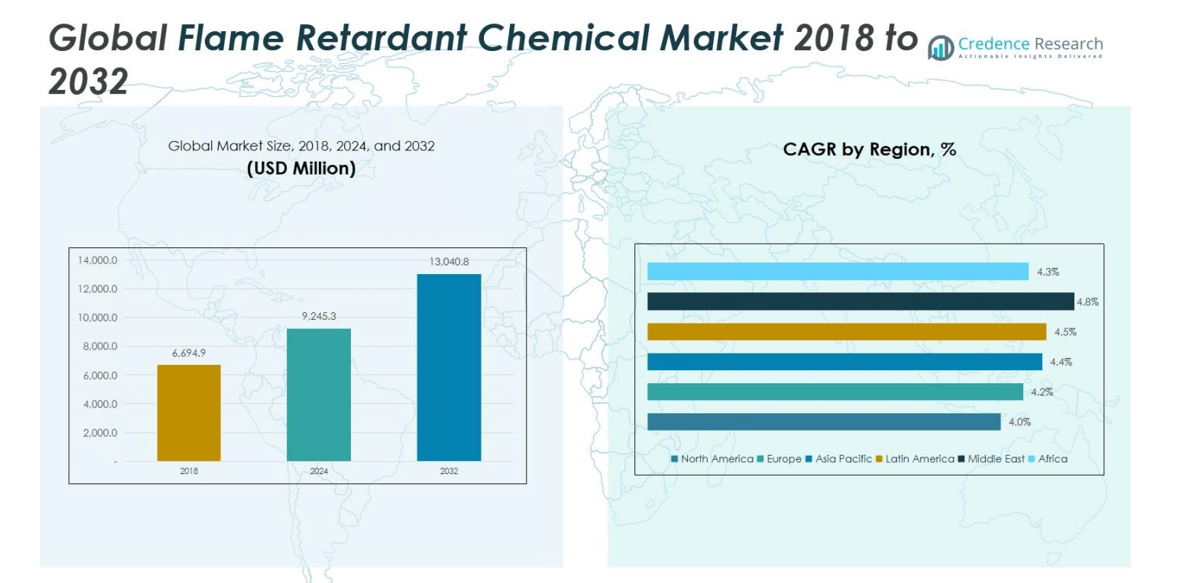
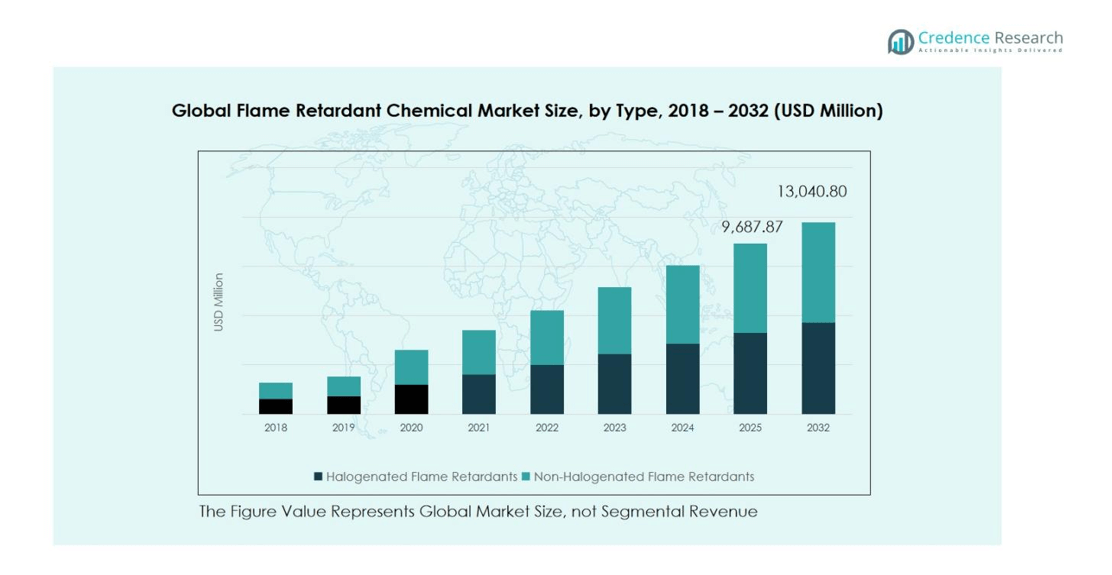
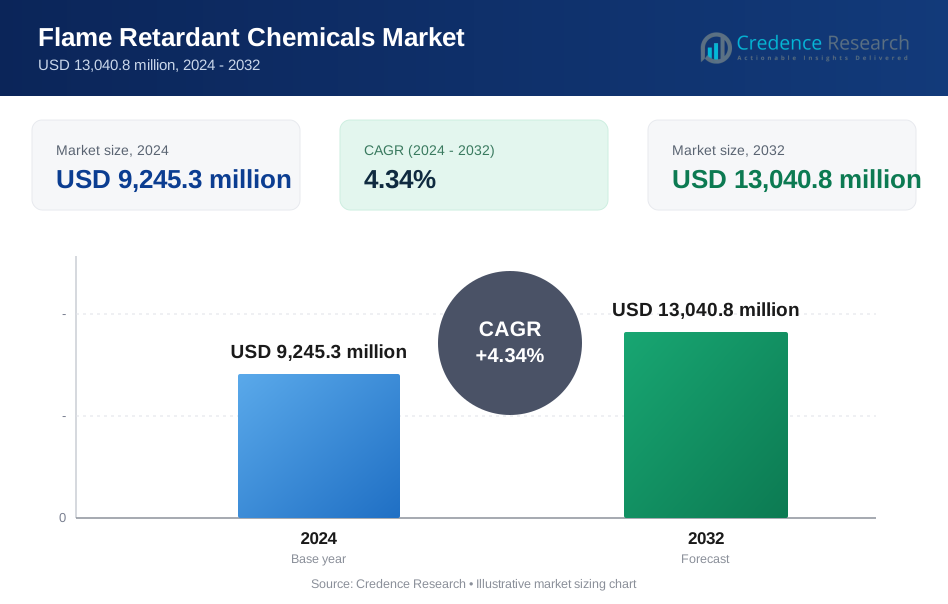
The Global Flame Retardant Chemical Market was valued at USD 6,694.9 million in 2018, growing to USD 9,245.3 million in 2024. It is anticipated to reach USD 13,040.8 million by 2032, at a CAGR of 4.34% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Flame Retardant Chemical Market Size 2024 | USD 9,245.3 million |
| Flame Retardant Chemical Market, CAGR | 4.34% |
| Flame Retardant Chemical Market Size 2032 | USD 13,040.8 million |
The Global Flame Retardant Chemical Market is dominated by key players such as BASF, Albemarle Corporation, Dow Inc., LANXESS AG, and ICL Group, which collectively hold a substantial share of the market. These companies leverage their extensive portfolios, cutting-edge research, and strong regional presence to maintain leadership. BASF and Albemarle are particularly prominent in the non-halogenated flame retardant segment, offering innovative solutions that cater to evolving fire safety standards. In terms of regional leadership, Asia Pacific holds the largest market share at 37.8% in 2024, driven by rapid industrialization and growing demand in sectors like electronics and construction. Europe follows closely with a share of 21.2%, while North America captures 16.8% of the global market, bolstered by stringent fire safety regulations and high demand from automotive and electronics industries. The market continues to expand as demand for sustainable and effective flame retardants grows globally.
Market Insights
- The Global Flame Retardant Chemical Market was valued at USD 6,694.9 million in 2018, projected to reach USD 9,245.3 million by 2024 and USD 13,040.8 million by 2032, growing at a CAGR of 4.34%.
- Key drivers of market growth include increasing fire safety regulations, particularly in construction and automotive industries, and rising demand for electronics and electric vehicles, which require flame-resistant materials.
- Non-halogenated flame retardants, especially aluminum hydroxide and magnesium hydroxide, dominate the market, holding 5% of the share in 2024, as they align with sustainability trends and regulatory requirements.
- The market faces challenges due to high costs of advanced flame retardants and increasing pressure from environmental regulations, particularly for halogenated flame retardants.
- Asia Pacific leads the market with 8% share in 2024, driven by rapid industrialization, while Europe holds 21.2% and North America accounts for 16.8%.
Market Segmentation Analysis:
By Type
The non‑halogenated flame retardants segment dominates the global market, commanding 62.5% of the share in 2024. This dominance is driven by rising regulatory pressure against halogen‑based compounds and greater uptake of environmentally benign alternatives such as aluminium hydroxide and magnesium hydroxide. Among sub‑types, aluminium hydroxide remains the leading sub‑segment owing to its cost‑effectiveness and excellent smoke suppression properties. Meanwhile, halogenated flame retardants hold the remaining 37.5%, but face headwinds from health and environmental concerns which are prompting a gradual shift toward non‑halogenated forms.
- For instance, Clariant’s Exolit AP series, based on ammonium polyphosphate, is widely used in thermoplastics and coatings to meet stringent EU REACH and RoHS standards.
By Application
In the application dimension, the polyolefins segment leads with about 25.8% of the global flame‑retardant market in 2024. This segment benefits from the extensive use of polyethylene and polypropylene in wires, cables, automotive interiors and roofing materials, where flame safety is paramount. Epoxy resins rank as a strong sub‑segment, holding an estimated 26.8% share and growing steadily thanks to demand for high‑performance composites and coatings in construction, electronics and aerospace. PVC and other polymers trail behind but represent meaningful demand pockets.
- For instance, Toyota uses flame-retardant polypropylene in its interior components to comply with FMVSS 302 flammability standards.
By End Use
In terms of end‑use industries, the electrical & electronics sector holds the largest share at 41.6% in 2024. The surge in consumer electronics, electric vehicles, and renewable‑energy infrastructure drives demand for flame‑retardant additives in printed circuit boards, housings, wiring insulation and connectors. The construction sector follows closely and is expected to exhibit robust growth given increasingly stringent fire safety codes in residential and commercial buildings. Other end‑uses – including automotive, aerospace, textiles, paints & coatings and packaging – contribute the remainder and are benefiting from expansions in lightweight materials and fire‑safe formulations.
Key Growth Drivers
Stringent Fire Safety Regulations
The growing emphasis on fire safety standards in various industries, particularly construction, automotive, and electronics, has significantly driven the demand for flame retardant chemicals. Governments and regulatory bodies across the globe are increasingly mandating stricter fire safety measures to mitigate risks in high-risk environments. As a result, industries are adopting flame retardant materials that meet specific fire-resistance standards. This trend is particularly evident in the building sector, where fire-resistant coatings and materials are being increasingly integrated into construction codes, contributing to the market's growth.
- For instance, BASF introduced its Flamestab NOR 116 additive system, designed to improve flame resistance and durability in polymer applications for construction and electrical systems.
Increasing Demand for Electronics and Electrical Equipment
The surge in consumer electronics, electric vehicles, and renewable energy systems has bolstered the demand for flame retardant chemicals. In the electronics industry, flame retardants are crucial for preventing fire hazards in components like circuit boards, connectors, and insulation. The growing adoption of electric vehicles further intensifies the need for fire-resistant materials in batteries and electrical systems. Additionally, advancements in renewable energy technologies like solar panels and wind turbines are driving the demand for fire-resistant components, thereby fueling the market’s expansion.
- For instance, Clariant offers its halogen-free Exolit™ flame retardants that provide reliable fire safety to switches, casings, and micro-assemblies in electrical and electronic parts, including emerging 5G materials.
Rising Environmental and Health Concerns
Increasing environmental and health concerns associated with halogenated flame retardants are prompting a shift towards non-halogenated alternatives. These concerns, including the toxicological impact of brominated and chlorinated flame retardants, have driven significant regulatory pressure in regions like Europe and North America. Consumers and manufacturers are increasingly prioritizing eco-friendly and sustainable flame retardants. This shift toward safer, non-toxic materials is enhancing the growth prospects of the non-halogenated flame retardant segment, which is expected to capture a larger share of the market in the coming years.
Key Trends & Opportunities
Adoption of Non-Halogenated Flame Retardants
The growing shift towards non-halogenated flame retardants presents a significant opportunity in the market. With regulatory pressure mounting against halogenated compounds due to their harmful environmental and health impacts, manufacturers are increasingly adopting non-halogenated alternatives. Materials like aluminum hydroxide and magnesium hydroxide are gaining popularity due to their effectiveness, lower toxicity, and environmental friendliness. This trend aligns with the global move towards sustainability and eco-conscious manufacturing, creating a ripe opportunity for companies focused on developing and supplying non-halogenated flame retardant solutions.
- For instance, inorganic flame‑retardant fillers such as aluminum hydroxide (ATH) are widely used because they decompose endothermically and release water vapour when heated, helping to cool the material and suppress flame propagation.
Technological Advancements in Flame Retardant Chemicals
Technological innovations in flame retardant chemicals are opening new avenues for growth. The development of advanced flame retardants that offer higher efficiency, lower toxicity, and better thermal stability is transforming various applications, particularly in the automotive, aerospace, and electronics industries. Innovations such as polymeric flame retardants, nano-based solutions, and bio-based materials are gaining traction. These advancements allow for improved performance, lightweight solutions, and increased product longevity, making them ideal for industries that prioritize both safety and efficiency. Companies investing in R&D for new flame retardant technologies are positioned to capitalize on these emerging opportunities.
- For instance, a halogen‑free salt, Aluminium diethyl phosphinate, used in engineering plastics such as polyamide and polyester-meets UL 94 V‑0 at 0.4 mm and passes glow‑wire tests at 960 °C, thereby enabling electronics manufacturers to adopt lighter, safer housings with enhanced thermal stability.
Key Challenges
Regulatory and Environmental Concerns
One of the main challenges facing the global flame retardant chemical market is the stringent regulations and growing environmental concerns surrounding certain types of flame retardants. Halogenated flame retardants, in particular, face increasing scrutiny due to their adverse environmental and health impacts. Regulatory bodies are imposing tighter restrictions on these chemicals, which limits their use and forces manufacturers to find safer alternatives. Compliance with these regulations, particularly in regions like Europe and North America, is a significant challenge for companies that need to balance safety, performance, and environmental impact in their products.
High Costs of Advanced Flame Retardants
The high cost of advanced flame retardants, particularly non-halogenated and bio-based alternatives, presents a challenge for market growth. Although these flame retardants offer superior environmental and health benefits, they often come with a higher price tag compared to traditional halogenated compounds. The increased cost of production for manufacturers, coupled with price sensitivity in certain industries, can deter companies from adopting these alternatives. As a result, balancing cost and performance while meeting regulatory requirements remains a critical challenge for companies operating in the flame retardant chemical market.
Regional Analysis
North America
In 2018, the North American flame retardant chemical market was valued at USD 1,265.33 million, holding 16.8% of the global market share. By 2024, the market is projected to reach USD 1,712.49 million, and further grow to USD 2,349.95 million by 2032, at a CAGR of 4.0% during the forecast period. The U.S. contributes significantly to the market share due to stringent fire safety regulations and the high demand from sectors like automotive, construction, and electronics. As the demand for eco-friendly and non-halogenated flame retardants rises, North America is expected to maintain a leading position in the global market.
Europe
Europe’s flame retardant chemical market, valued at USD 1,614.81 million in 2018, held 21.2% of the global market share. By 2024, the market is expected to grow to USD 2,216.48 million, and by 2032, it is projected to reach USD 3,101.10 million, growing at a CAGR of 4.2%. Europe’s strong regulatory framework, particularly in the construction, automotive, and electronics industries, drives the demand for flame retardants. The region’s push for sustainable, non-halogenated alternatives further supports market growth, positioning Europe as one of the largest and most influential markets globally.
Asia Pacific
Asia Pacific dominates the global flame retardant chemical market, with a share of 37.8% in 2018, valued at USD 2,513.93 million. By 2024, the market is projected to grow to USD 3,493.39 million, and reach USD 4,968.55 million by 2032, at a CAGR of 4.4%. The region’s rapid industrialization, expanding construction activities, and increasing demand for electronics and electric vehicles are key drivers. With major contributions from China, Japan, and India, Asia Pacific is expected to maintain its dominant position throughout the forecast period, driven by infrastructure development and fire safety regulations.
Latin America
The Latin American flame retardant chemical market was valued at USD 721.71 million in 2018, holding 9.4% of the global market share. It is projected to reach USD 1,005.75 million by 2024 and USD 1,435.79 million by 2032, growing at a CAGR of 4.5% during the forecast period. Brazil and Mexico are the key markets in this region, with increasing demand from the construction, automotive, and packaging sectors. As fire safety regulations become stricter, the market in Latin America is expected to continue expanding, particularly in industries focused on fire-resistant materials.
Middle East
The Middle East flame retardant chemical market was valued at USD 453.91 million in 2018, holding 5.9% of the global market share. By 2024, the market is expected to grow to USD 644.66 million, and reach USD 942.85 million by 2032, growing at a CAGR of 4.8%. Strong construction and infrastructure growth, particularly in the UAE and Saudi Arabia, alongside stringent fire safety regulations in sectors like oil & gas, drive the market. As sustainable and non-halogenated flame retardants gain traction, the Middle East market is expected to experience significant growth in the coming years.
Africa
The African flame retardant chemical market was valued at USD 125.19 million in 2018, holding 1.6% of the global market share. The market is projected to grow to USD 172.49 million by 2024 and USD 242.56 million by 2032, at a CAGR of 4.3%. While the market share in Africa remains small, demand for flame retardants is increasing due to infrastructure development and rising awareness of fire safety. Key industries such as construction, automotive, and textiles are driving the growth, and as regulatory frameworks strengthen, Africa is expected to see steady market expansion.
Market Segmentations:
By Type
- Non-Halogenated Flame Retardants
- Aluminum Hydroxide
- Magnesium Hydroxide
- Others
- Halogenated Flame Retardants
- Brominated Compounds
- Chlorinated Compounds
By Application
- Polyolefins
- PVC
- Epoxy Resins
- Others
By End Use
- Automotive
- Construction
- Textile
- Electronics
- Aerospace
- Paints and Coatings
- Packaging
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis in the global flame‑retardant chemical market highlights firms such as BASF SE, Albemarle Corporation, Dow Inc., LANXESS AG and ICL Group Ltd as key players. These companies command significant market share by leveraging expansive global supply‑chains, broad portfolios (covering both halogenated and non‑halogenated chemistries), and strong R&D investment into next‑gen flame‑retardant technologies such as inorganic magnesium hydroxide or bio‑based phosphorous systems. They actively pursue strategic partnerships, M&A and regional production investments to strengthen their footprint in high‑growth markets like Asia‑Pacific and Middle East. Competitive pressures force firms to prioritise cost optimisation, regulatory compliance (especially with evolving fire‑safety and environmental norms), and differentiated offering performance (e.g., low smoke, high char yield, halogen‑free). Over the forecast period, smaller niche players focusing on specialty additives may gain traction, but the incumbent majors maintain advantages in scale, customer reach and technical support, creating moderate barriers to entry for emerging rivals.\
Key Player Analysis
- Adeka Corporation
- Albemarle Corporation
- BASF
- Dow Inc.
- ICL Group
- MPI Chemie BV
- Dover Corporation
- Lanxess AG
- RTP Company
- Other Key Players
Recent Developments
- In January 2025, Nofia Solutions BV completed the acquisition of FRX Polymers, Inc. on 23 January, thereby obtaining the Nofia® halogen‑ and PFAS‑free flame‑retardant polymer technology.
- In April 2025, Mitsubishi Chemical Corporation announced the expansion of production capacity for flame‑retardant compounds at its China (Jiangsu) and France (Tiffauges) plants, with new lines scheduled to start operation from April 2025 and January 2026 respectively.
- In November 2025, Clariant International Ltd announced a strategic joint venture with FUHUA Chemical Group to develop next‑generation non‑halogenated phosphorus‑based flame retardants targeting automotive, e‑mobility, building & electronics markets.
- In September 2025, Avient Corporation launched a new line of polymer flame‑retardant additives designed to deliver enhanced flame‑retardant performance in end‑use applications
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growth will accelerate as global fire‑safety regulations tighten, driving higher adoption of flame retardant chemicals in construction, electronics and transport.
- Demand for non‑halogenated and eco‑friendly flame retardants will increase as stakeholders prioritise sustainability and regulatory compliance.
- The rise of electric vehicles and related battery systems will spur uptake of flame retardants for wiring, casings and battery modules.
- Rapid infrastructure development in Asia‑Pacific and the Middle East will create strong regional growth opportunities.
- Increasing miniaturisation and higher power density in electronics will raise the requirement for advanced flame retardant additives.
- Lightweight materials in automotive and aerospace sectors will promote flame retardant formulations compatible with high‑performance polymers.
- Rising raw material cost volatility (e.g., antimony, phosphorus) could pressure margins and spur sourcing optimisation initiatives.
- Formulation innovation (such as nano‑scale fillers, intumescent systems) will differentiate offerings and drive premiumisation.
- Greater circular‑economy focus will push development of flame retardants that support recycling and lower emissions of toxic combustion by‑products.
- Emerging markets in Latin America and Africa will deliver incremental volume growth as fire‑safety standards and industrialisation advance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Fire Safety Regulations
Increasingly strict fire safety standards in construction, automotive, and electronics sectors are compelling manufacturers to incorporate flame retardant chemicals to comply with regulatory requirements, directly boosting market demand.
Shift Toward Non-Halogenated and Eco-Friendly Solutions
Rising environmental and health concerns over halogenated flame retardants, coupled with regulatory restrictions, are accelerating the adoption of non-halogenated alternatives such as aluminum and magnesium hydroxide, expanding the market for sustainable solutions.
Growth in Electronics and Electric Vehicles
The proliferation of consumer electronics, electric vehicles, and renewable energy infrastructure is driving the need for flame retardant chemicals in components like circuit boards, wiring, and battery modules, supporting robust market growth.
Rapid Industrialization and Infrastructure Development in Asia Pacific
Expanding construction activities, urbanization, and industrial growth in Asia Pacific are fueling demand for flame retardant chemicals, especially in sectors like electronics, automotive, and building materials.
Technological Advancements in Flame Retardant Formulations
Innovations such as polymeric, nano-based, and bio-based flame retardants are enabling higher performance, lower toxicity, and better compatibility with advanced materials, opening new application areas and supporting premiumization in the market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Flame Retardant Chemical Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Flame Retardant Chemical Market projected to grow between 2025 and 2032?
Who are the major players in this market?
What are the primary factors fueling the growth of the Global Flame Retardant Chemical Market?
Who are the leading companies in the Global Flame Retardant Chemical Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Non-Halogenated Flame Retardants
- 1.2.2 Aluminum Hydroxide
- 1.2.3 Magnesium Hydroxide
- 1.2.4 Halogenated Flame Retardants
- 1.2.5 Brominated Compounds
- 1.2.6 Chlorinated Compounds
- 1.3 By End Use
- 1.3.1 Electrical & Electronics
- 1.3.2 Construction
- 1.3.3 Automotive
- 1.3.4 Aerospace
- 1.3.5 Textile
- 1.3.6 Paints and Coatings
- 1.3.7 Packaging
- 1.4 By Application
- 1.4.1 Polyolefins
- 1.4.2 PVC
- 1.4.3 Epoxy Resins
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,245.3 million → 2032: USD 13,040.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Flame Retardant Chemicals Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Flame Retardant Chemicals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Flame Retardant Chemicals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Flame Retardant Chemicals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Flame Retardant Chemicals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Flame Retardant Chemicals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Flame Retardant Chemicals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Flame Retardant Chemicals Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,245.3 million → 2032: USD 13,040.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Flame Retardant Chemicals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Non-Halogenated Flame Retardants
- 12.3.7.2 Aluminum Hydroxide
- 12.3.7.3 Magnesium Hydroxide
- 12.3.7.4 Halogenated Flame Retardants
- 12.3.7.5 Brominated Compounds
- 12.3.7.6 Chlorinated Compounds
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Electrical & Electronics
- 12.4.7.2 Construction
- 12.4.7.3 Automotive
- 12.4.7.4 Aerospace
- 12.4.7.5 Textile
- 12.4.7.6 Paints and Coatings
- 12.4.7.7 Packaging
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Polyolefins
- 12.5.7.2 PVC
- 12.5.7.3 Epoxy Resins
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Flame Retardant Chemicals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Flame Retardant Chemicals Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Flame Retardant Chemicals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Flame Retardant Chemicals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Albemarle Corporation
- 18.4 Dow Inc.
- 18.5 LANXESS AG
- 18.6 ICL Group
- 18.7 Clariant International Ltd
- 18.8 Adeka Corporation
- 18.9 Mitsubishi Chemical Corporation
- 18.10 Avient Corporation
- 18.11 MPI Chemie BV
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

