
Market Overview:
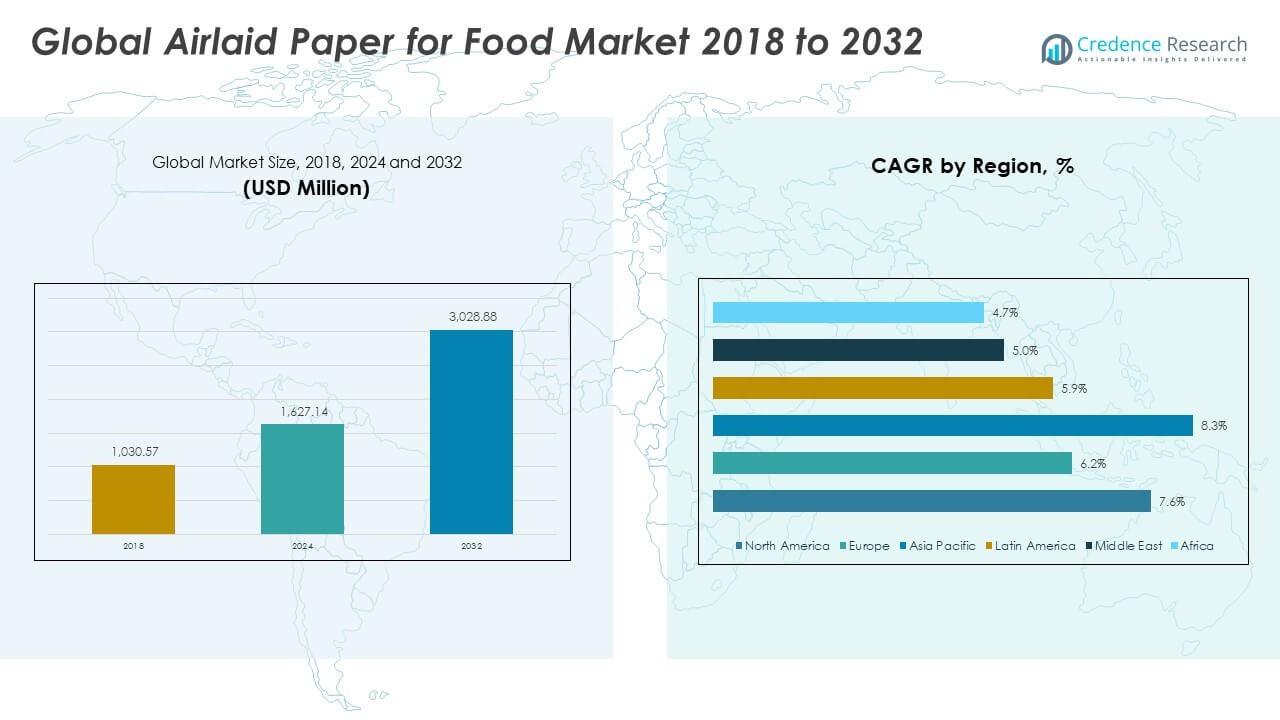
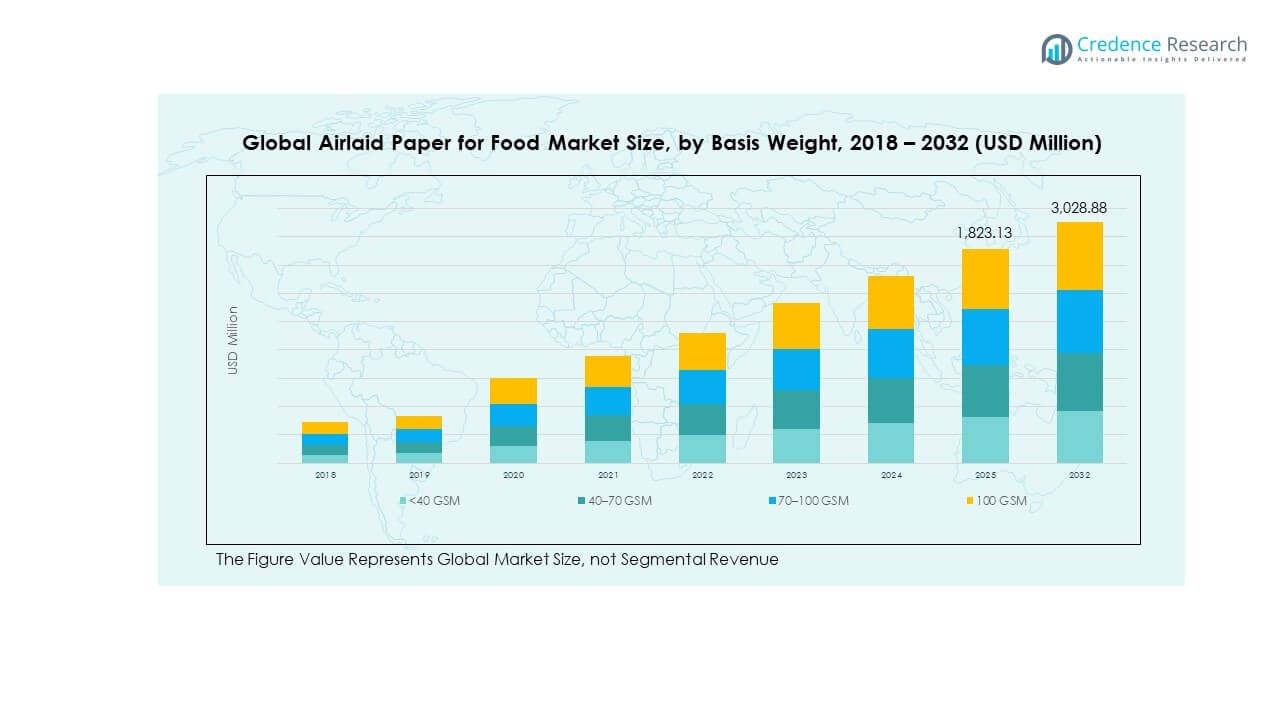
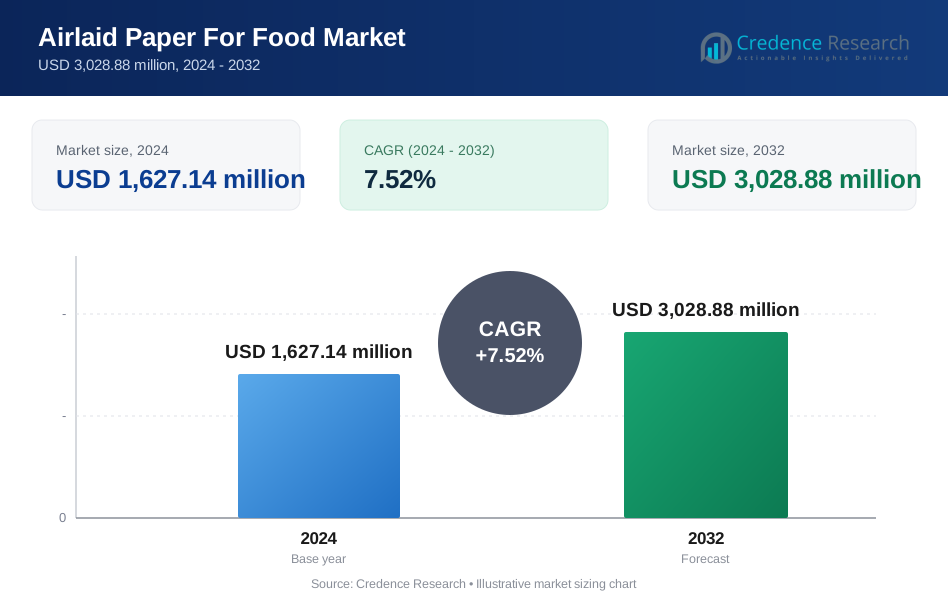
The Global Airlaid Paper for Food Market size was valued at USD 1,030.57 million in 2018 to USD 1,627.14 million in 2024 and is anticipated to reach USD 3,028.88 million by 2032, at a CAGR of 7.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Airlaid Paper for Food Market Size 2024 | USD 1,627.14 Million |
| Airlaid Paper for Food Market, CAGR | 7.52% |
| Airlaid Paper for Food Market Size 2032 | USD 3,028.88 Million |
The Global Airlaid Paper for Food Market is primarily driven by rising demand for hygienic, absorbent, and sustainable packaging solutions. The shift from plastic-based materials toward biodegradable alternatives encourages large-scale adoption of airlaid paper in meat pads, bakery wraps, and napkins. Manufacturers invest in high-performance materials that enhance durability and absorption while supporting recyclability. Increasing foodservice expansion, growth of ready-to-eat meals, and heightened focus on product safety continue to strengthen overall market demand.
Geographically, Asia Pacific leads the Global Airlaid Paper for Food Market due to expanding food processing industries, urbanization, and growing sustainability awareness. North America and Europe hold significant shares, supported by stringent packaging standards and advanced production technologies. Latin America shows steady growth, driven by rising disposable incomes and food retail expansion. The Middle East and Africa are emerging markets where changing consumer lifestyles and growing investment in food packaging infrastructure are creating new opportunities for manufacturers.
Market Insights:
- The Global Airlaid Paper for Food Market was valued at USD 1,030.57 million in 2018, reached USD 1,627.14 million in 2024, and is projected to attain USD 3,028.88 million by 2032, growing at a CAGR of 7.52%.
- Asia Pacific holds around 36% of the global share, leading due to rapid industrial expansion, urbanization, and demand for sustainable food packaging materials.
- North America accounts for about 28% of the market, supported by strong hygiene standards and widespread adoption of absorbent food packaging. Europe follows with roughly 24%, driven by advanced sustainability regulations and high consumer awareness.
- Asia Pacific remains the fastest-growing region, supported by increasing food processing activities and investments in biodegradable material technologies.
- By type, the 40–70 GSM segment accounts for nearly 45% of total market share, while 70–100 GSM represents about 30%, highlighting strong demand for mid-weight and high-strength paper grades in packaging applications.
Market Drivers
Rising Shift Toward Sustainable Food Packaging Materials
The Global Airlaid Paper for Food Market is expanding due to the growing focus on sustainable packaging solutions. Consumers and regulators demand eco-friendly alternatives to plastic wraps and synthetic liners. Airlaid paper meets these expectations through biodegradability, compostability, and minimal chemical processing. Manufacturers benefit from its low energy requirements and recyclability. The food industry increasingly adopts airlaid paper for bakery wraps, absorbent pads, and disposable food packaging. Stronger environmental regulations in Europe and North America further push manufacturers toward renewable materials. The transition aligns with global climate commitments. These factors collectively accelerate market penetration and long-term adoption.
Growing Demand from Foodservice and Ready-to-Eat Segments
Expansion in foodservice chains and the ready-to-eat sector strengthens demand for airlaid paper packaging. The material offers high absorbency, hygiene, and structural stability under heat and moisture. Restaurants, cafeterias, and delivery platforms use it for napkins, wraps, and disposable trays. It supports compliance with food-safety standards and improves convenience. Growing urban populations and fast-paced lifestyles encourage higher consumption of packaged meals. Airlaid paper helps brands maintain product freshness and reduce leakage risks. Cost efficiency and easy disposal contribute to large-scale adoption. These characteristics strengthen its position across commercial and household food applications.
Technological Advancements Enhancing Performance and Customization
Technological innovation plays a central role in improving airlaid paper quality and production efficiency. Modern equipment enables uniform fiber distribution, precise layering, and advanced bonding techniques. These developments enhance softness, strength, and absorbency across product lines. Manufacturers design specialized airlaid grades for greasy, moist, or hot food applications. Integration of natural binders and biopolymers reduces reliance on synthetic additives. Customization capabilities allow brands to align packaging properties with specific food categories. Continuous R&D investment supports higher throughput and cost competitiveness. This innovation-driven evolution widens adoption in industrial and retail packaging formats.
- For instance, McAirlaid’s Vliesstoffe GmbH specializes in premium airlaid nonwoven materials using proprietary bonding and layering technologies that enhance absorbency and strength. The company’s innovations focus on food and hygiene packaging, offering customized airlaid products for greasy and moist food applications, aligning with sustainability and performance trends in the Global Airlaid Paper for Food Market.
Rising Hygiene Standards and Regulatory Pressure in Food Handling
Increasing hygiene awareness influences packaging decisions in the food sector. Governments enforce stricter regulations on contact materials to ensure safety and traceability. Airlaid paper offers a clean, lint-free surface suitable for direct food contact. Its production involves minimal chemical residues, aligning with global safety norms. Retailers prefer airlaid materials for meat pads, fruit liners, and bakery wrapping. The ongoing replacement of single-use plastics strengthens its role in the hygiene-focused food economy. It provides superior barrier protection and absorption performance. These regulatory and health-driven preferences amplify the market’s expansion prospects.
- For instance, Duni AB, a Swedish company specializing in sustainable packaging and tableware, produces airlaid paper products designed for strict EU food-contact compliance. Its airlaid meat pads and fruit liners meet stringent chemical residue and hygiene standards, supporting food retailers’ efforts to maintain safety and regulatory adherence within the Global Airlaid Paper for Food Market.
Market Trends
Integration of Bio-Based Fibers and Advanced Manufacturing Techniques
Producers are focusing on bio-based fibers like bamboo and hemp to enhance sustainability. These materials improve strength, flexibility, and softness while reducing carbon footprint. Automation and sensor-based production systems enhance output consistency. Companies employ waterless processes and renewable binders to limit environmental impact. Lightweight airlaid variants are gaining traction in food packaging. The shift aligns with global goals for resource efficiency and cleaner manufacturing. Adoption of smart equipment shortens production cycles and ensures quality stability. These developments redefine the manufacturing landscape of airlaid paper.
- For instance, industrial hemp has been scientifically shown to produce up to 25 tons of fiber matter per hectare while using about 77% less water and inputs than cotton. Its high cellulose content of around 72% in bast fibers enables stronger, sustainable fiber output. Research confirms that the organosolv pulping process for hemp stalks enhances fiber yield and quality with reduced chemical impact, supporting sustainable raw material sourcing relevant to airlaid paper and packaging applications.
Expansion of Private Label and Customized Packaging Solutions
Private label brands increasingly demand tailored airlaid packaging designs. Retailers prefer customized absorbent pads, wraps, and liners to reflect brand identity. Producers respond with printable surfaces and embossing techniques that support brand differentiation. The rise of small and medium-sized food businesses encourages flexible design and low-volume production. Digital printing integration enables rapid response to short production runs. Airlaid paper’s versatility supports both luxury and budget packaging needs. Growing collaboration between converters and retailers drives innovation in personalized designs. This trend fosters greater brand engagement and product visibility.
- For instance, HP and Xerox have introduced verified digital printing innovations enabling short-run, customized packaging with rapid turnaround. Industry case studies report up to 30% faster job completion, supporting the growing use of digitally printed airlaid packaging within the Global Airlaid Paper for Food Market, where personalized and small-batch food packaging solutions are increasingly in demand.
Increased Use in Frozen and Perishable Food Applications
Rising consumption of frozen foods fuels demand for moisture-absorbent and durable packaging. Airlaid paper serves as an effective moisture barrier during thawing and storage. Its structure maintains integrity under varying temperatures. Producers design specific formulations for seafood, poultry, and bakery packaging. Demand grows from large supermarket chains emphasizing shelf-life extension. Airlaid liners reduce contamination risk and maintain product quality. The trend supports broader use in cold-chain logistics. These performance advantages enhance product appeal and customer satisfaction.
Digital Transformation Across the Supply Chain
Manufacturers deploy digital tools for quality monitoring and inventory management. Automated tracking systems help optimize material usage and minimize waste. Data-driven production supports real-time control of moisture levels and fiber distribution. Advanced analytics predict equipment maintenance and reduce downtime. Online platforms enhance collaboration between suppliers and end-users. Transparency across sourcing and production builds buyer confidence. Integration of Industry 4.0 technologies boosts operational efficiency and environmental compliance. This digital transformation defines the next growth phase for airlaid paper producers.
Market Challenges Analysis
High Production Costs and Limited Fiber Availability
The Global Airlaid Paper for Food Market faces cost challenges due to fiber dependency and energy requirements. Natural fiber prices fluctuate with global supply chain disruptions and climatic conditions. Production consumes considerable power, increasing operational expenses. Smaller manufacturers struggle to maintain cost parity with synthetic alternatives. Equipment maintenance and process upgrades demand heavy investment. Limited access to specialty pulps in emerging regions restricts scalability. These economic pressures slow expansion in cost-sensitive markets. Balancing quality with affordability remains a major industry obstacle.
Intense Competition from Substitute Materials and Recycling Constraints
Alternative materials like coated papers, tissue laminates, and biodegradable films compete with airlaid paper. These substitutes offer varying performance at lower cost in some applications. Recycling airlaid composites with binders presents technical difficulties. Mixed fiber content complicates material recovery and reuse. Regional recycling infrastructure often lacks capacity to process specialty packaging. Regulatory differences between markets hinder standardized recycling programs. Market participants must address sustainability communication gaps. Tackling these material and waste-management issues is essential for long-term competitiveness.
Market Opportunities
Growing Penetration in Emerging Economies and Quick-Service Food Chains
Expanding foodservice infrastructure in developing economies opens new revenue avenues. Urbanization and rising disposable income accelerate packaged food demand. Airlaid paper meets hygiene and sustainability expectations of fast-growing restaurant networks. Governments in Asia-Pacific and Latin America promote eco-friendly packaging alternatives. The material’s cost-to-performance ratio appeals to small manufacturers seeking plastic reduction. Collaborations with local converters enhance regional accessibility. This growth supports broader market diversification and supply resilience. The ongoing expansion of quick-service chains ensures consistent consumption volumes.
Innovation in Functional Coatings and Multi-Layered Product Designs
Producers explore coatings that improve grease resistance and barrier strength without compromising recyclability. Combining airlaid substrates with bio-films enhances durability and printability. These innovations target convenience packaging, bakery wraps, and heat-seal applications. Research into water-based adhesives and cellulose-derived resins improves performance standards. The integration of antimicrobial agents offers extended food protection. Partnerships between material scientists and packaging firms drive product differentiation. Technological innovation unlocks higher-value applications across multiple food categories. These advancements promise long-term opportunities for premium-grade airlaid paper adoption.
Market Segmentation Analysis:
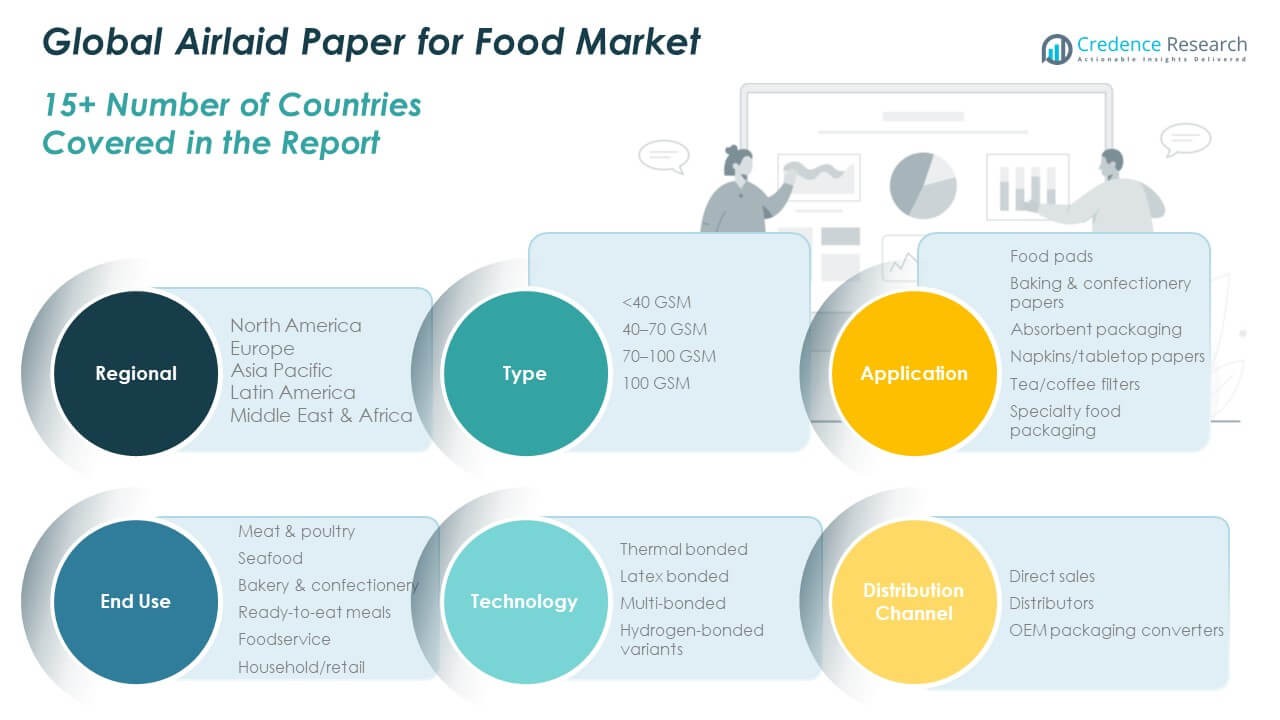
The Global Airlaid Paper for Food Market is structured across multiple segments that define its performance and growth dynamics.
By type, categories such as < 40 GSM, 40–70 GSM, 70–100 GSM, and 100 GSM serve distinct applications based on thickness, softness, and absorbency. The 40–70 GSM range is most common due to its balance of strength and cost efficiency, supporting mass production for food pads and packaging liners. Lighter variants find use in napkins and filters, while heavier grades suit absorbent or industrial packaging. Each type aligns with specific product performance and sustainability goals.
- For instance, Georgia-Pacific LLC operates advanced airlaid manufacturing facilities that utilize fiber defibration and binder application technologies to enhance absorbency and softness. The company’s airlaid materials are widely used in hygiene and food packaging applications, emphasizing consistent quality and performance across global markets.
By application, airlaid paper is used in food pads, baking and confectionery papers, absorbent packaging, napkins, tea or coffee filters, and specialty food packaging. Food pads remain the leading segment, driven by high demand from meat and seafood packaging for leakage control and hygiene. Baking and confectionery applications grow steadily due to expanding demand for grease-resistant and non-stick wrapping. Specialty packaging attracts innovation with biodegradable coatings and printed designs for brand differentiation.
By end use, meat & poultry, seafood, bakery & confectionery, ready-to-eat meals, foodservice, and household retail define consumption trends. The meat & poultry sector dominates due to widespread use of absorbent pads. Foodservice adoption is rising rapidly, fueled by quick-service outlets and delivery expansion. Household usage continues growing through retail adoption of disposable, compostable food wraps.
- For instance, Suominen Corporation, a leading nonwoven producer, implemented technological upgrades that improved processing efficiency and product softness in its airlaid paper portfolio. These enhancements support growing demand from meat, poultry, and foodservice packaging sectors, aligning with the performance and hygiene standards of the Global Airlaid Paper for Food Market.
By technology, thermal-bonded airlaid paper leads due to durability and high absorbency. Latex and multi-bonded types are expanding with new hygiene standards, while hydrogen-bonded variants offer premium softness. Distribution occurs mainly through direct sales, distributors, and OEM packaging converters, ensuring strong supply integration across regions.
Segmentation:
By Type
- < 40 GSM
- 40–70 GSM
- 70–100 GSM
- 100 GSM
By Application
- Food Pads
- Baking & Confectionery Papers
- Absorbent Packaging
- Napkins/Tabletop Papers
- Tea/Coffee Filters
- Specialty Food Packaging
By End Use
- Meat & Poultry
- Seafood
- Bakery & Confectionery
- Ready-to-Eat Meals
- Foodservice
- Household/Retail
By Technology
- Thermal Bonded
- Latex Bonded
- Multi-Bonded
- Hydrogen-Bonded Variants
By Distribution Channel
- Direct Sales
- Distributors
- OEM Packaging Converters
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Airlaid Paper for Food Market size was valued at USD 295.10 million in 2018 to USD 458.54 million in 2024 and is anticipated to reach USD 857.20 million by 2032, at a CAGR of 7.6 % during the forecast period. North America accounts for nearly 28 % of the global market share, driven by strong food packaging regulations and advanced manufacturing capabilities. The U.S. leads consumption due to a high demand for absorbent food pads and ready-to-eat meal packaging. Canada and Mexico contribute through expanding retail food chains and adoption of biodegradable materials. Major producers invest in automation and fiber innovation to improve absorbency and sustainability. Consumer awareness of hygiene and food safety further enhances market penetration. Stringent standards on single-use plastics encourage rapid substitution with airlaid paper formats. Robust distribution networks and strategic partnerships support regional growth.
Europe
The Europe Global Airlaid Paper for Food Market size was valued at USD 186.78 million in 2018 to USD 278.27 million in 2024 and is anticipated to reach USD 469.53 million by 2032, at a CAGR of 6.2 % during the forecast period. Europe holds about 24 % of the global share, anchored by early adoption of sustainable packaging solutions. Germany, France, and the U.K. remain key markets supported by strict food contact regulations and circular-economy initiatives. Manufacturers integrate recyclable coatings and renewable binders to meet EU sustainability directives. The bakery and confectionery sectors dominate demand, supported by premium packaging standards. Regional brands emphasize compostable food wraps and grease-resistant airlaid materials. Ongoing R&D in bio-fiber technology enhances material performance. Growing exports to Central and Eastern Europe expand production capacity across major countries.
Asia Pacific
The Asia Pacific Global Airlaid Paper for Food Market size was valued at USD 455.87 million in 2018 to USD 746.01 million in 2024 and is anticipated to reach USD 1,472.40 million by 2032, at a CAGR of 8.3 % during the forecast period. The region dominates with an estimated 36 % market share, supported by high population density and rapid urbanization. China and Japan are key producers leveraging large-scale food packaging industries. India and Southeast Asia show rising consumption driven by quick-service restaurants and disposable hygiene culture. Domestic manufacturers adopt advanced bonding technologies to enhance production efficiency. Government initiatives promoting sustainable packaging accelerate demand in export-oriented food processing. Expanding retail infrastructure and e-commerce strengthen supply networks. Local companies invest in low-cost biodegradable variants to capture emerging consumer segments.
Latin America
The Latin America Global Airlaid Paper for Food Market size was valued at USD 48.68 million in 2018 to USD 75.90 million in 2024 and is anticipated to reach USD 125.05 million by 2032, at a CAGR of 5.9 % during the forecast period. Latin America contributes around 6 % of the global market share, led by Brazil and Mexico. Expanding foodservice industries and rising demand for hygienic packaging support growth. Regional suppliers introduce affordable airlaid grades suitable for bakery and meat packaging. Import reliance remains moderate, with new local production units emerging in key cities. Government efforts to limit plastic waste stimulate sustainable alternatives. Retail chains increasingly adopt compostable food pads and wrapping paper. Rising consumer preference for clean-label packaging drives innovation. Continuous expansion in supermarket networks sustains long-term adoption.
Middle East
The Middle East Global Airlaid Paper for Food Market size was valued at USD 26.92 million in 2018 to USD 38.59 million in 2024 and is anticipated to reach USD 59.72 million by 2032, at a CAGR of 5.0 % during the forecast period. The region holds about 3 % of the global share, supported by growth in the food processing and hospitality sectors. The UAE and Saudi Arabia lead adoption with rising fast-food consumption and imported food packaging standards. Manufacturers emphasize high-absorbency papers for meat and bakery applications. Investment in food logistics and cold-chain operations expands usage of absorbent liners. Local distributors strengthen supply channels across retail and institutional buyers. Regulatory alignment toward sustainable packaging increases import of eco-certified products. Gradual localization of production facilities enhances regional competitiveness and cost efficiency.
Africa
The Africa Global Airlaid Paper for Food Market size was valued at USD 17.22 million in 2018 to USD 29.82 million in 2024 and is anticipated to reach USD 44.97 million by 2032, at a CAGR of 4.7 % during the forecast period. Africa accounts for approximately 3 % of the global market share, showing steady progress in urban and retail expansion. South Africa, Nigeria, and Egypt lead regional demand with growing packaged food consumption. Adoption remains limited by high production costs and import dependency. Local converters are beginning to introduce small-scale manufacturing for absorbent packaging. Rising middle-class income and modern retail growth create long-term opportunities. Awareness of hygiene and sustainability is spreading among consumers. International partnerships are improving material availability and technology transfer across the continent.
Key Player Analysis:
- Glatfelter Corporation
- Domtar Corporation
- Ahlstrom
- Mölnlycke Health Care
- Nippon Paper Industries Co., Ltd.
Competitive Analysis:
The competitive landscape for the Global Airlaid Paper for Food Market features several well-established firms that drive innovation, manufacturing scale and geographical reach. Leading companies such as Glatfelter Corporation, Georgia‑Pacific LLC and Domtar Corporation maintain substantial market share through extensive product portfolios and global distribution networks. These firms invest heavily in research and development to enhance absorbency, softness and sustainability of their airlaid offerings. Mid-level players such as McAirlaid’s Vliesstoffe GmbH and Ahlstrom‑Munksjö Corporation pursue strategic partnerships and regional manufacturing to accelerate growth. Smaller niche participants often focus on eco-friendly binders or regional specialty packaging solutions. Competitive tactics include capacity expansion, acquisitions and new product launches targeted at rising end-use segments such as meat & poultry and ready-to-eat meals. Ultimately, it remains critical for companies to differentiate on performance metrics and sustainability credentials to maintain leadership.
Recent Developments:
- In July 2024, Berry Global Group, Inc. and Glatfelter Corporation officially announced the new brand identity “Magnera Corporation” for their proposed merged nonwovens and films business. The rebranding reflects the companies’ strategic alignment to strengthen their presence in sustainable materials, including food-grade airlaid applications.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End Use, Technology and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global demand for sustainable food packaging materials will continue to drive strong growth across developed and emerging economies.
- Expansion of foodservice, bakery, and ready-to-eat meal sectors will increase adoption of absorbent and hygienic airlaid paper solutions.
- Manufacturers will prioritize recyclable and compostable grades to comply with tightening environmental regulations worldwide.
- Technological innovations in bonding, fiber alignment, and biodegradable coatings will enhance product performance and durability.
- Growth in private-label packaging and custom branding will encourage design diversification and premium product development.
- Strategic alliances between producers and food packaging converters will strengthen supply chain integration and market reach.
- Asia Pacific will remain the fastest-growing region, supported by industrial expansion, urbanization, and changing dietary patterns.
- North America and Europe will focus on R&D and automation to maintain quality leadership in sustainable manufacturing.
- New entrants will explore niche applications such as tea filters and specialty wrapping, targeting eco-conscious consumers.
- Long-term investments in circular packaging ecosystems will ensure steady market expansion and material innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Sustainable Food Packaging Materials
Increasing regulatory and consumer pressure to reduce plastic waste is driving food manufacturers and retailers to adopt biodegradable and compostable airlaid paper solutions, especially for meat pads, bakery wraps, and disposable food packaging.
Growth in Foodservice and Ready-to-Eat Segments
The rapid expansion of foodservice chains and the popularity of ready-to-eat meals are boosting demand for absorbent, hygienic, and convenient packaging formats, where airlaid paper excels due to its high absorbency and structural stability.
Technological Advancements in Material Performance
Innovations in fiber bonding, layering, and the use of bio-based fibers are enhancing the absorbency, strength, and sustainability of airlaid paper, making it more attractive for a wider range of food packaging applications.
Rising Hygiene Standards and Regulatory Pressure
Stricter food safety regulations and heightened hygiene awareness are prompting the adoption of airlaid paper, which offers clean, lint-free surfaces and minimal chemical residues, aligning with global food contact and safety standards.
Expansion in Emerging Markets and Quick-Service Chains
Urbanization, rising disposable incomes, and the growth of quick-service restaurants in Asia Pacific and Latin America are creating new opportunities for airlaid paper adoption, supported by government initiatives to promote eco-friendly packaging.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Airlaid Paper for Food Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Airlaid Paper for Food Market projected to grow between 2024 and 2032?
Which Global Airlaid Paper for Food Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Airlaid Paper for Food Market?
Who are the leading companies in the Global Airlaid Paper for Food Market?
Which region commanded the largest share of the Global Airlaid Paper for Food Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 < 40 GSM
- 1.2.2 40–70 GSM
- 1.2.3 70–100 GSM
- 1.2.4 100 GSM
- 1.3 By End Use
- 1.3.1 Meat & Poultry
- 1.3.2 Seafood
- 1.3.3 Bakery & Confectionery
- 1.3.4 Ready-to-Eat Meals
- 1.3.5 Foodservice
- 1.3.6 Household/Retail
- 1.4 By Technology
- 1.4.1 Thermal Bonded
- 1.4.2 Latex Bonded
- 1.4.3 Multi-Bonded
- 1.4.4 Hydrogen-Bonded Variants
- 1.5 By Application
- 1.5.1 Food Pads
- 1.5.2 Baking & Confectionery Papers
- 1.5.3 Absorbent Packaging
- 1.5.4 Napkins/Tabletop Papers
- 1.5.5 Tea/Coffee Filters
- 1.5.6 Specialty Food Packaging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,627.14 million → 2032: USD 3,028.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Airlaid Paper For Food Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Airlaid Paper For Food Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Airlaid Paper For Food Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Airlaid Paper For Food Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Airlaid Paper For Food Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Airlaid Paper For Food Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Airlaid Paper For Food Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Airlaid Paper For Food Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,627.14 million → 2032: USD 3,028.88 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Airlaid Paper For Food Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 < 40 GSM
- 12.3.7.2 40–70 GSM
- 12.3.7.3 70–100 GSM
- 12.3.7.4 100 GSM
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Meat & Poultry
- 12.4.7.2 Seafood
- 12.4.7.3 Bakery & Confectionery
- 12.4.7.4 Ready-to-Eat Meals
- 12.4.7.5 Foodservice
- 12.4.7.6 Household/Retail
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Thermal Bonded
- 12.5.7.2 Latex Bonded
- 12.5.7.3 Multi-Bonded
- 12.5.7.4 Hydrogen-Bonded Variants
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Food Pads
- 12.6.7.2 Baking & Confectionery Papers
- 12.6.7.3 Absorbent Packaging
- 12.6.7.4 Napkins/Tabletop Papers
- 12.6.7.5 Tea/Coffee Filters
- 12.6.7.6 Specialty Food Packaging
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Airlaid Paper For Food End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Airlaid Paper For Food Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Airlaid Paper For Food Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Airlaid Paper For Food Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Glatfelter Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Domtar Corporation
- 18.4 Ahlstrom
- 18.5 Mölnlycke Health Care
- 18.6 Nippon Paper Industries Co., Ltd.
- 18.7 Georgia-Pacific LLC
- 18.8 McAirlaid’s Vliesstoffe GmbH
- 18.9 Berry Global Group, Inc.
- 18.10 Duni AB
- 18.11 Suominen Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

