
Market Overview:
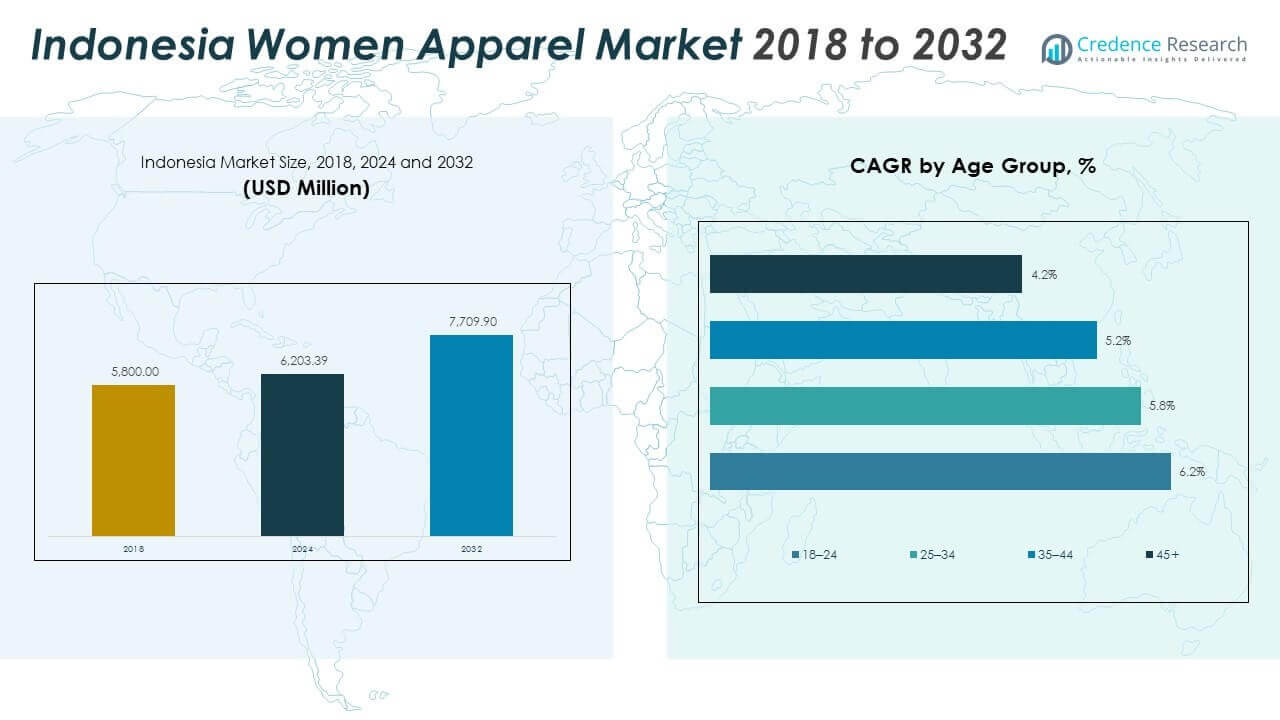
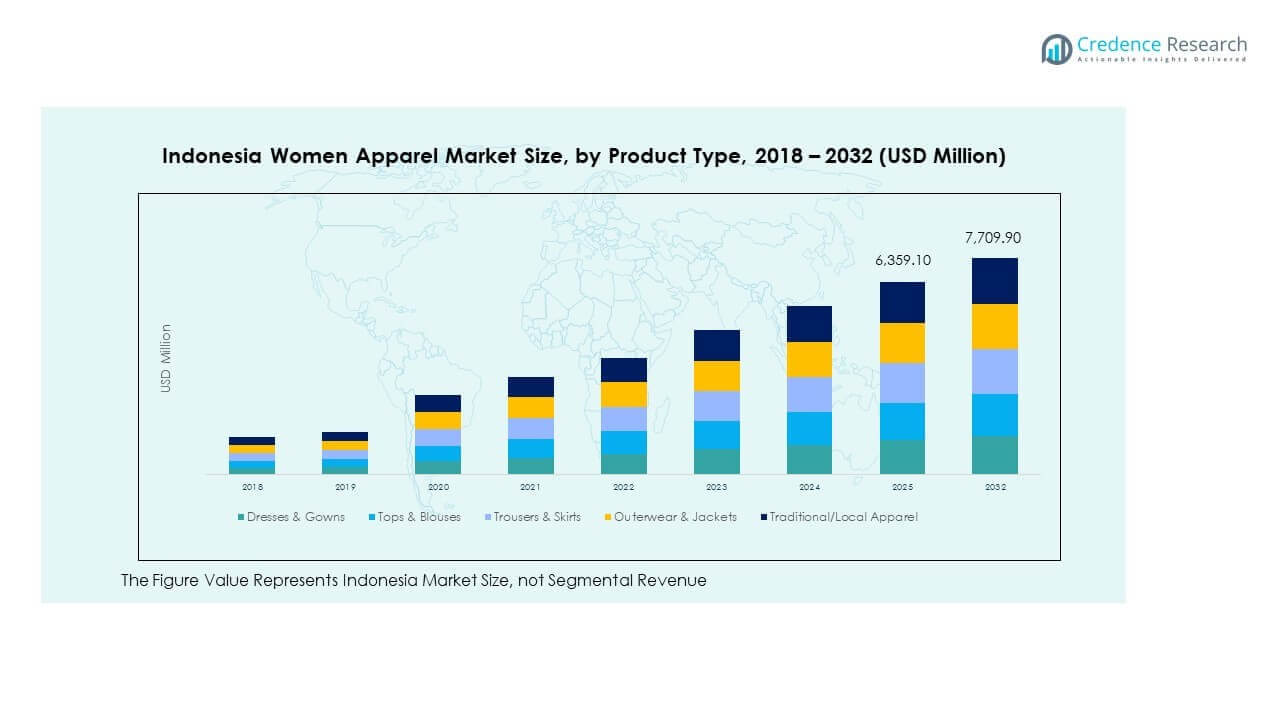
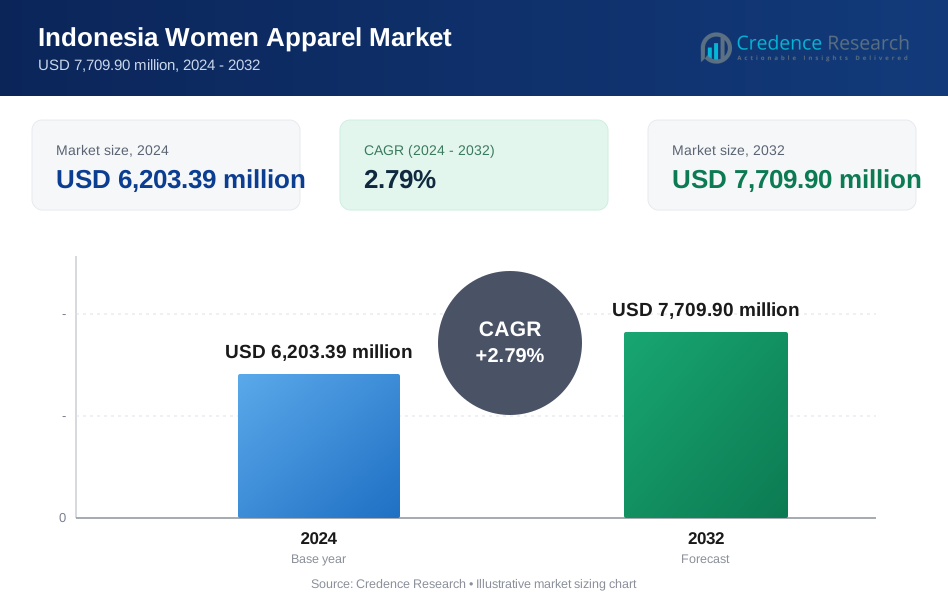
The Indonesia Women Apparel Market size was valued at USD 5,800.00 million in 2018 to USD 6,203.39 million in 2024 and is anticipated to reach USD 7,709.90 million by 2032, at a CAGR of 2.79% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Indonesia Women Apparel Market Size 2024 | USD 6,203.39 million |
| Indonesia Women Apparel Market, CAGR | 2.79% |
| Indonesia Women Apparel Market Size 2032 | USD 7,709.90 million |
Rising urbanization, expanding middle-income groups, and increasing fashion awareness among young women continue to drive demand. Social media, mobile commerce, and local influencer culture shape style preferences and product discovery. Organized retail expansion and improved access to branded apparel widen the buyer base. Consumer shifts toward comfort, modest wear, and value-for-money fashion strengthen category performance. E-commerce platforms boost convenience and offer wider reach, especially across price-sensitive and trend-driven segments.
Java leads the market with strong urban demand, retail infrastructure, and high youth population. Cities like Jakarta, Bandung, and Surabaya show high brand engagement and premium spending patterns. Sumatra and Kalimantan follow with steady adoption of fashion trends, supported by regional malls and mobile-based purchases. Sulawesi and Bali show rising demand through boutique labels and cultural apparel, while Eastern Indonesia remains an emerging zone with growing retail access and digital influence.
Market Insights
- The market was valued at USD 5,800.00 million in 2018, USD 6,203.39 million in 2024, and is projected to reach USD 7,709.90 million by 2032, registering a CAGR of 2.79%.
- Java dominates with 55% share due to urban concentration, followed by Sumatra at 16% and Kalimantan at 9%, driven by expanding retail and consumer base.
- Sulawesi and Bali together hold 15% share, with Bali benefiting from tourism-linked fashion demand and boutique-style retail experiences.
- The 45+ age group is the fastest-growing segment at 6.2% CAGR, while 35–44 follows at 5.8%, reflecting rising style awareness and disposable income.
- Dresses & Gowns lead product preference, and e-commerce continues gaining traction among younger consumers and rural buyers, supporting long-term growth.
Market Drivers
Urbanization, Rising Middle-Class Income, and Changing Fashion Consciousness Among Young Consumers
Rapid urbanization and growing middle-class income drive fashion adoption in Indonesia. Young consumers, especially women in urban areas, influence apparel trends. Increasing exposure to global fashion through social media accelerates demand for modern styles. The Indonesia Women Apparel Market gains from rising brand consciousness and peer influence. Western and Korean fashion continue to shape purchase decisions. Fashion becomes a form of self-expression for younger women. Local brands respond quickly with seasonal collections. The market benefits from a cultural shift toward modern dressing styles. It shows high alignment with youth-centric product positioning.
- For instance, Erigo achieved a 105.6% sales target achievement in July 2022, reaching IDR 239,795,250 through Instagram campaigns targeting urban Gen Z. This performance was documented in a study analyzing that specific month.
Expansion of Organized Retail Formats Across Tier 1 and Tier 2 Cities
Wider retail presence improves accessibility and consumer experience in apparel shopping. Shopping malls, department stores, and fashion chains increase penetration in mid-size cities. The Indonesia Women Apparel Market sees higher footfall and conversion in organized retail. Retailers offer segmented product lines for casual, formal, and modest wear. Store layout and ambience enhance brand positioning and lifestyle branding. Affordable luxury and premium mid-range labels attract aspirational consumers. Organized players also invest in in-store promotions and influencer campaigns. Product trials, visual merchandising, and loyalty programs support repeat purchases. The growth of domestic fashion labels supports organized retail expansion.
Digital Transformation, Social Media Marketing, and E-commerce Growth
Indonesia’s e-commerce boom plays a central role in shaping apparel sales trends. Online platforms offer wider reach, convenience, and affordability for women shoppers. Mobile-first interfaces and digital wallets simplify the shopping journey. The Indonesia Women Apparel Market benefits from social commerce models and influencer-driven sales. Instagram and TikTok act as major channels for product discovery. Micro-influencers collaborate with brands for short-term campaigns. Social media marketing drives visibility for seasonal promotions and limited drops. Platforms like Shopee and Tokopedia offer exclusive deals and fast delivery. Customer reviews and easy return policies boost online purchase confidence.
- For instance, Erigo amassed 3.2 million followers across Instagram, TikTok, YouTube, and Facebook by 2023, with TikTok Shop live streaming showing a 0.761 correlation to purchase decisions, highlighting strong conversion influence.
Rising Preference for Modest Fashion and Culturally Aligned Clothing Styles
A large Muslim population supports growing interest in modest fashion apparel. Women seek clothing that blends religious values with modern aesthetics. Hijab-friendly fashion, maxi dresses, and loose silhouettes see strong demand. The Indonesia Women Apparel Market aligns with this shift through expanded modest wear lines. Designers blend tradition with contemporary styling to meet evolving expectations. Festive collections, wedding wear, and Eid-themed apparel show strong seasonal spikes. Islamic fashion weeks promote homegrown designers and inspire product innovation. Modest fashion also gains export traction in neighboring Muslim-majority countries. It positions Indonesia as a modest fashion hub in Southeast Asia.
Market Trends
Rise of Ethical Fashion, Sustainable Materials, and Conscious Consumer Behavior
Eco-conscious buying becomes more prevalent among urban women shoppers. Consumers evaluate sustainability in materials, processes, and brand practices. The Indonesia Women Apparel Market reflects rising demand for organic cotton, bamboo fabrics, and low-impact dyes. Local brands adopt small-batch production to minimize waste. Consumers seek transparency in sourcing and ethical labor practices. Sustainable fashion events and pop-ups attract new-age buyers. Gen Z leads the movement toward climate-responsible fashion. Fashion resale platforms and thrifting also gain acceptance. Brands with sustainability credentials build long-term brand trust and loyalty.
- For instance, SukkhaCitta transformed 118 acres of farmland through regenerative cotton farming and supported over 1,500 individuals through its supply chain, as highlighted in National Geographic’s sustainability coverage.
Customization, Personal Styling, and Use of AI in Apparel Recommendations
Technology personalizes fashion like never before in this market. Retailers offer AI-based styling assistants and size recommendation tools. The Indonesia Women Apparel Market witnesses rising engagement with virtual try-on features. Consumers appreciate curated style feeds and outfit bundles based on body type. Local fashion tech startups help shoppers discover new looks. Retailers use customer data to push tailored suggestions via email and apps. Subscription-based fashion services offer rotating wardrobes and curated deliveries. The fusion of AI and retail improves experience and reduces returns. Fashion personalization supports higher satisfaction and basket size.
Streetwear, Athleisure, and Everyday Functional Wear Influence
Practicality, comfort, and multi-use apparel take priority in style decisions. Streetwear and athleisure gain appeal across age segments. The Indonesia Women Apparel Market embraces oversized silhouettes, joggers, and coordinated sets. Fashion-forward women prefer stylish yet wearable options for daily use. Sneakers, crossbody bags, and breathable fabrics complement active lifestyles. Brands mix urban looks with tropical-friendly materials. Local labels experiment with bold prints, slogans, and capsule drops. Athleisure brands collaborate with celebrities to enhance visibility. Daily wear evolves into a fashion statement beyond traditional categories.
- For instance, local Indonesian athleisure brands featured in Jakarta pop-ups launched coordinated sets using breathable, tropical-adapted fabrics, with collections showcased at events that drew thousands of urban shoppers.
Rise of Local Independent Designers and Niche Fashion Communities
Small fashion brands carve loyal customer bases through niche positioning. They offer exclusivity, cultural relevance, and direct-to-consumer engagement. The Indonesia Women Apparel Market supports this shift through Instagram boutiques and craft-based brands. Hand-embroidery, batik fusion, and gender-neutral styles gain traction. Local designers participate in regional fashion weeks and pop-up exhibitions. These creators appeal to identity-conscious consumers seeking originality. Fashion communities grow through Telegram groups, TikTok trends, and creator-led platforms. Niche labels avoid mass production and retain design integrity. Independent labels add cultural depth to Indonesia’s fashion identity.
Market Challenges Analysis
Intense Price-Based Competition and Limited Differentiation Among Mid-Tier Brands
The mid-tier segment faces heavy competition from both local and imported labels. Many brands operate with similar price points and overlapping product lines. The Indonesia Women Apparel Market struggles with over-reliance on discounts and flash sales. Small players lack brand recall or customer loyalty programs. Fast fashion giants use economies of scale to dominate visibility and margins. Price wars reduce profitability across retail channels. Brands face difficulty in maintaining originality with rapid trend cycles. Imitation of popular styles leads to saturation in collections. The need for clear differentiation becomes critical to avoid churn.
Supply Chain Volatility, Raw Material Dependence, and Rising Import Costs
Volatile textile supply chains affect production timelines and delivery cycles. Many Indonesian apparel brands depend on imported fabrics and trims. The Indonesia Women Apparel Market faces cost pressure from currency fluctuation and shipping delays. Local sourcing networks are still developing for specialized fabrics. Factory delays during festive rush periods disrupt launch timelines. Geopolitical factors and trade restrictions increase import uncertainty. Domestic manufacturers face labor shortages and limited automation. Inventory misalignment due to forecasting errors leads to overstock or sell-outs. Supply inefficiencies hinder seamless product availability across regions.
Market Opportunities
Untapped Growth in Rural and Tier 3 Markets Supported by Digital Penetration
Emerging internet access and smartphone usage support rural apparel consumption. Women in Tier 3 towns show growing awareness of fashion trends. The Indonesia Women Apparel Market can unlock potential through regional influencers and vernacular campaigns. E-commerce platforms bridge product gaps in underserved locations. Mobile-first design, cash-on-delivery, and localized sizing aid rural adoption. Brands offering modest pricing and multi-use products will gain early traction.
Potential to Expand Indonesia’s Modest Fashion Segment into Global Export Markets
Indonesia can lead Southeast Asia in modest fashion innovation and export. Cultural richness and Islamic fashion creativity attract foreign buyers. The Indonesia Women Apparel Market can scale through trade shows and B2B platforms. Partnering with global retailers opens access to Muslim-majority markets. Certifications for ethical production and modest compliance boost appeal. It positions the country as a value-added apparel exporter.
Market Segmentation Analysis
Product Type
The Indonesia Women Apparel Market sees strong demand across product categories, with Dresses & Gowns leading due to cultural events and formal wear needs. Tops & Blouses perform well in casual and office settings, while Trousers & Skirts offer versatility. Outerwear & Jackets grow seasonally and in urban zones. Traditional/Local Apparel remains essential during festivals and regional celebrations.
- For instance, Batik Keris offers an extensive online collection of women’s batik dresses featuring traditional Nusantara motifs, catering to both formal and casual occasions.
Age Group
Women aged 25–34 represent the largest consumer base in the Indonesia Women Apparel Market, driven by fashion awareness and disposable income. The 18–24 segment also shows strong demand for trendy and affordable styles. Buyers aged 35–44 prioritize quality and comfort. The 45+ segment seeks modest, durable options.
Income Level
The middle-income group dominates the Indonesia Women Apparel Market with consistent purchases across price ranges. High-income consumers drive growth in the premium category, seeking exclusive and branded collections. The low-income group shows steady volume demand in the value segment.
- For instance, Matahari Department Store, a key offline retailer, offers a wide range of mid-tier women’s apparel across its outlets in Indonesia, supporting broad access to fashion for urban and suburban shoppers.
Price Segment
The Value/Mass Market segment holds the highest share in the Indonesia Women Apparel Market, supported by wide affordability. Mid-Range offerings attract aspirational buyers balancing quality and price. Luxury/Premium remains niche but expands with rising brand preference in urban areas.
Distribution Channel
Offline Retail leads the Indonesia Women Apparel Market due to store access in malls and high-street locations. Online Retail grows rapidly through mobile commerce and influencer marketing. Direct Sales & Pop-up Stores help brands connect locally with targeted offerings.
Segmentation
By Product Type
- Dresses & Gowns
- Tops & Blouses
- Trousers & Skirts
- Outerwear & Jackets
- Traditional/Local Apparel
By Age Group
- 18–24
- 25–34
- 35–44
- 45+
By Income Level
- Low
- Middle
- High
By Price Segment
- Luxury/Premium
- Mid-Range
- Value/Mass Market
By Distribution Channel
- Online Retail
- Offline Retail
- Direct Sales & Pop-up Stores
Regional Analysis
Java – The Retail and Fashion Powerhouse Holding Over 55% Market Share
Java dominates the Indonesia Women Apparel Market with more than 55% revenue share in 2024. The island’s dense population, strong urban infrastructure, and high retail concentration support robust demand. Jakarta, Surabaya, and Bandung act as major hubs for fashion consumption and retail expansion. Women in urban Java show higher brand awareness and spending capacity. Organized retail, fashion chains, and e-commerce fulfillment centers are highly concentrated in this region. Java’s youthful population continues to drive seasonal apparel turnover and trend adoption across both mid-range and premium categories.
Sumatra and Kalimantan – Expanding Market Base with Nearly 25% Combined Share
Sumatra accounts for about 16% of the market while Kalimantan contributes nearly 9%. These regions reflect rising middle-income households and growing exposure to fashion trends. Tier-2 and Tier-3 cities such as Medan, Palembang, and Banjarmasin show increasing retail penetration. The Indonesia Women Apparel Market leverages offline and mobile-first platforms to reach consumers in these zones. Economic development zones and regional malls support product access in suburban areas. Brands focusing on modest wear and daily fashion gain strong traction in these markets due to cultural alignment and practical demand.
Sulawesi, Bali, and Eastern Indonesia – Emerging Clusters with Approx. 20% Share
Sulawesi and Bali collectively hold around 15% of the market, with the rest from Papua, Maluku, and Nusa Tenggara. Bali leads in fashion-driven tourism retail, serving both domestic and international consumers. Sulawesi shows rising urban development in cities like Makassar, boosting apparel demand. The Indonesia Women Apparel Market finds growth in local fashion boutiques, pop-up stores, and cultural fusion wear in these subregions. Eastern Indonesia sees slower adoption but growing awareness due to improving connectivity and digital outreach. Market players focusing on affordability and localized designs gain early mover advantage here.
Key Player Analysis
- Matahari Department Store
- PT Ramayana Lestari Sentosa
- PT Mitra Adiperkasa
- Berrybenka
- Hijup
Competitive Analysis
The Indonesia Women Apparel Market features a mix of domestic retailers, department stores, e-commerce players, and niche designers. Key players include Matahari Department Store, PT Ramayana Lestari Sentosa, PT Mitra Adiperkasa, Berrybenka, and Hijup. These companies dominate the formal and casual wear categories across offline and online channels. Matahari and Ramayana lead in the mass-market segment through expansive retail footprints. Hijup and Berrybenka specialize in modest fashion and digital-first retailing, catering to younger, tech-savvy consumers. It remains highly competitive with minimal entry barriers for local brands. E-commerce platforms allow smaller fashion labels to scale quickly through curated online storefronts. Price sensitivity shapes product positioning across most categories. Brands differentiate through local styling, fabric innovation, and influencer-driven marketing. Fast fashion trends push continuous product refresh cycles, making agility essential. The Indonesia Women Apparel Market continues to evolve as local and international brands compete across style, speed, and sustainability.
Recent Developments
- In December 2025, PT Mitra Adiperkasa entered a partnership with Abercrombie & Fitch to launch stores in Indonesia, expanding its apparel offerings including women's lines.
- In September 2025, Pacific Universal Investments from Singapore acquired a stake in PT Mitra Adiperkasa, cleared by the Philippine Competition Commission, potentially boosting its position in the women's apparel market.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Age Group, Income Level, Price Segment and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Urban youth demand will continue to shape trends, driving sales of fast fashion and lifestyle wear.
- E-commerce penetration will deepen across rural and Tier-3 cities with mobile-first strategies.
- Local brands will gain ground through modest fashion, cultural styling, and sustainability focus.
- AI-based personalization, virtual fitting, and smart recommendation tools will enhance customer experience.
- Organized retail expansion across emerging cities will fuel offline and omni-channel growth.
- Fashion-tech startups will innovate with data-led design and influencer-driven micro-collections.
- The modest wear category will remain a high-potential growth driver, supported by cultural alignment.
- Indonesia is likely to emerge as a modest fashion exporter to Southeast Asian and Muslim-majority markets.
- The value/mass-market segment will remain dominant, with new entrants competing on price and quality.
- Investment in ethical sourcing and sustainable materials will influence consumer preferences and brand loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Expanding Middle Class
Rapid urbanization and a growing middle-income population in Indonesia are increasing disposable incomes and driving demand for fashionable women's apparel, especially in urban centers like Jakarta, Bandung, and Surabaya.
Digital Transformation and E-commerce Growth
The proliferation of e-commerce platforms, mobile commerce, and social media marketing has made fashion more accessible, enabling brands to reach younger and rural consumers and driving overall market expansion.
Rising Fashion Consciousness Among Young Women
Exposure to global trends via social media and influencer culture is shaping style preferences, with younger women seeking modern, expressive, and trend-driven apparel, fueling demand for both local and international brands.
Preference for Modest and Culturally Aligned Fashion
Indonesia's large Muslim population is driving strong demand for modest wear, such as hijab-friendly and culturally inspired apparel, positioning the country as a regional hub for modest fashion innovation.
Organized Retail and Omni-channel Expansion
The growth of organized retail formats and the integration of offline and online channels are improving consumer access and experience, supporting higher conversion rates and brand engagement across diverse consumer segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Indonesia Women Apparel Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Indonesia Women Apparel Market projected to grow between 2024 and 2032?
Which Indonesia Women Apparel Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Indonesia Women Apparel Market?
Who are the leading companies in the Indonesia Women Apparel Market?
Which region commanded the largest share of the Indonesia Women Apparel Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Age Group
- 1.2.1 18–24
- 1.2.2 25–34
- 1.2.3 35–44
- 1.2.4 45+
- 1.3 By Product Type
- 1.3.1 Dresses & Gowns
- 1.3.2 Tops & Blouses
- 1.3.3 Trousers & Skirts
- 1.3.4 Outerwear & Jackets
- 1.3.5 Traditional/Local Apparel
- 1.4 By Price Segment
- 1.4.1 Luxury/Premium
- 1.4.2 Mid-Range
- 1.4.3 Value/Mass Market
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,203.39 million → 2032: USD 7,709.90 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Indonesia Women Apparel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Indonesia Women Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Indonesia Women Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Indonesia Women Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Indonesia Women Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Indonesia Women Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Indonesia Women Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Indonesia Women Apparel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,203.39 million → 2032: USD 7,709.90 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Indonesia Women Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Age Group - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 18–24
- 12.3.7.2 25–34
- 12.3.7.3 35–44
- 12.3.7.4 45+
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dresses & Gowns
- 12.4.7.2 Tops & Blouses
- 12.4.7.3 Trousers & Skirts
- 12.4.7.4 Outerwear & Jackets
- 12.4.7.5 Traditional/Local Apparel
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Price Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Luxury/Premium
- 12.5.7.2 Mid-Range
- 12.5.7.3 Value/Mass Market
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Indonesia Women Apparel Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Indonesia Women Apparel Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Indonesia Women Apparel Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Matahari Department Store
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 PT Ramayana Lestari Sentosa
- 17.4 PT Mitra Adiperkasa
- 17.5 Berrybenka
- 17.6 Hijup
- 17.7 Zalora Indonesia
- 17.8 Erigo
- 17.9 Batik Keris
- 17.10 H&M Indonesia
- 17.11 Uniqlo Indonesia
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

