
Market Overview:
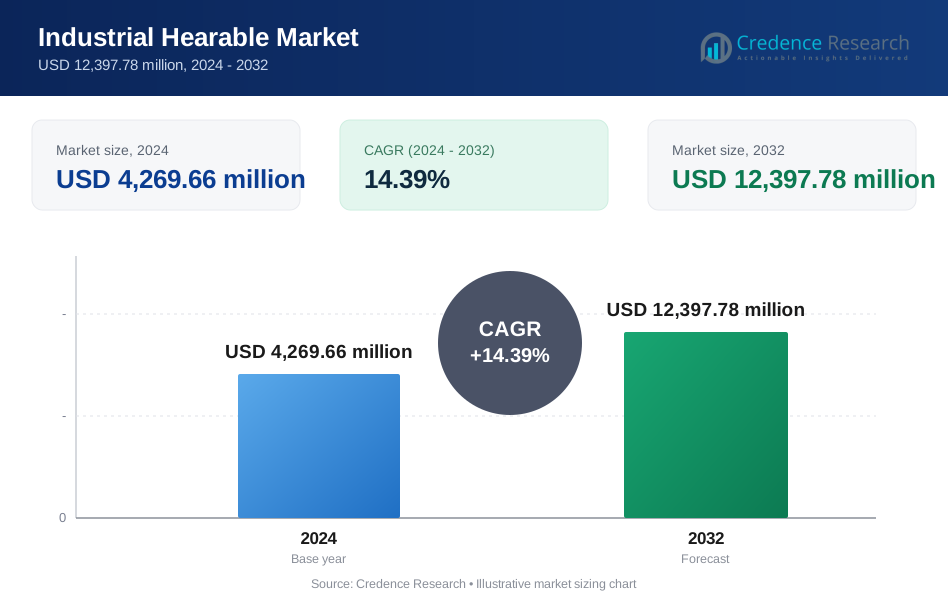
The Industrial Hearable Market size was valued at USD 2,800.00 million in 2018 to USD 4,269.66 million in 2024 and is anticipated to reach USD 12,397.78 million by 2032, at a CAGR of 14.39% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Hearable market Size 2024 | USD 4,269.66 million |
| Industrial Hearable market, CAGR | 14.39% |
| Industrial Hearable market Size 2032 | USD 12,397.78 million |
Growth in this market is driven by rising demand for real-time communication, worker safety, and hands-free operation across industrial sectors. Manufacturers, logistics operators, and energy firms deploy hearables to improve workflow coordination and reduce safety incidents. Smart devices with voice assistance, noise cancellation, and biometric sensors help prevent errors in high-risk environments. Industrial IoT integration and automation also support hearable adoption, with companies prioritizing connected workforce solutions. Regulatory pressure and digital transformation initiatives further push industries to invest in intelligent audio technologies.
North America leads due to early adoption of digital PPE and strict safety compliance across industries. Europe follows with industrial automation and multilingual workforce requirements. Asia Pacific is emerging quickly, backed by strong manufacturing growth and evolving safety norms in China, India, and Southeast Asia. Latin America sees gradual uptake in mining and logistics. The Middle East and Africa show growing interest in connected wearables, especially within oil, gas, and infrastructure sectors where communication and protection remain critical.

Market Insights:
- The Industrial Hearable Market was valued at USD 2,800.00 million in 2018, reached USD 4,269.66 million in 2024, and is projected to attain USD 12,397.78 million by 2032, expanding at a CAGR of 14.39% during the forecast period.
- North America leads with about 39.0% share, driven by early adoption of digital PPE and strict safety norms, followed by Europe at 25.8% due to automation and regulatory enforcement, and Asia Pacific at 25.2% supported by large-scale manufacturing and workforce expansion.
- By end user, manufacturing accounts for roughly 35% of demand, reflecting high communication needs on factory floors, while construction holds about 25% due to safety-driven adoption across active sites.
- Mining and logistics together represent nearly 40%, with mining near 20% from hazardous operations and logistics close to 20% driven by real-time coordination across warehouses and transport hubs.
Market Drivers
Growing Need for Workforce Safety and Real-Time Communication Across High-Risk Work Environments
Industrial sectors such as construction, oil & gas, and manufacturing prioritize worker safety in hazardous zones. The Industrial Hearable Market benefits from devices that provide real-time alerts, voice commands, and SOS features. Workers use smart hearables for instant updates and team coordination without pausing tasks. Noise-canceling and situational awareness technologies reduce accident risks in high-decibel environments. Compliance with workplace safety norms pushes employers to adopt hearables. These tools ensure constant audio connectivity with control rooms. They enable preventive action before critical incidents. Adoption scales with digital safety protocols in regulated industries.
- For instance, the 3M™ PELTOR™ WS™ ProTac XPI headset provides up to 31 dB SNR and meets EN 352 and ANSI S3.19 standards, enabling two-way communication and ambient sound awareness in oil and gas work zones.
Integration of AI-Driven Functionalities to Support Voice-Activated and Hands-Free Operations
Hearables embedded with AI support voice recognition, language translation, and predictive alerts. AI capabilities enhance user interaction by allowing control through voice rather than physical input. It improves task accuracy and reduces manual workload in complex industrial processes. The Industrial Hearable Market grows as enterprises adopt AI to monitor workflows. Smart assistants integrated into hearables optimize task lists and improve time management. Companies deploy these tools for training, support, and procedural guidance in fieldwork. AI also filters environmental noise to deliver clear instructions. Workers gain immediate access to critical data, reducing downtime.
Expansion of Industrial IoT Infrastructure and Integration With Wearable Technologies
The rise of Industrial IoT (IIoT) enables connected operations between machines, systems, and personnel. Hearables serve as frontline access points for IIoT data transmission. These devices capture and relay data like noise exposure, fatigue, or location. The Industrial Hearable Market advances as businesses invest in smart factories. Hearables complement AR glasses and smart helmets in a broader wearable ecosystem. They allow continuous data flow between staff and systems without disrupting workflows. Manufacturers use hearables to track assets and guide maintenance in real time. Their integration improves traceability, efficiency, and site visibility.
High Demand for Seamless Communication in Large-Scale and Decentralized Industrial Sites
Enterprises operating across dispersed work zones need uninterrupted team communication. Traditional radios face signal drops and limited bandwidth in such setups. The Industrial Hearable Market supports this gap with Wi-Fi and Bluetooth-enabled solutions. These tools allow group communications and instant alerts across buildings or off-site locations. It improves emergency coordination and supports fast decision-making. Hearables connect frontline workers to supervisors, reducing information delays. Such systems also support conference calling and multilingual interaction. This boosts collaboration across units, contractors, and on-site teams in real-time.
- For instance, Sensear’s Smart Headsets are deployed in Chevron's LNG facilities, enabling Bluetooth and short-range radio connectivity for effective team coordination across high-noise refinery environments, maintaining speech clarity above 95 dB SPL.
Market Trends
Development of Multifunctional Hearables Supporting Environmental Sensing and Worker Biometrics
Modern hearables now go beyond audio support to track environmental and physiological data. Sensors detect temperature, gas leaks, and noise thresholds in the surroundings. Some devices monitor heart rate, posture, or fatigue to improve worker wellness. The Industrial Hearable Market evolves with growing adoption of sensor-rich wearables. These multifunctional devices enhance safety and help identify early signs of risk. Data collected is used for predictive maintenance and preventive interventions. Employers gain better insights into workforce health and site conditions. Integration of such features transforms hearables into safety intelligence platforms.
Adoption of Edge Computing for Low-Latency Audio Processing in Industrial Hearables
Low-latency communication is vital for critical industrial tasks and emergency response. Edge computing minimizes delays by processing data closer to the source. The Industrial Hearable Market adopts edge-enabled devices for immediate voice transmission and alert execution. It reduces dependency on cloud connectivity in remote zones. Hearables now process voice commands and detect anomalies on-device in real time. This improves responsiveness and user control. Edge-based systems enable private and secure communication in data-sensitive environments. They support real-time translation, smart alerts, and condition monitoring in milliseconds.
- For instance, Sensear’s SM1P series uses embedded digital signal processors (DSPs) to deliver real-time audio processing and voice enhancement with near-zero latency, designed specifically for edge-enabled operations in explosive and high-noise environments like chemical plants and refineries.
Emergence of Lightweight and Ergonomically Designed Hearables for Long-Hour Industrial Usage
Comfort plays a key role in worker acceptance of wearable technologies. Manufacturers focus on ergonomic, sweat-resistant, and lightweight hearables for long shifts. The Industrial Hearable Market shifts toward user-centric designs with adjustable bands and in-ear comfort features. Devices offer high battery life and minimal bulk to reduce fatigue. IP-rated casings protect them in dusty, wet, or high-temperature environments. Enhanced fit improves noise isolation and stability during motion. Compact form factors ensure ease of use in helmets and safety gear. Worker satisfaction influences retention and regular use.
- For instance, ISOtunes' PRO 2.0 Bluetooth earplug headphones offer 10+ hour battery life, an IP67 rating, and heat- and sweat-resistant memory foam tips, meeting OSHA-compliant hearing protection standards while supporting all-day industrial use.
Integration of Location-Based Services and Proximity Alerts in Industrial Hearable Devices
Hearables now include GPS and BLE-based proximity sensing for dynamic asset tracking. These systems help workers avoid restricted zones or high-risk equipment. The Industrial Hearable Market supports geofencing features and proximity warnings to ensure spatial safety. Devices issue alerts when a worker nears hazardous areas or equipment malfunctions. Managers use location data to allocate tasks or monitor workflow bottlenecks. It enhances visibility into workforce movement patterns and dwell times. Integration with RTLS platforms strengthens operational control. Real-time location audio prompts improve field efficiency and safety compliance.
Market Challenges Analysis
Technical Barriers Related to Network Stability, Latency, and Interoperability With Legacy Systems
Reliable communication depends on network strength, which varies across industrial environments. Weak connectivity disrupts real-time voice transmission and sensor alerts. The Industrial Hearable Market faces challenges integrating with legacy equipment and fragmented platforms. Old infrastructure limits data flow between hearables and backend systems. Latency issues in remote areas weaken user experience. Compatibility gaps increase device failure risks and limit feature usage. Enterprises delay adoption where IT ecosystems lack standardization. Integration efforts demand time, customization, and skilled resources. These factors slow procurement and reduce ROI clarity.
User Acceptance, Training Gaps, and Privacy Concerns Around Continuous Monitoring
Employees often resist new technologies without clear benefits or training. Improper usage reduces device utility and operational impact. The Industrial Hearable Market encounters concerns around personal data collection. Workers fear misuse of biometric or location data by employers. Misconceptions about surveillance deter consistent wear. Successful deployment needs change management, usage policies, and trust building. Lack of awareness about safety and productivity gains also limits uptake. Privacy laws vary across regions, complicating compliance. This creates friction between innovation goals and user comfort.
Market Opportunities
Growing Investments in Smart Factory Projects and Digital Workforce Transformation Initiatives
Enterprises invest in digital infrastructure to enhance automation, agility, and efficiency. Hearables are a key enabler in this shift, offering hands-free access to information and voice support. The Industrial Hearable Market benefits from expanding budgets for worker-centric technologies. Demand grows from industries embracing remote supervision, predictive maintenance, and connected operations. Smart factory programs in Asia and Europe boost regional adoption.
Untapped Potential Across Developing Markets With Rapid Industrialization and Workforce Growth
Emerging economies present opportunities where large industrial workforces seek safety and communication tools. The Industrial Hearable Market gains traction as regional firms adopt modern safety norms. Local manufacturers explore affordable and rugged hearable solutions. Government mandates on workplace digitization also support penetration. Growth is likely across Southeast Asia, Latin America, and the Middle East.

Market Segmentation Analysis:
By type, in-ear hearables lead the market due to compact design, high noise isolation, and ease of use in active environments. Over-ear devices remain relevant in heavy-duty sectors requiring full-ear protection and extended comfort. The Industrial Hearable Market supports both formats based on application intensity and safety protocols.
- For example, 3M™ PELTOR™ EEP‑100 Series in‑ear communication earplugs provide ANSI/CE certified hearing protection with integrated voice comms for manufacturing floors, while 3M PELTOR X Series over‑ear headsets deliver full‑ear attenuation for heavy industries like steel, mining, and shipbuilding.
By technology, Bluetooth dominates due to its wide compatibility and wireless convenience. Wi-Fi-based hearables are preferred in high-data environments requiring seamless cloud connectivity. DECT technology sees demand in secure, interference-free communication zones. Other technologies, including NFC and LTE-enabled variants, are gaining attention for niche industrial tasks.
By end-user, manufacturing holds the largest share due to structured work zones and high coordination needs. Construction and mining sectors deploy hearables for on-site alerts and hazard prevention. Logistics and oil & gas sectors use them for fleet coordination, safety monitoring, and voice-led operations under high-risk conditions.
- For example, Honeywell’s Smart Talk industrial headsets are widely adopted in automotive manufacturing lines for real‑time team comms; and Sensear headsets are used in mining operations to maintain clear voice comms amid high‑noise drilling and transport.
By application, industrial wireless communication remains the primary driver, followed by audio/voice applications supporting hands-free task execution. Noise cancellation technology plays a key role in high-decibel settings to prevent hearing loss and enhance focus.
By component, microphones and speakers form the essential audio interface layer. Batteries influence device uptime, especially in long-shift usage. PCBs manage signal processing, integration with sensors, and software control, forming the intelligent core of smart hearables. The Industrial Hearable Market aligns these segments to support diverse industrial operations.
Segmentation:
By Type
- In-Ear
- Over-Ear
By Technology
- Bluetooth
- Wi‑Fi
- DECT
- Others
By End-User
- Manufacturing
- Construction
- Mining
- Logistics
- Oil & Gas
By Application
- Industrial Wireless
- Audio / Voice Application
- Industrial Noise Cancellation
By Component
- Microphone
- Speaker
- Battery
- PCB
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Regional Analysis:
North America
The North America Industrial Hearable Market size was valued at USD 1,103.20 million in 2018 to USD 1,663.43 million in 2024 and is anticipated to reach USD 4,824.00 million by 2032, at a CAGR of 14.4% during the forecast period. North America accounts for the largest regional share, representing approximately 39.0% of the global market in 2024. The region leads due to high adoption across the U.S. manufacturing and energy sectors. Companies prioritize advanced worker safety technologies, integrating real-time audio, noise reduction, and biometric monitoring. The region’s regulatory environment enforces occupational health standards that encourage deployment. U.S.-based companies like 3M and Honeywell drive strong domestic production and R&D. Technological maturity and digital workforce transformation programs support expansion. Demand is further reinforced by smart factory investments and workforce modernization initiatives. Canada and Mexico also contribute to cross-border adoption within trade and logistics operations.
Europe
The Europe Industrial Hearable Market size was valued at USD 750.40 million in 2018 to USD 1,100.60 million in 2024 and is anticipated to reach USD 3,021.99 million by 2032, at a CAGR of 13.6% during the forecast period. Europe held around 25.8% of the global market share in 2024. Industrial automation, strong worker safety mandates, and high labor costs push adoption across Germany, the UK, and France. The EU promotes workplace digitization and industrial IoT, favoring smart hearables as part of safety compliance. Leading industries such as automotive, aerospace, and energy adopt noise-canceling and voice-enabled tools to improve operational efficiency. Multilingual capabilities in hearables cater to Europe’s diverse labor force. France and Italy are emerging with growing demand from construction and logistics. European startups like Orosound and QuietOn strengthen innovation in smart hearing protection. Cross-industry collaborations accelerate market maturity across the continent.
Asia Pacific
The Asia Pacific Industrial Hearable Market size was valued at USD 674.80 million in 2018 to USD 1,075.30 million in 2024 and is anticipated to reach USD 3,450.31 million by 2032, at a CAGR of 15.8% during the forecast period. The region captured nearly 25.2% of the global share in 2024. Rapid industrialization in China, India, and Southeast Asia fuels strong demand. Governments implement safety reforms that encourage wearable adoption in factories, mining, and logistics hubs. Manufacturing growth in automotive, electronics, and consumer goods accelerates deployment. Enterprises seek connected worker solutions to boost productivity in labor-intensive sectors. Japan and South Korea lead in technology integration, supporting feature-rich hearable development. The regional ecosystem benefits from cost-effective production and favorable trade agreements. Asia Pacific’s scale, workforce size, and economic momentum make it a key growth engine for the market.
Latin America
The Latin America Industrial Hearable Market size was valued at USD 181.44 million in 2018 to USD 274.07 million in 2024 and is anticipated to reach USD 739.78 million by 2032, at a CAGR of 13.4% during the forecast period. Latin America represented around 6.4% of the global market in 2024. Brazil and Mexico drive most demand, led by infrastructure, mining, and logistics operations. Regional firms explore hearables for safety compliance and real-time site coordination. Mining-heavy economies adopt advanced audio systems for hazardous operations. Domestic labor laws are evolving, increasing pressure on companies to invest in safety technologies. Industrial zones near ports and special economic zones serve as early adopters. Mid-sized manufacturers explore low-cost, rugged devices suitable for hot and noisy conditions. Demand remains fragmented but rising with increasing awareness and government support.
Middle East
The Middle East Industrial Hearable Market size was valued at USD 58.80 million in 2018 to USD 79.39 million in 2024 and is anticipated to reach USD 187.27 million by 2032, at a CAGR of 11.5% during the forecast period. The region contributed 1.9% to the global market share in 2024. Oil & gas, construction, and logistics sectors drive core demand. GCC countries deploy hearables in refinery zones, offshore rigs, and mega-construction projects. Smart city developments in UAE and Saudi Arabia encourage adoption of connected safety tools. High-risk work zones benefit from biometric alerts, voice control, and isolation from noise hazards. Government-driven infrastructure spending supports gradual expansion. Localization and Arabic language compatibility are key product development areas. Regional adoption is rising but remains concentrated in premium project zones and high-investment corridors.
Africa
The Africa Industrial Hearable Market size was valued at USD 31.36 million in 2018 to USD 76.87 million in 2024 and is anticipated to reach USD 174.43 million by 2032, at a CAGR of 10.2% during the forecast period. Africa held 1.8% of the global market in 2024. Mining and oil-producing countries like South Africa, Nigeria, and Egypt generate most of the demand. Firms invest in hearables to reduce accident rates and meet multinational safety benchmarks. Telecommunications and construction sectors also explore use cases for workforce communication. Low connectivity, budget constraints, and limited awareness hinder wider penetration. Projects funded by international development agencies drive early adoption. Affordable, durable, and energy-efficient devices see better uptake across harsh field environments. The market holds long-term potential with rising infrastructure investment and urban workforce expansion.
Key Player Analysis:
- 3M Company
- Honeywell International Inc.
- Sensear Pty Ltd.
- Sonetics Corporation
- MSA Safety Incorporated
- ISOtunes (Haven Technologies)
- Orosound
- QuietOn
- Cotral Lab
- Silentium
- Eave
- CavCom, Inc.
Competitive Analysis:
The Industrial Hearable Market features a mix of global safety equipment leaders and specialized audio technology firms. Major players such as 3M Company and Honeywell International focus on scale, brand trust, and integrated safety portfolios. It benefits from strong R&D investment, global distribution networks, and long-term enterprise contracts. Mid-sized specialists like Sensear, Sonetics, and MSA Safety emphasize rugged design, secure communication, and sector-specific customization. Niche providers such as Orosound, QuietOn, and Cotral Lab compete through advanced noise control and ergonomic innovation. ISOtunes and CavCom target industrial and defense-grade communication needs with certified products. Competitive intensity remains moderate, driven by product differentiation rather than price wars. Companies pursue growth through new product launches, regional expansion, and partnerships with industrial system integrators. Continuous improvement in battery life, audio clarity, and connectivity defines competitive positioning across key end-user segments
Recent Developments:
- In March 2025, Eargo and hearX, the maker of Lexie hearing aids, completed their merger to form LXE Hearing, backed by $100 million from Patient Square Capital. This first major consolidation in the over-the-counter hearing aid space since FDA regulations in 2022 combines Eargo's virtually invisible designs with Lexie's Bose-powered products and mobile app for improved accessibility in hearing health, potentially extending to industrial applications.
- In January 2025, EssilorLuxottica acquired Pulse Audition to strengthen its presence in the hearing aid sector, advancing innovation in integrated audio solutions. This move supports development of smart hearables with features like real-time noise adaptation and AI-driven safety alerts, aligning with industrial demands for connected PPE in manufacturing and construction.
Report Coverage:
The research report offers an in-depth analysis based on Type, Technology, End-User, Application, and Component. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for smart, connected hearables will grow with deeper integration of industrial IoT infrastructure.
- AI-powered features such as real-time translation and fatigue detection will enhance adoption across critical sectors.
- Regulatory emphasis on occupational safety will accelerate mandatory adoption in hazardous environments.
- Asia Pacific will emerge as the fastest-growing region due to large-scale industrialization and labor safety reforms.
- Device form factors will evolve toward lighter, ergonomic designs to support extended wear across shifts.
- Hearables with edge computing and low-latency voice processing will see greater uptake in high-risk zones.
- Cross-platform compatibility and integration with wearable ecosystems will shape future procurement decisions.
- Industries like mining and oil & gas will adopt biometric monitoring-enabled devices for incident prevention.
- Partnerships between OEMs and software providers will define competitive advantage in workflow solutions.
- Mid-tier manufacturers will enter the market with low-cost, ruggedized models suited for emerging markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Industrial Hearable Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Industrial Hearable Market projected to grow between 2024 and 2032?
Which Industrial Hearable Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Industrial Hearable Market?
Who are the leading companies in the Industrial Hearable Market?
Which region commanded the largest share of the Industrial Hearable Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Industrial Hearable Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Industrial Hearable Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,269.66 million → 2032: USD 12,397.78 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Industrial Hearable Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Industrial Hearable Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Industrial Hearable Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Industrial Hearable Market Drivers
- 3.3 Industrial Hearable Market Restraints & Challenges
- 3.4 Industrial Hearable Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Industrial Hearable Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Industrial Hearable Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Industrial Hearable category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Industrial Hearable Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Industrial Hearable Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Industrial Hearable. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Industrial Hearable Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Industrial Hearable Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Industrial Hearable Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Industrial Hearable (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Industrial Hearable
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Industrial Hearable Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Industrial Hearable Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Industrial Hearable Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Industrial Hearable Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Industrial Hearable Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Industrial Hearable Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Industrial Hearable Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Industrial Hearable Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
