
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Bunker Fuel Market Size 2023 | USD 115842.2 million |
| Bunker Fuel Market CAGR | 5.00% |
| Bunker Fuel Market Size 2032 | USD 179709.27 million |
Market Insights
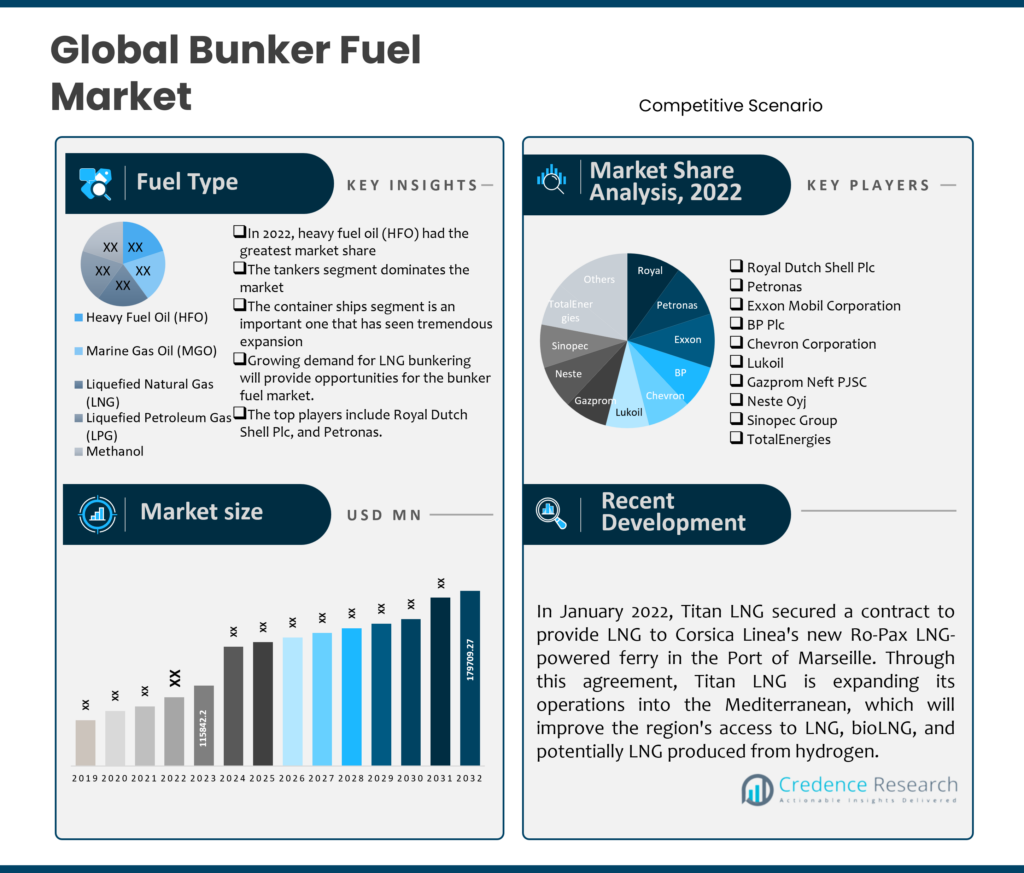
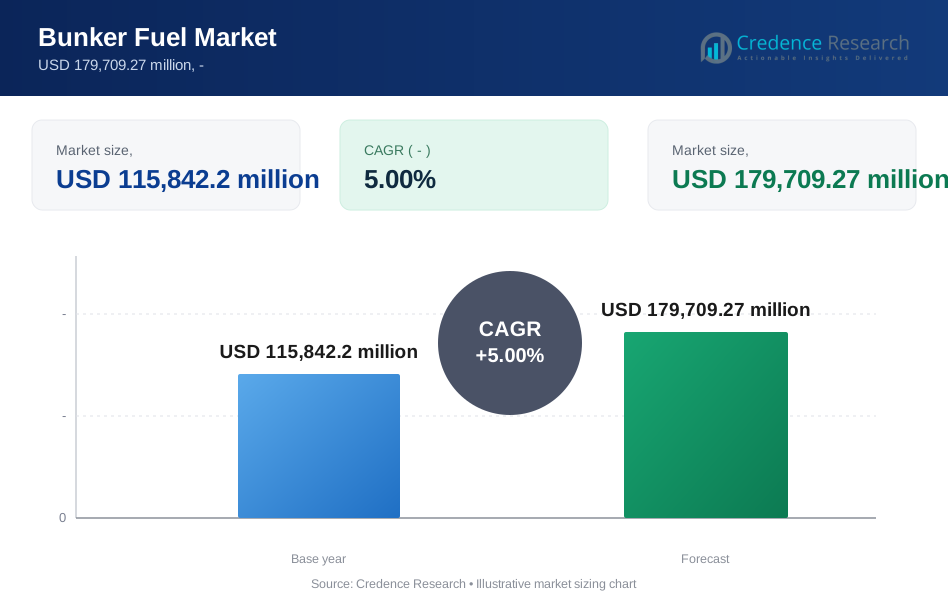
- Between 2024 and 2032, the global market for bunker fuel is projected to rise at a compound annual growth rate (CAGR) of 5.00%, from an estimated USD 115842.2 million in 2023 to USD 179709.27 million in 2032.
- The largest category is heavy fuel oil (HFO). Marine gas oil (MGO), on the other hand, is expected to grow at a strong CAGR.
- The tankers category will expand at a rapid rate of growth.
- North America governed the market for bunker fuel.
- Regarding the market share of bunker fuel, Europe is expected to come second.
- The market for bunker fuel is expected to increase at the fastest rate in the Asia Pacific.
- The market for bunker fuel is supported by rising government programs that support decarbonization, and renewable energy affects the market for conventional bunker fuels.
- Organizations that can set themselves apart from the competition and provide value-added services to clients can facilitate the market expansion of bunker fuel through advancements in energy efficiency technology, emissions reduction strategies, and digital fuel management systems.
Executive Summary
Market Definition
The global market for the purchase and sale of different types of fuel used to power ships and other big marine vessels is known as the bunker fuel market. Ship fuel, often known as bunker fuel or marine fuel, serves the purpose for the transportation of people and cargo across oceans and seas. Other grades and types of bunker fuel are exchanged in this market, including heavy fuel oil, marine diesel oil, and marine gas oil.
Market Overview
The bunker fuel sector is predicted to continue its upward trend between 2024 and 2032, growing at a compound annual growth rate (CAGR) of 5.00%. From its projected USD 115842.2 million in 2023 to USD 179709.27 million in 2032, the market will continue to grow.
The world's fleet grew by an overall 3.04% in 2021 compared to 2020 across all categories with the exception of general cargo ships and other ships, suggesting that international seaborne trade will continue to propel the bunker fuel market in the coming years. Furthermore, a 23% growth from 2020 was predicted for international commerce to reach roughly US$ 28 trillion in 2021. Sea channels are mandatory for international trade. Trade between nations and the world economy both heavily rely on maritime transportation.
A rise in the demand for resources, including coal, steel, iron, and crude oil, is expected to boost production and exploration efforts offshore, which would help the global bunker fuel market expand. The oil and gas industry can purchase bunker fuel and related services from marine bunkering businesses. Deep offshore areas and other marginal oil and gas resources are seeing an increase in exploration activity as a result of technological developments in the industry. The sector's offshore fleet is mostly made up of stand-by boats, anchor handlers, platform supply vessels, exploration vessels, and cable layers. The transition from onshore to offshore exploration has been slow because of the rapid growth in exploratory operations and the spike in demand for new hydrocarbon reserves. Thus, offshore areas presently account for a significant portion of hydrocarbon production. In an effort to increase their market share, bunker oil suppliers are putting money into new bunkering divisions at ports near significant offshore hydrocarbon basins.
Segmentation by Fuel Type
- The heavy fuel oil (HFO) category is the market leader in terms of fuel type. HFO is used in maritime boats not just for propulsion but also for onboard power production. Shipboard generators use HFO to provide power for a range of onboard functions, including HVAC (heating, ventilation, and air conditioning), lighting, navigational equipment, and refrigeration.
- The marine gas oil (MGO) category will exhibit a sizable CAGR during the projected period. Marine gas oil supplies dependable power to emergency generators on board ships in the case of a main engine failure or other operational issues.
- Other fuel types, such as liquefied natural gas (LNG), liquefied petroleum gas (LPG), and methanol, also contribute to the demand for bunker fuel.
Segmentation by Vessel Type
- The finest vessel type is the tanker. Because of the rising demand for chemicals, liquid raw materials, petroleum products, and crude oil, the industry is predicted to increase gradually in the coming years. Specifically, crude oil is a significant energy source that is used to heat buildings, power cars, and produce electricity. The section of the tanker fleet comprises specialist boats intended for the conveyance of LNG and LPG (liquefied Petroleum Gas).
- The container ships category will likely register a significant CAGR during forecasting. This is because metal goods, accessories, and electrical apparatus are among the many items transported by container ships.
- Other vessel types, such as bulk carriers, LNG carriers, passenger vessels, and offshore support vessels (OSVs), also contribute to the demand for bunker fuel.
Segmentation by Region
- North America leads the bunker fuel industry. This is due to the rising demand for bunker fuel from North American countries such as the US, Canada, and Mexico.
- Europe is estimated to rank second in the bunker fuel market size.
- The bunker fuel industry is predicted to flourish rapidly in the Asia Pacific.
- The remaining need for bunker fuel is covered by regions including Latin America, Africa, and the Middle East.
The primary driver of the bunker fuel market's expansion during the projected period is the growing public awareness of the need to save energy and reduce pollution. Due to their numerous uses, including eco-friendly frameworks and high efficiency, highly energy-efficient fuels have been highly sought after. During the projected period, all of these factors have the potential to contribute to market expansion.
Based on projections, North America is anticipated to control the bunker fuel market. The primary region for offshore oil extraction operations is North America, where there is a stronger emphasis on the development of offshore wind projects. Interregional commerce and other value-added services are driving the expansion of the bunker fuel industry in North America. The market for bunker fuel is heavily influenced by North America, whose main ports on the Gulf, West, and East coasts act as essential entry points for trade with the region. Demand for cleaner fuels in the region is rising, especially for those who must adhere to emissions regulations.
Throughout the projected period, Asia Pacific's bunker fuel market is anticipated to expand quickly. The need for bunker fuels is being driven by the rapid economic expansion occurring in countries such as China, India, and Southeast Asia, which is leading to a rise in marine activities. The market is expanding as a result of the existence of important maritime routes, a sizable shipbuilding industry, and the rise in containerization. In addition, Asia Pacific is seeing developments in greener and substitute bunker fuels that are in line with the objectives of environmental sustainability.
Key Highlights of the Report
The global bunker fuel market is segmented by fuel type, vessel type, and region. The heavy fuel oil (HFO) category is the market spearhead in terms of fuel type, and the tankers are the top vessel type. The bunker fuel market is expanding mostly in North America.
The sulfur content of marine fuels used worldwide must be significantly reduced by the IMO 2020 standards, from 3.5% to 0.5% sulfur. Low-sulfur bunker fuels, such as compliant marine gas oil (MGO) and very low-sulfur fuel oil (VLSFO), are becoming more and more popular due to this legal need. These fuels are necessary to comply with the new sulfur cap. As shipping firms and vessel operators work to assure compliance with the new sulfur limitations, the implementation of IMO 2020 regulations has resulted in a rise in demand for compliant bunker fuels. The market for bunker fuel is expanding as a result of this rising demand, especially from producers of low-sulfur alternatives.
North America is expected to account for the largest bunker fuel market globally. The oil and gas production in North America, especially in the US and Canada, has surged recently, increasing the supply of crude oil feedstocks that may be refined into bunker fuels. Because there are so many domestic energy resources available, the regional bunker fuel industry is expanding. It is also anticipated that the market will develop at the fastest rate in the Asia Pacific region. This is due to the major centers of commodity consumption being present in the Asia Pacific. However, the presence of developing economies like those in Thailand, India, China, Japan, and others is crucial to marine trade, which raises the need for bunker fuel in the region.
Which Key Factors Are Driving The Global Bunker Fuel Market?
The bunker fuel industry is expanding due to the demand for goods and transportation, which is driven by economic expansion. This, in turn, increases the consumption of bunker fuel. Increasing trade activity requires more shipping, which raises the need for bunker fuel.
What Are The Main Challenges Confronting The Global Bunker Fuel Market?
The bunker fuel industry faces a number of challenging obstacles, such as high initial investment costs and infrastructure, as well as technological obstacles to the adoption of cleaner fuel technologies, such as LNG bunkering infrastructure.
What Market Opportunities Exist For Bunker Fuel Globally?
The market for bunker fuel is expanding due to the growing number of trade volumes and shipping activity in expanding marine markets, notably in Asia-Pacific and Latin America. This provides potential for suppliers to develop and sell compliant fuel mixes in light of the trend towards low-sulfur bunker fuels.
Market Drivers
Bunker Fuel is Widely Used in the Power and Shipping Industries
Bunker fuel is widely used in the shipping sector. Large, high-performance vessels that are in great demand, especially when carrying a sizable number of passengers, are the main users of bunker fuel. Because of their speed and cargo capacity, they are the favored vessels. Because of its high viscosity, bunker fuel is frequently used by cruise ships, oil tankers, container ships, and other ships.
Bunker fuel is used to heat buildings and produce power. It is also utilized for power generation on bigger boats. Because these boats can carry a lot more weight than other forms of transportation, there is a greater need for bunker fuel while refilling.
Market Restraints
High Prices of Bunker Fuel
The combination of crude oil and residual fuel in bunker fuel will be a significant obstacle to the market's rate of expansion. Issues that would hinder the industry's expansion include the present price of crude oil and the increasing expenses associated with its transportation.
Certain shipping routes may become economically unprofitable due to high bunker fuel prices, particularly those with longer journeys or lower freight rates. This can cause problems with route optimization and a decrease in trade flows. The high-cost difference between low-sulfur or LNG and traditional bunker fuels may discourage shipping companies from making environmentally friendly investments, thereby impeding the development of sustainable shipping practices.
Opportunities
Growing Demand for LNG Bunkering
Bunkering with LNG is a more environmentally friendly option for shipping firms to adhere to strict emissions and sulfur criteria set by the International Maritime Organization (IMO). This demand is triggered by the goal to reduce pollution from greenhouse gases and their effect on the environment. Sulfur oxides (SOx), nitrogen oxides (NOx), and particulate matter are among the pollutants that LNG is known to produce in less quantities than traditional maritime fuels. The preference for LNG bunkering as a means of lowering the carbon footprint of marine transportation is expanding as environmental concerns continue to rise. The industry for LNG bunkering is expanding due to the growing availability of bunkering infrastructure, such as terminals and tankers. Market accessibility and expansion are being supported by investments in LNG infrastructure at major ports and important sites throughout the globe.
Competitive Landscape
Key Players
In the highly competitive global bunker fuel market, there are a number of significant rivals. A few of the top market players are shown below, together with their respective market shares:
- Royal Dutch Shell Plc
- Petronas
- Exxon Mobil Corporation
- BP Plc
- Chevron Corporation
- Lukoil
- Gazprom Neft PJSC
- Neste Oyj
- Sinopec Group
- TotalEnergies
- Others
To stay competitive, these businesses prioritize product innovation, expanding their distribution networks, and completing mergers and acquisitions.
The biggest vendors in the global bunker fuel market consistently strive to keep one step ahead of the competition by creating cutting-edge ideas and goods.
In January 2022, An agreement for cooperation was signed by the LNG Alliance and the New Mangalore Port Trust to build an LNG port terminal with an initial capacity of 4 million tons and the possibility for an annual extension to 8 million tons. This port, which would be the first in India, will offer LNG bunkering for ships.
In December 2021, Minerva Bunkering, a subsidiary of Mercuria Energy Group, started supplying marine fuels to the ports of Yanbu and Jeddah in Saudi Arabia's Red Sea area. The partnership between the Saudi Arabian Energy Ministry and Aramco Trading is anticipated to increase the company's visibility in the expanding regional shipping market.
How are Companies Performing in the Bunker Fuel Market?
The substantial performance of companies in the bunker fuel market can be attributed to some noteworthy reasons. Bunker fuel companies endeavor to increase their global reach and enhance their current portfolio by upholding product standards, enforcing quality control, and fortifying supply chain management systems.
Reputable companies are spending a lot of money to reach a wider audience worldwide. Several strategies are implemented by companies to expand their influence, including partnerships, mergers and acquisitions, collaborations, and more. For example, Titan LNG and Brittany Ferries established a long-term bunkering deal in May 2022 for the provision of LNG and Liquefied Bio Methane (LBM) to two new LNG-fueled hybrid Ro-Pax vessels that Brittany Ferries plans to run between England and France starting in 2025. These ships are anticipated to service well-traveled routes that link Ouistreham and Saint-Malo with Portsmouth. Additionally, Titans intends to provide gasoline to both ships in conjunction with SIMOPS (simultaneous operations) during routine cargo operations.
In order to reduce greenhouse gas emissions, major companies in the bunker fuel market are launching programs with their affiliated businesses. For example, In an effort to lower greenhouse gas emissions, Neste OYJ and Nordic Marine Oil launched a new marine fuel pilot program in Scandinavia in May 2022. The fuel is called Neste Marine 0.1 Co-processed. The fuel is based on a variety of low-sulfur marine fuels (Neste MGO DMA and Neste MDO DMB) with a sulfur concentration of less than 0.1%, known as Neste Marine 0.1 low-sulfur marine fuel.
Summary of Key Findings
- Variations in trade patterns, vessel sizes, and shipping routes influence bunker fuel usage patterns and are the primary cause of the demand for the bunker fuel market.
- The market is segmented by fuel type, vessel type, and region.
- The heavy fuel oil (HFO) category is anticipated to develop at a greater CAGR over the forecast period.
- The largest vessel type category is the tankers.
- North America is leading market development; the market is highly competitive with key players including Royal Dutch Shell Plc, Petronas, Exxon Mobil Corporation, BP Plc, Chevron Corporation, Lukoil, Gazprom Neft PJSC, Neste Oyj, Sinopec Group, and TotalEnergies, and Others.
Future Outlook
- The bunker fuel industry is expected to increase significantly in North America, and its outlook is positive worldwide.
- Tax credits, subsidies, and incentives for renewable energy programs influence bunker fuel market dynamics.
- Sulfur content limitations and other strict environmental requirements present compliance challenges for ship operators and bunker fuel suppliers.
- Major organizations must develop new products, reach a larger audience, and maintain competitive pricing to stay ahead of other businesses.
How the Credence Research Bunker Fuel Market Report Can Help CXOs
The Credence Research Bunker Fuel Market Report provides CXOs with an extensive market overview and comprises the following:
- Market size and growth forecast: The study offers comprehensive market estimations for bunker fuel globally, broken down by fuel type, vessel type, and region. In addition, projections for the market through 2032 based on significant drivers and trends are included.
- Market segmentation: The bunker fuel market is divided into segments by fuel type, vessel type, and region in the research report. CXOs are given a detailed grasp of the market and the potential inside each sector due to this segmentation.
- Competitive landscape: The study report provides a thorough analysis of the leading businesses in the bunker fuel sector, together with details on their revenue streams, product lines, and business strategies. This information can help CXOs assess and identify their competitors.
- Key trends and drivers: The study report analyzes and highlights the key developments and elements driving the bunker fuel market. CXOs can utilize this information to make well-informed choices regarding their plans and investments.
The Credence Research Bunker Fuel Market Report provides CXOs with insights that they may utilize to:
- Identify growth opportunities: This analysis is likely to help CXOs find fresh growth prospects in the bunker fuel sector. For example, the research recognizes the increasing requirement for bunker fuel from the shipping industry as a crucial opportunity.
- Make informed investment decisions: The study aids CXOs in making informed decisions about bunker fuel. For example, it delivers information on the key variables to consider while picking bunker fuel solutions and evaluating suppliers.
- Develop competitive strategies: CXOs can utilize the research report to establish competitive strategies for their bunker fuel firms. The study paper explores the primary tactics employed by bunker fuel providers to set themselves apart from their rivals.
- Track market developments: By tracking market advancements, this research report could assist CXOs in remaining ahead of the curve. For example, it provides information about the latest advancements and patterns in the bunker fuel industry.
The Credence Research Bunker Fuel Market Report is helpful for CXOs who want to learn more about the market and identify potential opportunities.
Segmentation
-
By Fuel Type
- Heavy Fuel Oil (HFO)
- Marine Gas Oil (MGO)
- Liquefied Natural Gas (LNG)
- Liquefied Petroleum Gas (LPG)
- Methanol
-
By Vessel Type
- Container Ships
- Bulk Carriers
- Tankers
- LNG Carriers
- Passenger Vessels
- Offshore Support Vessels (OSVs)
-
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
- North America
Adjacent Markets
Several adjacent markets in the bunker fuel market have high revenue growth opportunities. The key adjacent markets for the bunker fuel market -
|
Adjacent Markets |
||
| Marine Lubricants | Fuel Additives and Treatments | Marine Transportation |
| Exhaust Gas Cleaning Systems (Scrubbers) | Emissions Monitoring and Control Systems | Port Services and Logistics |
| LNG Bunkering | Bunkering Infrastructure | Alternative Marine Fuels |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of International Seaborne Trade
The continued growth in global trade volumes, especially in commodities and manufactured goods, is increasing the demand for marine transportation, directly driving the need for bunker fuel to power the expanding global fleet.
Regulatory Shift Toward Low-Sulfur and Cleaner Fuels
Implementation of IMO 2020 regulations and stricter emissions standards are accelerating the adoption of low-sulfur bunker fuels and alternative marine fuels, creating new demand segments and driving market growth.
Growth in Offshore Exploration and Production
Rising offshore oil and gas exploration activities, particularly in North America and Asia Pacific, are increasing the number of support and supply vessels, thereby boosting bunker fuel consumption in these regions.
Technological Advancements in Fuel Efficiency and Emissions Reduction
Innovations in digital fuel management, energy efficiency technologies, and emissions reduction strategies are enabling shipping companies to optimize fuel usage, supporting market expansion as operators seek to comply with environmental mandates.
Development of LNG Bunkering Infrastructure
Investments in LNG bunkering terminals and supply chains at major ports are facilitating the transition to cleaner marine fuels, opening new opportunities for suppliers and expanding the overall bunker fuel market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much does the global market currently hold for bunker fuel?
What is the bunker fuel market's projected growth rate between 2024 and 2032?
What is the most significant market segment in terms of fuel type?
Regarding the vessel type, which market category is in the lead?
Which fuel type is anticipated to grow at the fastest rate throughout the projected period?
In which region is the market for bunker fuel expanding?
Who are the main players in the global bunker fuel industry?
Which market factors are the primary drivers of the bunker fuel industry?
What main market challenges prevent the growth of the bunker fuel sector?
What are the main market opportunities for the bunker fuel sector?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel Type
- 1.2.1 Heavy Fuel Oil (HFO)
- 1.2.2 Marine Gas Oil (MGO)
- 1.2.3 Liquefied Natural Gas (LNG)
- 1.2.4 Liquefied Petroleum Gas (LPG)
- 1.2.5 Methanol
- 1.3 By Vessel Type
- 1.3.1 Container Ships
- 1.3.2 Bulk Carriers
- 1.3.3 Tankers
- 1.3.4 LNG Carriers
- 1.3.5 Passenger Vessels
- 1.3.6 Offshore Support Vessels (OSVs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 115,842.2 million → 2032: USD 179,709.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bunker Fuel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bunker Fuel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bunker Fuel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bunker Fuel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bunker Fuel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bunker Fuel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bunker Fuel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bunker Fuel Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 115,842.2 million → 2032: USD 179,709.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bunker Fuel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Heavy Fuel Oil (HFO)
- 12.3.7.2 Marine Gas Oil (MGO)
- 12.3.7.3 Liquefied Natural Gas (LNG)
- 12.3.7.4 Liquefied Petroleum Gas (LPG)
- 12.3.7.5 Methanol
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vessel Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Container Ships
- 12.4.7.2 Bulk Carriers
- 12.4.7.3 Tankers
- 12.4.7.4 LNG Carriers
- 12.4.7.5 Passenger Vessels
- 12.4.7.6 Offshore Support Vessels (OSVs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bunker Fuel Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Bunker Fuel Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Bunker Fuel Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Royal Dutch Shell Plc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Petronas
- 17.4 Exxon Mobil Corporation
- 17.5 BP Plc
- 17.6 Chevron Corporation
- 17.7 Lukoil
- 17.8 Gazprom Neft PJSC
- 17.9 Neste Oyj
- 17.10 Sinopec Group
- 17.11 TotalEnergies
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

