
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Compressed Natural Gas (CNG) Market Size 2024 | USD 89113 million |
| Compressed Natural Gas (CNG) Market, CAGR | 3.5% |
| Compressed Natural Gas (CNG) Market Size 2032 | USD 121451.9 million |
Market Overview:
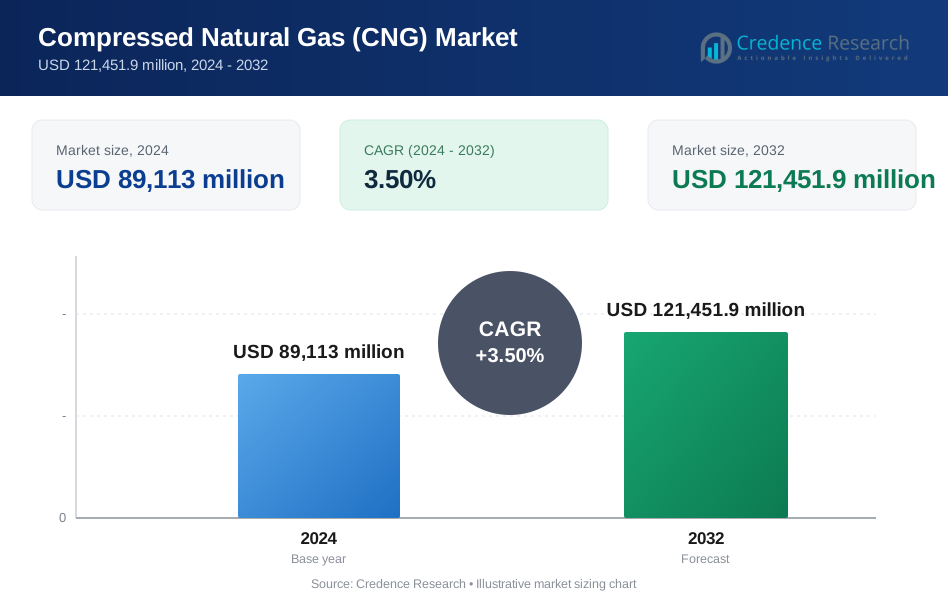
The Compressed Natural Gas (CNG) Market is projected to grow from USD 89113 million in 2024 to an estimated USD 121451.9 million by 2032, with a compound annual growth rate (CAGR) of 3.5% from 2024 to 2032.
Several factors contribute to the robust growth of the CNG market. Firstly, the rising environmental concerns and stringent emission regulations are prompting industries and consumers to seek cleaner fuel options. CNG, being a cleaner alternative to traditional fuels like gasoline and diesel, emits fewer pollutants, making it an attractive choice for reducing air pollution and greenhouse gas emissions. Secondly, the economic benefits associated with CNG are compelling. It offers lower fuel costs compared to petrol and diesel, leading to significant savings for consumers and businesses alike. Additionally, advancements in CNG vehicle technology and infrastructure development are enhancing the efficiency and convenience of CNG usage, further driving its adoption.
Regionally, Asia-Pacific holds a dominant position in the global CNG market. Countries like India and China are leading the way in adopting CNG as a primary fuel source for transportation. In India, for instance, the government has been actively promoting the use of CNG through various initiatives, including the establishment of CNG stations and offering incentives for CNG vehicles. Similarly, China's commitment to reducing urban air pollution has led to increased investments in CNG infrastructure and vehicles. North America, particularly the United States, also presents significant growth opportunities due to the availability of natural gas resources and supportive policies encouraging the use of alternative fuels. Europe is witnessing steady growth, driven by the European Union's stringent emission norms and the adoption of CNG in public transportation systems. However, challenges such as the limited number of refueling stations and the high initial cost of CNG vehicles need to be addressed to accelerate market penetration in these regions
Market Insights:
- The Compressed Natural Gas (CNG) Market is projected to grow from USD 89,113 million in 2024 to USD 121,451.9 million by 2032, registering a CAGR of 3.5% during this period.
- Rising environmental concerns and stringent emission regulations drive demand for CNG, a cleaner alternative that emits fewer pollutants compared to gasoline and diesel.
- Economic advantages, including lower fuel costs and government incentives such as subsidies and tax rebates, promote CNG adoption across transportation and industrial sectors.
- Technological advancements in vehicle engines, storage tanks, and refueling infrastructure improve performance, safety, and convenience, encouraging wider market penetration.
- Supportive government policies aimed at energy security and reducing oil dependency boost the market, with national strategies favoring domestic natural gas resources.
- Limited refueling infrastructure and uneven geographic coverage create challenges, especially in developing regions, restricting consumer confidence and vehicle adoption.
- High initial vehicle costs and technical limitations, such as reduced cargo space and maintenance complexity, impede consumer acceptance, requiring ongoing innovation and cost reduction.
Market Drivers:
Rising Environmental Concerns and Stringent Emission Regulations Driving Demand for Cleaner Fuel Alternatives
One of the primary drivers of the Compressed Natural Gas (CNG) Market is the increasing global emphasis on environmental sustainability. Governments worldwide enforce strict emission standards to curb pollution caused by traditional fossil fuels such as gasoline and diesel. CNG emits significantly lower levels of harmful pollutants, including nitrogen oxides, particulate matter, and carbon dioxide, which makes it an attractive alternative for reducing urban air pollution and greenhouse gas emissions. It supports efforts to combat climate change by providing a cleaner fuel option for transportation and industrial use. This environmental advantage encourages both private and public sectors to shift towards CNG-powered vehicles and infrastructure. Consequently, industries and fleet operators are adopting CNG to comply with regulations and enhance their corporate social responsibility credentials. Consumer awareness about the environmental impact of fuel choices also plays a vital role in expanding market demand.
Cost-Effectiveness and Economic Incentives Promoting Adoption Across Transportation and Industrial Sectors
Economic factors significantly influence the growth of the Compressed Natural Gas (CNG) Market. CNG offers lower fuel costs compared to conventional fuels, providing a cost-effective solution for both commercial and private users. The reduced expenditure on fuel helps fleet operators, public transportation providers, and individual vehicle owners achieve substantial savings over time. Several governments promote CNG adoption by offering financial incentives, such as subsidies, tax rebates, and reduced registration fees for CNG vehicles. These incentives lower the upfront investment and operational expenses, encouraging a broader acceptance of CNG technology. The stable pricing of natural gas compared to volatile crude oil prices further enhances its economic appeal. Companies that incorporate CNG in their operations benefit from improved fuel cost predictability and enhanced profitability. This cost advantage supports increased investments in CNG infrastructure and vehicle manufacturing.
Technological Advancements Enhancing Vehicle Performance and Infrastructure Development Facilitating Market Expansion
Continuous improvements in CNG vehicle technologies drive the market forward by addressing previous limitations related to performance and convenience. Manufacturers are developing advanced engine systems that optimize fuel efficiency and power output while maintaining low emissions. Innovations in storage tank design and refueling mechanisms improve safety and reduce vehicle weight, thereby increasing driving range and user experience. The expansion of refueling infrastructure, including the construction of more CNG stations globally, supports widespread adoption. Governments and private entities invest in establishing a robust network to alleviate range anxiety and improve accessibility. Efficient maintenance and repair services for CNG vehicles also encourage consumer confidence. These technological and infrastructural advancements collectively contribute to the growing feasibility and appeal of CNG vehicles across various regions.
- For instance, Tata’s Altroz iCNG features smart CNG kits equipped with leak sensors and automatic shut-off valves, which immediately halt gas flow upon detecting leaks, greatly enhancing safety.
Strategic Government Policies and Global Energy Security Concerns Supporting Market Growth
Governments play a critical role in shaping the trajectory of the Compressed Natural Gas (CNG) Market through supportive policies and initiatives. National and regional authorities implement strategies to reduce dependence on imported oil by promoting domestically available natural gas resources. It contributes to energy security and diversifies the energy mix, mitigating risks associated with global oil price fluctuations. Regulatory frameworks mandate or encourage the use of cleaner fuels in public transportation and commercial fleets, accelerating CNG adoption. Public awareness campaigns and partnerships with industry stakeholders foster market development. International commitments to reduce carbon footprints and meet climate goals also align with policies favoring CNG. These coordinated efforts create a favorable environment for investment and innovation, ensuring sustainable market expansion.
- For instance, Clean Energy Fuels’ 2023 expansion of RNG stations directly supports U.S. state and federal mandates for lower carbon transportation fuels, leveraging RNG to achieve carbon-negative fleet operations.
Market Trends:
Expansion of CNG Vehicle Adoption in Commercial and Public Transportation Sectors
A prominent trend in the Compressed Natural Gas (CNG) Market involves the increasing integration of CNG-powered vehicles within commercial fleets and public transportation systems. Fleet operators, including logistics companies and city transit authorities, recognize the benefits of reduced operational costs and lower emissions. This trend accelerates the replacement of diesel-powered buses, trucks, and taxis with CNG alternatives. Governments encourage this transition through mandates and subsidies, prompting large-scale deployments in urban centers worldwide. The enhanced focus on sustainability and clean mobility solutions supports steady growth in demand for CNG vehicles. Manufacturers respond by expanding their product portfolios to include a wider range of CNG-compatible commercial vehicles. This shift contributes to improving air quality and reducing the carbon footprint in densely populated areas.
- For instance, Delhi Transport Corporation (DTC) operates the world’s largest fleet of CNG-powered buses, with over 3,800 CNG buses in service as of 2023, according to DTC and Delhi government sources. Tata Motors is a key supplier to this fleet, providing Starbus CNG models that are equipped with advanced emission control systems and comply with Bharat Stage VI emission standards.
Advancements in CNG Storage and Refueling Technologies Improving User Convenience and Safety
Technological innovation in storage and refueling infrastructure significantly shapes the trajectory of the Compressed Natural Gas (CNG) Market. New developments enhance tank designs, offering higher capacity with reduced weight and improved durability. These innovations extend vehicle driving ranges and contribute to overall system safety. Automated refueling stations equipped with faster dispensing capabilities reduce wait times and improve user experience. The integration of digital monitoring systems allows real-time tracking of fuel levels and maintenance needs, increasing reliability. Industry participants invest heavily in expanding refueling networks to address accessibility challenges, particularly in emerging markets. These technological strides lower barriers to adoption by mitigating concerns about refueling convenience and vehicle performance.
Growing Emphasis on Sustainable and Renewable Natural Gas Sources Complementing CNG Usage
The Compressed Natural Gas (CNG) Market increasingly embraces sustainable alternatives such as renewable natural gas (RNG) derived from organic waste and biogas sources. It helps reduce reliance on fossil-based natural gas and further lowers greenhouse gas emissions. Several countries prioritize RNG integration into existing CNG infrastructure through supportive policies and pilot projects. The combination of CNG and RNG fuels aligns with broader climate change mitigation strategies and circular economy principles. Industry stakeholders collaborate to develop cost-effective methods for RNG production and distribution. This trend promotes environmental responsibility while ensuring fuel supply diversification. The growing acceptance of RNG enriches the market’s appeal among environmentally conscious consumers and regulatory bodies.
Strategic Collaborations and Partnerships Driving Innovation and Market Penetration
Companies in the Compressed Natural Gas (CNG) Market pursue strategic collaborations to enhance product offerings and accelerate market reach. Partnerships between vehicle manufacturers, fuel suppliers, and technology providers facilitate innovation in CNG systems and infrastructure. Collaborative efforts support research and development focused on improving fuel efficiency, emission controls, and vehicle compatibility. Joint ventures help expand refueling station networks and promote standardization of components and safety protocols. Alliances with government agencies enable alignment with regulatory frameworks and access to incentive programs. These cooperative initiatives strengthen market dynamics by leveraging combined expertise and resources. They create new opportunities for growth, especially in emerging regions with untapped potential.
- For instance, alliance between Scania and Gasum, have expanded refueling station networks and supported the rollout of CNG-compatible commercial vehicles in new regions.
Market Challenges Analysis:
Limited Refueling Infrastructure and Geographic Accessibility Constraints Hindering Market Expansion
One of the significant challenges facing the Compressed Natural Gas (CNG) Market is the limited availability and uneven distribution of refueling stations. Many regions, especially in developing countries, lack a sufficient network of CNG fueling points, which restricts consumer adoption and commercial fleet integration. This scarcity creates range anxiety among potential users, discouraging investment in CNG vehicles. High costs and lengthy timelines associated with establishing new refueling infrastructure further slow market growth. The absence of standardized fueling protocols in some areas complicates interoperability and service consistency. Infrastructure development requires coordinated efforts between governments, private investors, and industry stakeholders to ensure comprehensive coverage. Until the network expands and becomes more accessible, the market will face constraints in achieving widespread penetration.
- For instance, as of 2024, the United States had approximately 900 public CNG fueling stations, according to the U.S. Department of Energy, which is significantly lower than the number of gasoline stations nationwide and leads to limited route flexibility for commercial fleets.
High Initial Vehicle Costs and Technical Limitations Affecting Consumer Acceptance and Industry Adoption
The upfront cost of CNG-powered vehicles presents a notable barrier within the Compressed Natural Gas (CNG) Market. CNG vehicles generally have higher purchase prices than conventional gasoline or diesel models due to specialized components and fuel storage systems. This price premium discourages many individual consumers and small businesses from making the switch, despite lower operational expenses over time. Technical limitations, such as reduced cargo space due to bulky fuel tanks and slightly lower engine power in some applications, affect user preferences. Maintenance complexity and a shortage of trained technicians also challenge service quality and reliability. These factors collectively reduce the immediate appeal of CNG vehicles compared to traditional alternatives. Overcoming these hurdles requires continued technological advancements, cost reduction strategies, and consumer education to improve market confidence and acceptance.
Market Opportunities:
Expansion of CNG Infrastructure and Urban Fleet Modernization Creating Growth Potential
The expansion of CNG refueling infrastructure in emerging economies presents significant opportunities for the Compressed Natural Gas (CNG) Market. Governments and private entities invest in establishing new fueling stations to support urban fleet modernization programs. Public transportation systems, including buses and taxis, increasingly shift toward CNG to meet emission reduction targets and reduce operational costs. It creates demand for reliable fuel supply and related services, fostering market growth. Investments in infrastructure enhance consumer confidence and encourage private vehicle owners to adopt CNG technology. This expansion also enables penetration into previously underserved regions, widening the market base. The ongoing modernization of commercial fleets offers substantial growth avenues for vehicle manufacturers and fuel providers.
Technological Innovations and Renewable Natural Gas Integration Enhancing Market Prospects
Technological advancements in vehicle design and fuel management systems offer promising opportunities for the Compressed Natural Gas (CNG) Market. Improved engine efficiency, lightweight storage solutions, and enhanced safety features increase the attractiveness of CNG vehicles. The integration of renewable natural gas (RNG) into existing CNG infrastructure supports sustainability goals and appeals to environmentally conscious consumers and regulators. It opens new avenues for collaboration between waste management and energy sectors to produce cleaner fuels. Growing interest in decarbonization policies globally drives investments in RNG projects, further expanding market potential. Innovation and diversification of fuel sources strengthen the market’s long-term viability and competitiveness.
Market Segmentation Analysis:
The Compressed Natural Gas (CNG) Market segments offer diverse growth avenues driven by evolving consumer preferences and industrial needs.
By vehicle type, passenger cars and commercial vehicles dominate demand due to increasing environmental regulations and rising fuel efficiency standards. Two-wheelers and three-wheelers also contribute significantly, especially in densely populated regions where cost-effective and cleaner transport options are prioritized. Buses benefit from government initiatives targeting public transportation emissions reduction, supporting fleet transitions to CNG.
By Cylinder type segmentation highlights single, twin, and multi-cylinder configurations. Single-cylinder tanks serve smaller vehicles, while twin-cylinder setups optimize space and capacity, popularized in models like the Tata Nexon iCNG. Multi-cylinder systems cater to commercial vehicles requiring extended driving ranges and higher fuel volumes, facilitating broader adoption across fleet operators.
By Source-wise, the market includes refinery gas, associated gas, and non-associated gas. Refinery gas offers a reliable supply from processing plants, whereas associated and non-associated natural gas sources ensure diversified feedstock availability. This segmentation supports supply chain stability and regional resource optimization.
By Application segments span transportation, industrial use, residential use, and power generation. Transportation remains the largest consumer, driven by fleet conversions and private vehicle adoption. Industrial applications leverage CNG for cleaner energy in manufacturing and processing. Residential use, though smaller, gains traction for heating and cooking in urban areas seeking sustainable alternatives. Power generation utilizes CNG in gas-fired plants, offering efficient and lower-emission electricity production. This multi-sector usage underlines the comprehensive role of CNG in global energy transition efforts.
Segmentation:
By Vehicle Type:
- Passenger Cars
- Commercial Vehicles
- Two-Wheelers
- Three-Wheelers
- Buses
By Cylinder Type:
- Single Cylinder
- Twin Cylinder
- Multi Cylinder
By Source
- Refinery
- Associated Gas
- Non-Associated Gas
By Application:
- Transportation
- Industrial Use
- Residential Use
- Power Generation
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Asia-Pacific Region Dominates the Compressed Natural Gas (CNG) Market with Significant Growth Momentum
The Asia-Pacific region leads the Compressed Natural Gas (CNG) Market, accounting for approximately 40% of the global market share in 2024. Countries such as India and China drive this dominance through aggressive adoption of CNG in transportation and industrial sectors. Government initiatives in these countries focus on expanding CNG infrastructure and promoting environmentally friendly fuels to tackle urban pollution. India’s extensive CNG vehicle programs and network of refueling stations exemplify the region’s commitment to clean energy solutions. Rising urbanization, increased demand for public transportation, and regulatory support contribute to sustained market growth. Manufacturers and service providers actively target this region to capitalize on expanding demand and supportive policies. The region’s growing middle class also fuels consumer interest in cost-effective and eco-friendly fuels.
North America Exhibits Steady Growth Driven by Energy Security and Environmental Regulations
North America holds around 30% of the Compressed Natural Gas (CNG) Market share, driven primarily by the United States and Canada. The region benefits from abundant natural gas resources and established infrastructure, facilitating widespread CNG adoption. Federal and state regulations encouraging emission reductions in transportation sectors create favorable market conditions. Fleet operators in logistics, public transportation, and commercial sectors increasingly transition to CNG vehicles to reduce costs and environmental impact. Investments in technology advancements and refueling networks further support market expansion. The region also leads in developing renewable natural gas (RNG) integration into the existing CNG supply chain. Industry collaboration between government bodies and private enterprises promotes innovation and policy compliance, reinforcing market growth.
Europe Sees Moderate Expansion Fueled by Stringent Emission Norms and Public Transit Initiatives
Europe commands approximately 20% share of the Compressed Natural Gas (CNG) Market, reflecting steady adoption across key countries such as Germany, Italy, and the United Kingdom. The European Union’s strict emission standards and climate action plans encourage the use of cleaner fuels in transportation and municipal services. Public transit authorities invest in CNG-powered buses and fleet vehicles to meet sustainability goals and improve urban air quality. The region focuses on integrating CNG with biogas to enhance environmental benefits and energy diversification. Infrastructure development remains a priority, with increasing refueling stations supporting growing demand. Consumer awareness and government incentives contribute to gradual market penetration. Despite some challenges related to initial vehicle costs, Europe maintains a positive outlook for CNG adoption in the coming years.
Key Player Analysis:
- Centrica
- Chevron Corporation
- Clean Energy Fuels Corp.
- ConocoPhillips
- Duke Energy
- ExxonMobil Corporation
- Fortis Inc.
- FortisBC
- GasTerra
- Gazprom
- Indraprastha Gas Limited
- JW Power Company
- National Grid
- National Iranian Gas Company
- Occidental Petroleum Corporation
- Octopus Energy
- Royal Dutch Shell Plc
- Sempra Energy
- TotalEnergies
Competitive Analysis:
The Compressed Natural Gas (CNG) Market features a competitive landscape dominated by key players focusing on innovation, strategic partnerships, and regional expansion. Leading companies such as Cummins Inc., Westport Fuel Systems, and Clean Energy Fuels Corporation continuously invest in research and development to improve engine efficiency and fuel storage technologies. It emphasizes expanding refueling infrastructure and vehicle offerings to meet growing demand. Collaborations between manufacturers, fuel suppliers, and government agencies enhance market penetration and regulatory compliance. Companies also focus on cost reduction and safety enhancements to increase user adoption. The competitive environment drives continuous product improvement and geographic diversification. Firms actively pursue emerging markets in Asia-Pacific and Latin America, leveraging favorable government policies. Market leaders maintain their positions through innovation, strategic alliances, and an increasing focus on sustainable and renewable natural gas integration, ensuring long-term growth and resilience in the evolving energy landscape.
Recent Developments:
- In February 2025, Iran inaugurated 12 new CNG stations across six provinces, marking a continued expansion of its CNG infrastructure. This brings the total number of operational CNG stations in the country to 2,600, supporting approximately 4.4 million natural gas vehicles. The move is part of a broader strategy to diversify Iran’s fuel portfolio and reduce gasoline consumption, with more than $3 billion invested in CNG station construction and vehicle conversion projects to date.
- In February 2025, Noida International Airport partnered with Indraprastha Gas Limited to develop CNG infrastructure at the airport. IGL will establish two CNG stations-one in the west precinct and another in the airside area-serving travelers, airport staff, and partners. The collaboration also includes developing a city gas distribution network and supplying piped natural gas to airport facilities, aligning with the airport’s sustainability goals.
- On February 12, 2025, TotalEnergies signed a 10-year agreement with Gujarat State Petroleum Corporation (GSPC) to supply LNG from its global portfolio, starting in 2026. The LNG will serve industrial customers and be used for vehicles running on CNG in India, strengthening TotalEnergies’ commitment to supporting India’s energy transition and expanding CNG use.
Market Concentration & Characteristics:
The Compressed Natural Gas (CNG) Market exhibits a moderately concentrated structure with several key players holding significant shares while numerous smaller companies operate regionally. It balances innovation-driven competition with collaboration to expand infrastructure and technology. Leading firms focus on advanced engine designs, safety improvements, and expanding refueling networks, fostering steady market development. The market’s characteristics include a growing emphasis on sustainability, cost efficiency, and regulatory compliance, which influence product offerings and strategic priorities. Regional variations in infrastructure availability and government policies create diverse competitive dynamics. Emerging markets provide opportunities for new entrants, intensifying competition while established companies leverage scale and expertise to maintain leadership. This blend of competitive intensity and cooperative initiatives shapes the market’s evolution and supports long-term growth prospects.
Report Coverage:
The research report offers an in-depth analysis based on Vehicle Type, Cylinder Type, Source and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Compressed Natural Gas (CNG) Market will experience steady growth driven by increasing environmental regulations worldwide.
- Expansion of refueling infrastructure in emerging economies will enhance market accessibility and adoption.
- Technological advancements in storage and engine efficiency will improve vehicle performance and appeal.
- Integration of renewable natural gas (RNG) will support sustainability goals and diversify fuel sources.
- Government incentives and subsidies will continue to encourage fleet transitions to CNG-powered vehicles.
- Urbanization and rising demand for public transportation will boost commercial CNG vehicle deployment.
- Cost reductions in CNG vehicle manufacturing will increase affordability for private consumers.
- Strategic partnerships between manufacturers, fuel suppliers, and governments will accelerate market penetration.
- Development of digital monitoring and safety systems will enhance refueling station reliability and user confidence.
- Growing consumer awareness about clean fuels will drive broader acceptance and long-term market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Emission Regulations and Environmental Concerns
Governments worldwide are enforcing stricter emission standards to combat air pollution and climate change, making CNG an attractive alternative due to its lower emissions of nitrogen oxides, particulate matter, and carbon dioxide compared to gasoline and diesel.
Economic Benefits and Cost-Effectiveness
CNG offers lower fuel costs and greater price stability than conventional fuels, providing significant savings for fleet operators and consumers. Government incentives such as subsidies and tax rebates further reduce the total cost of ownership, accelerating adoption.
Technological Advancements in Vehicles and Infrastructure
Continuous improvements in CNG engine technology, storage tanks, and refueling infrastructure have enhanced vehicle performance, safety, and convenience, making CNG vehicles more appealing and practical for a wider range of users.
Expansion of Refueling Infrastructure
Investments by governments and private companies in building new CNG stations, especially in emerging economies, are reducing range anxiety and improving accessibility, which is critical for broader market penetration.
Integration of Renewable Natural Gas (RNG)
The growing use of RNG derived from organic waste and biogas sources is further reducing the carbon footprint of CNG, aligning with global sustainability goals and increasing the market’s appeal to environmentally conscious consumers and regulators.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Compressed Natural Gas (CNG) Market?
What factors are driving the growth of the Compressed Natural Gas (CNG) Market?
Which application is anticipated to grow at the fastest rate throughout the projected period?
Who are the main players in the global compressed natural gas (CNG) industry?
Which market factors are the primary drivers of the compressed natural gas (CNG) industry?
What main market challenges prevent the growth of the compressed natural gas (CNG) sector?
What are the main market opportunities for the compressed natural gas (CNG) sector?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Refinery
- 1.2.2 Associated Gas
- 1.2.3 Non-Associated Gas
- 1.3 By Application
- 1.3.1 Transportation
- 1.3.2 Industrial Use
- 1.3.3 Residential Use
- 1.3.4 Power Generation
- 1.4 By Vehicle Type
- 1.4.1 Passenger Cars
- 1.4.2 Commercial Vehicles
- 1.4.3 Two-Wheelers
- 1.4.4 Three-Wheelers
- 1.4.5 Buses
- 1.5 By Cylinder Type
- 1.5.1 Single Cylinder
- 1.5.2 Twin Cylinder
- 1.5.3 Multi Cylinder
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 89,113 million → 2032: USD 121,451.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Compressed Natural Gas (CNG) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Compressed Natural Gas (CNG) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Compressed Natural Gas (CNG) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Compressed Natural Gas (CNG) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Compressed Natural Gas (CNG) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Compressed Natural Gas (CNG) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Compressed Natural Gas (CNG) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Compressed Natural Gas (CNG) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 89,113 million → 2032: USD 121,451.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Compressed Natural Gas (CNG) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Refinery
- 12.3.7.2 Associated Gas
- 12.3.7.3 Non-Associated Gas
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transportation
- 12.4.7.2 Industrial Use
- 12.4.7.3 Residential Use
- 12.4.7.4 Power Generation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Cars
- 12.5.7.2 Commercial Vehicles
- 12.5.7.3 Two-Wheelers
- 12.5.7.4 Three-Wheelers
- 12.5.7.5 Buses
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Cylinder Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Single Cylinder
- 12.6.7.2 Twin Cylinder
- 12.6.7.3 Multi Cylinder
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Compressed Natural Gas (CNG) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Compressed Natural Gas (CNG) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Compressed Natural Gas (CNG) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Compressed Natural Gas (CNG) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Clean Energy Fuels Corp.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Indraprastha Gas Limited
- 18.4 Gazprom
- 18.5 TotalEnergies
- 18.6 Chevron Corporation
- 18.7 ExxonMobil Corporation
- 18.8 Royal Dutch Shell Plc
- 18.9 Centrica
- 18.10 ConocoPhillips
- 18.11 Sempra Energy
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

