
Market Overview
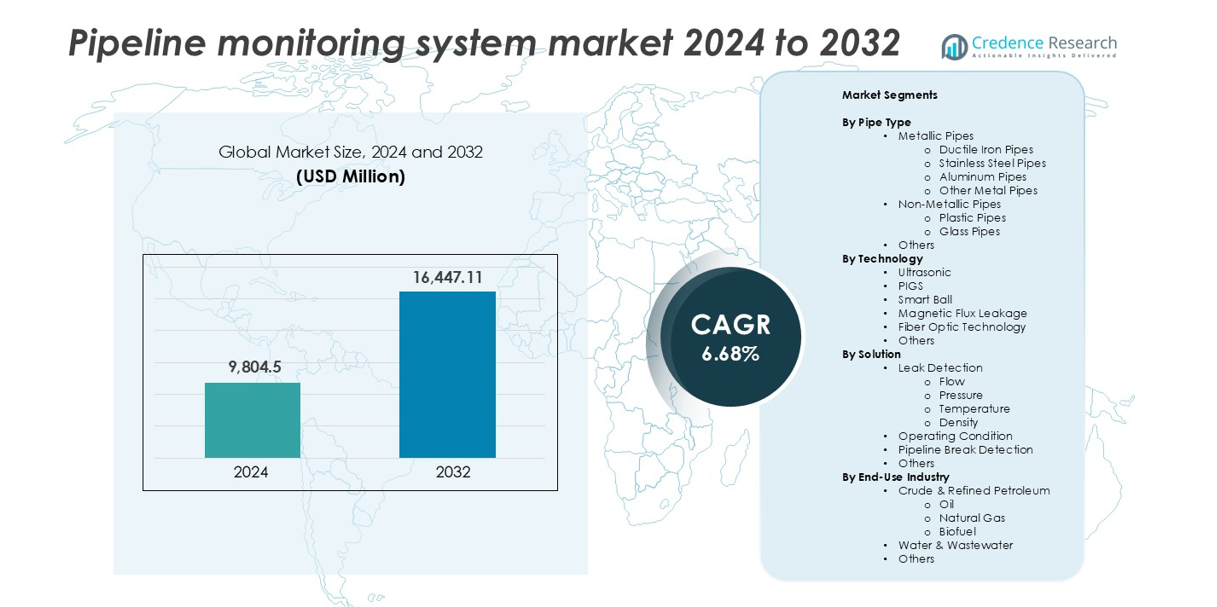
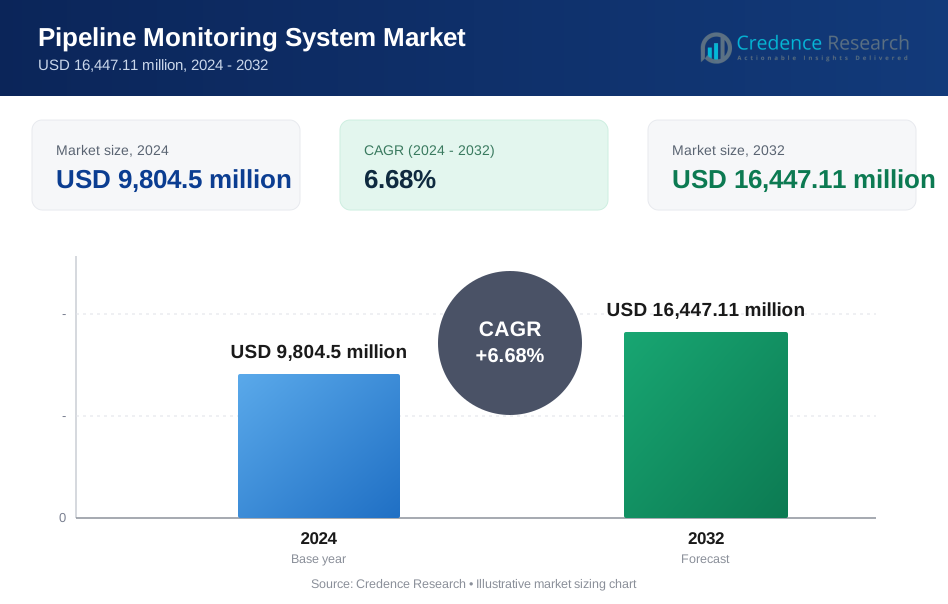
The Pipeline Monitoring System Market size was valued at USD 9,804.5 million in 2024 and is anticipated to reach USD 16,447.11 million by 2032, at a CAGR of 6.68% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pipeline Monitoring System Market Size 2024 | USD 9,804.5 million |
| Pipeline Monitoring System Market, CAGR | 6.68% |
| Pipeline Monitoring System Market Size 2032 | USD 16,447.11 million |
The pipeline monitoring system market is led by top players including Siemens AG, Honeywell International Inc., Schneider Electric SE, Emerson Electric Co., ABB Ltd., and General Electric Company. These companies dominate through advanced sensing technologies, integration with automation platforms, and strong global service networks. North America holds the largest regional share at 34%, driven by extensive oil and gas infrastructure, strict regulatory enforcement, and early technology adoption across the U.S. and Canada. Europe follows with a 26% share, supported by robust environmental policies and modern pipeline systems. Asia Pacific is the fastest-growing region, capturing 21% of the market, with rising demand from infrastructure expansion in China, India, and Southeast Asia. Companies such as TC Energy, Enbridge Inc., and Baker Hughes further strengthen North American presence, while firms like PSI AG, Yokogawa Electric Corporation, and ClampOn AS drive innovation in Europe and Asia, supporting regional growth through specialized monitoring and control solutions.
Market Insights
- The Pipeline Monitoring System Market was valued at USD 9,804.5 million in 2024 and is projected to reach USD 16,447.11 million by 2032, growing at a CAGR of 6.68%.
- Rising incidents of pipeline leaks and strict environmental regulations are driving the demand for real-time monitoring and early fault detection technologies.
- Ultrasonic and fiber optic technologies are emerging as preferred choices, with increased adoption of predictive maintenance and AI-based monitoring solutions across oil, gas, and water infrastructure.
- North America leads the market with a 34% share, followed by Europe at 26% and Asia Pacific at 21%, while metallic pipes and leak detection systems hold the largest segment shares due to their widespread application and operational reliability.
- High installation costs, integration complexity, and data management challenges remain key restraints, especially for operators managing legacy infrastructure or operating in cost-sensitive regions.
Market Segmentation Analysis:
By Pipe Type
Metallic pipes hold the largest share of the pipeline monitoring system market, driven by their widespread use in oil, gas, and water transmission. Among metallic types, ductile iron pipes dominate due to their durability, corrosion resistance, and suitability for high-pressure conditions. These pipes are favored in long-distance water and wastewater systems. Stainless steel pipes follow, with strong demand in chemically aggressive environments. Aluminum and other metals find niche use in low-weight or specialty applications. Non-metallic pipes, including plastic and glass, are gaining traction in corrosive or low-pressure settings, but account for a smaller market share.
- For instance, Saint-Gobain PAM supplies ductile iron pipelines used in over 100,000 kilometers of water infrastructure globally, including major municipal networks in Europe and Asia.
By Technology
Ultrasonic technology leads the market owing to its accuracy in detecting wall thinning, leaks, and flow irregularities. It is widely deployed across petroleum and water pipelines for internal inspections. Magnetic flux leakage follows, favored for detecting corrosion and pitting in ferrous pipelines. Smart ball systems are growing in use due to their ability to travel inside pipelines and detect small leaks. PIGS (Pipeline Inspection Gauges) remain standard in oil and gas sectors for cleaning and basic inspection. Fiber optic monitoring, while still emerging, offers real-time alerts over long distances and is gaining adoption in high-risk infrastructure.
- For example, ROSEN Group’s MFL tools are deployed in more than 120 countries and inspect over 20,000 km of oil and gas pipelines each year.
By Solution
Leak detection solutions dominate the market, especially those based on flow and pressure monitoring. These solutions are critical in minimizing environmental risks and avoiding costly downtime. Flow monitoring is the most deployed sub-segment, with pressure and temperature sensors closely integrated to track operating anomalies. Pipeline break detection systems are essential for high-value transmission lines in remote areas, where quick response reduces spill impact. Solutions for monitoring operating conditions support predictive maintenance strategies, helping operators prevent failures before they occur. Density-based leak detection, while niche, supports specialized applications like slurry or multiphase pipelines.
Key Growth Drivers
Rising Demand for Leak Prevention and Environmental Safety
Pipeline operators face strict safety and environmental rules worldwide. Regulators enforce rapid leak detection and response standards. Oil, gas, and water utilities invest in monitoring to avoid spills. Environmental damage leads to heavy fines and reputational loss. Pipeline monitoring systems reduce these operational risks. Real-time alerts help operators isolate faults quickly. Advanced sensors improve early leak identification accuracy. Aging pipeline networks increase failure probability. Operators prioritize monitoring to extend asset life. Urban expansion places pipelines near populated zones. This proximity raises public safety concerns. Monitoring systems support compliance with safety mandates. Insurance providers also demand risk mitigation tools. These factors strongly drive adoption across industries. The Pipeline monitoring system market benefits from this growing safety focus.
- For instance, TC Energy has integrated advanced real-time fiber optic monitoring technology along segments of its pipeline network in Canada and the U.S. As part of its broader safety program, which saw over $1 billion in investment recently, these systems utilize Distributed Acoustic Sensing (DAS) and temperature monitoring to detect potential leaks and external threats, enabling response times within minutes and significantly reducing the risk of spill spread.
Expansion of Oil, Gas, and Water Infrastructure Networks
Global energy demand supports new pipeline construction. Emerging economies expand oil and gas transport capacity. Water and wastewater infrastructure investments continue to rise. Governments fund large-scale pipeline modernization projects. Long-distance pipelines require continuous condition monitoring. Remote routes increase inspection complexity and cost. Monitoring systems reduce manual inspection dependence. Operators gain better visibility across wide networks. Offshore pipelines further increase monitoring needs. Harsh environments limit physical access. Digital monitoring ensures operational continuity. Natural gas distribution growth adds new deployment areas. Cross-border pipelines require standardized monitoring frameworks. Infrastructure expansion directly increases system installations. This trend strongly supports market growth.
- For instance, Petrobras uses smart PIGs and ultrasonic tools across over 10,000 km of pipelines, particularly in offshore oil transport between Brazilian rigs and refineries.
Digitalization and Predictive Maintenance Adoption
Pipeline operators shift toward data-driven operations. Predictive maintenance reduces unexpected failures and downtime. Monitoring systems generate continuous operational data. Analytics tools convert data into actionable insights. Operators detect corrosion trends early. Maintenance planning becomes more efficient. Asset utilization improves across pipeline networks. Integration with SCADA systems supports centralized control. Artificial intelligence enhances fault prediction accuracy. Digital twins simulate pipeline behavior under stress. These capabilities lower lifecycle costs. Operators seek long-term operational savings. Digital adoption accelerates monitoring system upgrades. This shift acts as a key growth driver.
Key Trends & Opportunities
Integration of Fiber Optic and Smart Sensing Technologies
Fiber optic sensing gains attention for long-distance monitoring. The technology enables real-time temperature and strain detection. Operators monitor thousands of kilometers from one system. Smart sensing reduces response time to incidents. These systems support high-risk pipeline segments. Adoption increases in oil, gas, and chemical transport. Costs decline with technology maturity. Vendors offer hybrid monitoring platforms. Integration improves overall detection reliability. Utilities adopt smart sensing for critical water pipelines. This trend creates new revenue opportunities. Advanced projects favor high-value monitoring solutions.
- For instance, Enbridge uses distributed acoustic sensing (DAS) over more than 2,500 km of pipeline in North America to detect third-party interference and pressure anomalies in real time.
Growth Opportunities in Emerging Economies
Developing regions invest in pipeline infrastructure upgrades. Urbanization increases water and fuel distribution needs. Governments prioritize reducing losses and theft. Monitoring systems support operational transparency. Local regulations begin to mandate leak detection. International funding supports infrastructure resilience projects. Vendors enter partnerships with regional operators. Cost-effective monitoring solutions gain traction. Emerging markets offer long-term growth potential. This opportunity supports sustained market expansion.
Key Challenges
High Installation and Integration Costs
Pipeline monitoring systems require significant upfront investment. Hardware, sensors, and communication networks raise costs. Retrofitting older pipelines proves complex. Integration with legacy systems adds technical challenges. Smaller operators face budget constraints. Cost concerns delay adoption decisions. Remote installations increase deployment expenses. Skilled labor requirements further raise costs. Return on investment may take time. These factors limit penetration in cost-sensitive markets. Price sensitivity remains a key barrier.
Data Management and System Complexity Issues
Monitoring systems generate large data volumes. Operators require advanced analytics capabilities. Data interpretation demands skilled personnel. False alarms reduce operator confidence. System calibration requires continuous attention. Cybersecurity risks increase with digital connectivity. Integration across multiple technologies adds complexity. Operators face training and change management challenges. Inconsistent data quality affects decision-making. These issues slow full-scale adoption. Complexity remains a critical challenge for the Pipeline monitoring system market.
Regional Analysis
North America
North America holds the largest share of the pipeline monitoring system market, accounting for over 34% in 2024. The region benefits from extensive oil and gas pipeline networks, particularly across the U.S. and Canada. Regulatory enforcement by PHMSA and growing investments in digital infrastructure boost adoption. High-profile incidents in past decades have driven operators to adopt advanced leak detection and predictive monitoring solutions. The U.S. dominates regional demand, with large-scale upgrades to aging infrastructure. High R&D spending and strong presence of leading vendors also support market expansion in North America.
Europe
Europe represents approximately 26% of the global market share in 2024, driven by a focus on safety and environmental regulations. Countries like Germany, the UK, and Norway implement strict pipeline monitoring mandates. The region emphasizes early fault detection and sustainable operation, especially for gas distribution systems. Cross-border energy transmission projects and the shift to hydrogen blending drive new system deployment. Fiber optic and smart sensing technologies gain traction in Northern and Western Europe. EU-backed infrastructure resilience funding also supports modernization, further stimulating regional growth.
Asia Pacific
Asia Pacific is the fastest-growing region, capturing around 21% market share in 2024 and expanding rapidly. China, India, and Southeast Asian nations continue to invest in oil, gas, and water pipelines. Urban expansion, industrialization, and high population density heighten the need for real-time monitoring. Governments in India and China implement infrastructure digitization initiatives. Emerging economies drive strong demand for cost-effective leak detection and operating condition solutions. Rising cross-country pipeline projects in the region support sustained deployment of monitoring systems. Growing water management needs also contribute to Asia Pacific’s growth trajectory.
Latin America
Latin America accounts for close to 10% of the market share in 2024, supported by oil and gas activities in Brazil, Argentina, and Mexico. Regional governments focus on reducing pipeline theft and spill-related losses, especially in high-risk zones. Investment in automated leak detection and remote monitoring systems grows as utilities modernize legacy infrastructure. Mexico’s pipeline reforms and Brazil’s offshore expansion drive system demand. However, political and economic instability in some nations may impact long-term adoption. Regional growth remains steady with targeted modernization efforts.
Middle East & Africa (MEA)
The Middle East & Africa region holds about 9% of the global market share in 2024. The Middle East’s large oil transmission networks in Saudi Arabia, UAE, and Kuwait fuel demand for high-precision monitoring. Harsh desert environments and long pipeline routes increase reliance on digital systems. Africa’s market is smaller but growing, with investments in water infrastructure and oil transportation. Nigeria, Egypt, and South Africa adopt monitoring tools to enhance operational safety and efficiency. Challenges such as budget constraints and limited skilled workforce may slow broader adoption across developing regions.
Market Segmentations:
By Pipe Type
- Metallic Pipes
-
-
- Ductile Iron Pipes
- Stainless Steel Pipes
- Aluminum Pipes
- Other Metal Pipes
-
- Non‑Metallic Pipes
-
-
- Plastic Pipes
- Glass Pipes
-
- Others
By Technology
- Ultrasonic
- PIGS
- Smart Ball
- Magnetic Flux Leakage
- Fiber Optic Technology
- Others
By Solution
- Leak Detection
-
-
- Flow
- Pressure
- Temperature
- Density
-
- Operating Condition
- Pipeline Break Detection
- Others
By End‑Use Industry
- Crude & Refined Petroleum
-
-
- Oil
- Natural Gas
- Biofuel
-
- Water & Wastewater
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The pipeline monitoring system market is highly competitive, with key players focusing on advanced sensing technologies, digital integration, and global service capabilities. Major companies like Siemens AG, ABB Ltd., Honeywell International Inc., and Emerson Electric Co. lead through diversified portfolios and real-time monitoring solutions. U.S.-based firms such as General Electric, Baker Hughes, and Rohrback Cosasco Systems offer specialized tools for ultrasonic inspection, pressure analysis, and corrosion detection. European firms including Schneider Electric and PSI AG focus on automation and SCADA-linked platforms, while companies like ClampOn AS and Atmos International specialize in acoustic and flow monitoring. Canadian firms such as TC Energy, Enbridge, and Pure Technologies focus on infrastructure safety across vast oil and gas networks. New entrants and regional players compete by offering cost-effective leak detection and predictive maintenance systems. Partnerships, service contracts, and regulatory compliance drive competition, with innovation in fiber optic sensing and AI-powered analytics shaping future strategies in the market.
Key Player Analysis
- ABB Ltd. (Switzerland)
- Atmos International (United Kingdom)
- Baker Hughes Company (United States)
- ClampOn AS (Norway)
- Emerson Electric Co. (United States)
- Enbridge Inc. (Canada)
- General Electric Company (United States)
- Honeywell International Inc. (United States)
- Perma-Pipe International Holdings, Inc. (United States)
- PSI AG (Germany)
- Pure Technologies Ltd. (Canada)
- Rohrback Cosasco Systems (United States)
- Schneider Electric SE (France)
- Senstar Corporation (Canada)
- Siemens AG (Germany)
- TC Energy (formerly TransCanada Corporation) (Canada)
- Yokogawa Electric Corporation (Japan)
Recent Developments
- In April 2025, ABB Ltd. delivered integrated automation and digital technology for IndianOil’s large pipeline network (covering SCADA/automation, remote data acquisition, and leak-detection capabilities), highlighting ABB’s role in large-scale pipeline monitoring and control deployments.
- In December 2024, Emerson Electric Co. published/updated its PipelineManager software suite (real-time transient modeling, leak detection, and pipeline operational analytics), reaffirming Emerson’s software-centric approach to pipeline leak detection, RTTM, and mixed-product/transient monitoring
Report Coverage
The research report offers an in-depth analysis based on Pipe Type, Technology, Solution, End‑Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for real-time pipeline monitoring will continue rising due to growing environmental safety concerns.
- Adoption of fiber optic sensing technology will expand across long-distance and high-risk pipelines.
- Predictive maintenance solutions will gain popularity to reduce operational downtime and asset failure.
- Integration with AI and IoT platforms will enhance detection accuracy and remote diagnostics.
- Regulatory mandates will tighten, pushing more operators to adopt automated monitoring systems.
- Emerging economies will invest in pipeline upgrades, boosting demand for cost-effective monitoring tools.
- Leak detection technologies will dominate new deployments across oil, gas, and water networks.
- Cloud-based monitoring platforms will support centralized control and multi-site visibility.
- Partnerships between technology providers and pipeline operators will grow to deliver customized solutions.
- Monitoring systems will expand into hydrogen, biofuel, and carbon capture pipeline networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Pipeline Monitoring System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Pipeline Monitoring System Market projected to grow between 2024 and 2032?
Who are the major players in the global pipeline monitoring systems market?
What are the major market drivers of the pipeline monitoring systems industry?
What are the major market restraints of the pipeline monitoring systems industry?
What are the major market opportunities of the pipeline monitoring systems industry?
Who are the leading companies in the Pipeline Monitoring System Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pipeline Monitoring System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pipeline Monitoring System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,804.5 million → 2032: USD 16,447.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pipeline Monitoring System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pipeline Monitoring System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pipeline Monitoring System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pipeline Monitoring System Market Drivers
- 3.3 Pipeline Monitoring System Market Restraints & Challenges
- 3.4 Pipeline Monitoring System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pipeline Monitoring System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pipeline Monitoring System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pipeline Monitoring System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pipeline Monitoring System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pipeline Monitoring System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pipeline Monitoring System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pipeline Monitoring System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pipeline Monitoring System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pipeline Monitoring System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pipeline Monitoring System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pipeline Monitoring System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pipeline Monitoring System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pipeline Monitoring System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pipeline Monitoring System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pipeline Monitoring System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pipeline Monitoring System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pipeline Monitoring System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pipeline Monitoring System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pipeline Monitoring System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
