
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Superabsorbent Polymers (SAP) Market Size 2024 | USD 11,550 million |
| Superabsorbent Polymers (SAP) Market, CAGR | 9.23% |
| Superabsorbent Polymers (SAP) Market Size 2032 | USD 23,405 million |
Market Overview:
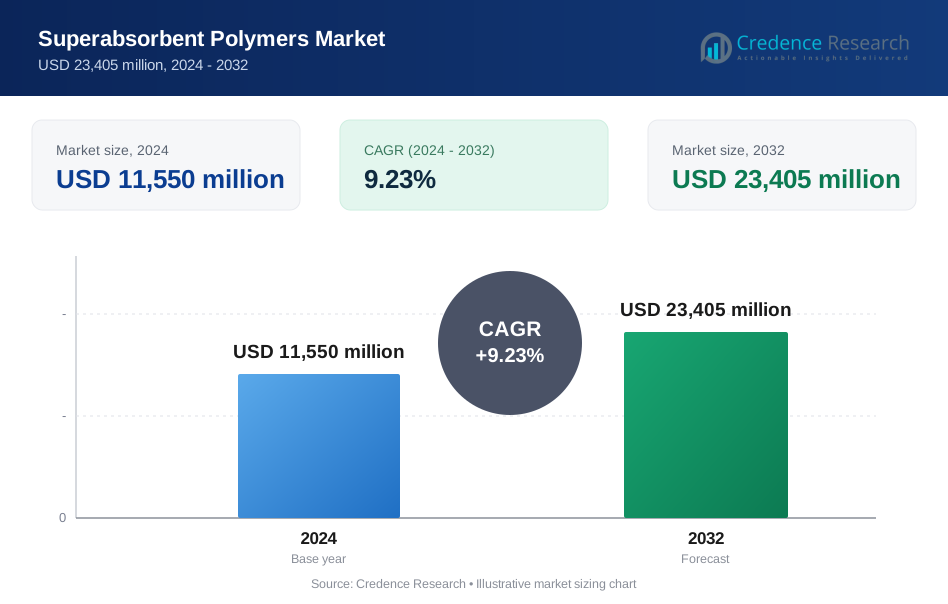
Superabsorbent Polymers (SAP) Market size was valued at USD 11,550 million in 2024 and is anticipated to reach USD 23,405 million by 2032, at a CAGR of 9.23% during the forecast period (2024-2032).
The market is driven by increasing global awareness of personal hygiene, particularly in developing economies where hygiene product penetration is rising. Aging populations in North America, Europe, and parts of Asia are contributing to increased demand for adult incontinence products. Rising birth rates and improving living standards in Asia-Pacific and Africa are supporting growth in the baby diaper segment. In agriculture, SAPs are gaining attention for their role in water conservation and improved crop yields in arid regions. The growing focus on sustainability and water management is prompting R&D investments in eco-friendly SAP solutions, further enhancing their market potential. Moreover, the healthcare sector’s rising demand for advanced wound care solutions is driving product innovation. Manufacturers are also exploring bio-based raw materials to align with global environmental goals. Increasing government initiatives promoting hygiene awareness and water efficiency are reinforcing market expansion.
Regionally, Asia-Pacific dominates the Superabsorbent Polymers Market, accounting for the highest revenue share due to strong manufacturing bases in China, India, and Japan and the large population base supporting demand for hygiene products. North America holds the second-largest market share, supported by high per capita consumption of personal care items and a mature healthcare system. Europe follows closely, with increasing demand for biodegradable SAPs and regulatory support for sustainable hygiene solutions. Latin America and the Middle East & Africa markets are emerging, driven by improving healthcare infrastructure and rising consumer awareness. Rising investments from multinational companies in regional production facilities are improving supply chain efficiency. Strategic collaborations between regional manufacturers and raw material suppliers are enabling cost-effective product development.
Market Insights:
- The Superabsorbent Polymers (SAP) Market was valued at USD 11,550 million in 2024 and is projected to reach USD 23,405 million by 2032, growing at a CAGR of 9.23% during the forecast period.
- Increasing demand for baby diapers, adult incontinence products, and feminine hygiene items is driving global SAP consumption.
- Aging populations in North America, Europe, and East Asia are significantly boosting the use of SAP-based adult care products.
- Adoption of SAPs in agriculture is rising, especially in arid regions, due to their water-retention properties and support for crop yield improvement.
- Manufacturers are focusing on biodegradable and bio-based SAPs to meet sustainability targets and comply with tightening regulations.
- Asia-Pacific leads the market with 42% share in 2024, driven by high population, rising hygiene awareness, and large-scale manufacturing.
- Volatile raw material costs and environmental regulations are pressuring traditional SAP producers to innovate and enhance supply chain resilience.
Market Drivers:
Rising Demand for Hygiene Products across Demographics
The Superabsorbent Polymers (SAP) Market is witnessing steady growth due to increased consumption of hygiene products across age groups. Baby diapers, adult incontinence products, and feminine hygiene items continue to account for the majority of global SAP usage. Rapid urbanization and rising awareness of hygiene in developing countries are contributing to higher product adoption. Governments and NGOs are launching awareness campaigns that promote better sanitation practices, creating further demand. Higher disposable income levels in emerging economies are enabling consumers to opt for superior hygiene solutions. This demand directly supports volume growth in the SAP supply chain.
Growing Geriatric Population in Developed Regions
North America, Europe, and parts of East Asia are facing demographic shifts due to aging populations. This shift is driving increased consumption of adult incontinence products, which rely heavily on SAP technology. Manufacturers are developing advanced polymer formulations to meet comfort and performance expectations for elderly consumers. Product innovations are focusing on better fluid retention and reduced skin irritation. The healthcare sector in these regions is integrating SAPs in hospital-grade hygiene products and care facilities. It is helping to stabilize long-term demand for SAP-based materials.
- For instance, Advanced Absorbent Technologies’ Alyne absorbent underwear uses multiple layers of different SAPs to provide superior fluid absorption and comfort for elderly users in North America, and was a finalist for INDA’s Hygienix Innovation Award.
Expansion of Agricultural Applications in Water-Scarce Regions
SAPs are gaining traction in agriculture due to their water-retention properties. Farmers in arid and drought-prone areas are adopting SAPs to improve soil moisture levels and crop productivity. Governments in regions such as the Middle East and Africa are supporting initiatives that promote efficient irrigation practices. The shift toward climate-resilient agriculture is encouraging research and development in polymer-based soil conditioners. It is fostering new use cases beyond conventional hygiene products. This trend is unlocking growth in non-traditional sectors for SAP producers.
Innovation in Sustainable and Biodegradable SAPs
Environmental concerns are pushing manufacturers to create eco-friendly SAP variants. Biodegradable polymers are becoming a focus area due to stricter regulations on plastic content in disposable hygiene items. Companies are investing in bio-based raw materials and green chemistry to meet market expectations. This is influencing procurement strategies and product development across the supply chain. It also aligns with corporate sustainability goals and consumer preferences. The shift is creating a competitive edge for companies investing early in sustainable SAP innovation.
- For instance, Kenya’s National Drought Management Authority subsidizes SAPs for smallholder farmers in arid counties to stabilize maize production, and in India, agritech startup EF Polymer’s “Fasal Amrit” (made from fruit peels) is helping farmers in Rajasthan conserve water and reduce irrigation frequency.
Market Trends:
Rising Focus on Sustainable and Biodegradable Alternatives
The Superabsorbent Polymers (SAP) Market is undergoing a transformation driven by growing demand for sustainable materials. Manufacturers are investing in the development of bio-based and biodegradable SAPs to address regulatory pressures and environmental concerns. Consumers are increasingly favoring products with lower environmental impact, prompting innovation across hygiene and agricultural applications. Companies are exploring starch-based and cellulose-derived SAPs that offer comparable absorbency with improved biodegradability. Governments are enforcing stricter policies on single-use plastics, creating incentives for green alternatives. It is encouraging a shift in production processes, material sourcing, and product design throughout the industry.
- For instance, NAGASE & CO., LTD., in collaboration with Nagase ChemteX Corporation and Hayashibara Co., Ltd., has successfully developed a superabsorbent polymer with high biomass content, using starch as the primary material, which matches or exceeds the absorbency of conventional products while being bio-based and biodegradable.
Adoption of SAPs in Non-Traditional Sectors
SAPs are expanding into industries beyond hygiene, including agriculture, construction, and packaging. In agriculture, SAPs improve water efficiency and soil health, supporting sustainable farming in water-stressed regions. Construction applications are emerging, where SAPs help manage moisture in concrete curing and reduce cracking. The packaging sector is utilizing SAPs for spill control and moisture regulation in transport-sensitive goods. These diversified applications are helping reduce dependency on the hygiene segment while unlocking new revenue streams. It is broadening the competitive landscape and attracting new entrants into the SAP value chain.
- For instance, scientists from China Agricultural University demonstrated that combining polyacrylamide SAPs with biofertilizers significantly improved seed germination rates and growth parameters in wheat and cucumber, highlighting SAPs’ positive impact in sustainable agriculture.
Market Challenges Analysis:
Fluctuating Raw Material Costs and Supply Chain Volatility
The Superabsorbent Polymers (SAP) Market faces significant pressure from raw material price volatility. Acrylate-based materials, which form the core of most SAPs, depend heavily on crude oil derivatives. Any disruption in oil supply or geopolitical tensions can impact cost structures across the supply chain. Manufacturers are often forced to absorb rising input costs or pass them on to consumers, affecting profitability and market competitiveness. Supply chain constraints, including shipping delays and limited availability of specialty chemicals, further compound the challenge. It restricts production flexibility and increases lead times for end-use industries.
- For instance, Blue Diamond Growers implemented SAP S/4HANA and SAP Integrated Business Planning to gain real-time insights into how fluctuations in supply volumes and costs impact financial performance, enabling the co-op to optimize planning and mitigate supply chain risks through data-driven decision-making.
Environmental Impact and Regulatory Pressures
Concerns over environmental sustainability are creating challenges for traditional SAPs, which are typically non-biodegradable. Regulatory bodies in North America, Europe, and Asia are tightening rules on the use of plastics in disposable hygiene products. This creates compliance risks for producers that rely on petroleum-based polymers. The cost of transitioning to biodegradable alternatives remains high, especially for small and mid-sized manufacturers. Public scrutiny and environmental activism are prompting companies to accelerate innovation while managing operational risks. It requires substantial investment in research, testing, and certification to meet evolving regulatory demands.
Market Opportunities:
Expansion into Water Management and Agricultural Solutions
The Superabsorbent Polymers (SAP) Market holds strong potential in addressing water scarcity through advanced agricultural applications. SAPs enhance soil water retention, reduce irrigation frequency, and improve crop resilience in arid regions. Governments are promoting efficient water use in farming, creating opportunities for SAP deployment in large-scale agricultural projects. Demand is rising in regions such as the Middle East, Africa, and parts of Asia where water stress impacts food production. It creates a platform for collaboration between SAP manufacturers and agri-tech companies to develop tailored soil conditioning solutions. Public-private partnerships in sustainable agriculture could accelerate adoption and market growth.
Development of Eco-Friendly and High-Performance SAPs
Innovation in sustainable SAPs presents a strategic opportunity to meet shifting consumer preferences and regulatory standards. Bio-based polymers derived from renewable feedstocks are gaining traction in personal care and hygiene products. Companies that invest in biodegradable alternatives can differentiate themselves in a competitive market. It opens access to premium product segments and environmentally conscious consumers. High-performance SAPs with enhanced absorption, durability, and skin compatibility are also finding applications in medical and industrial fields. These advancements support long-term market diversification and strengthen global brand positioning.
Market Segmentation Analysis:
By Product Type
The Superabsorbent Polymers (SAP) Market includes sodium polyacrylate, polyacrylamide copolymers, and other variants under this segment. Sodium polyacrylate dominates due to its superior liquid absorption properties and cost-effectiveness in hygiene products. Polyacrylamide copolymers are gaining market share in agriculture and industrial applications, where moisture retention and chemical resistance are critical. Other polymer types are being explored for specialty uses, particularly in eco-friendly and biodegradable formulations.
By Application
The market covers personal hygiene, agriculture, medical, and industrial applications. Personal hygiene remains the leading application segment, supported by growing global demand for baby diapers, feminine hygiene, and adult incontinence products. Agricultural applications are rising steadily with increasing focus on water conservation and sustainable farming practices. Medical uses include wound care, surgical pads, and drug delivery systems. Industrial applications such as cable insulation and spill control are also emerging, broadening the market's functional reach.
By Form
Granular, powder, and liquid forms define this segment. Granular SAPs hold the largest share due to their widespread use in disposable hygiene products. Powdered SAPs are preferred in agriculture and construction for their versatility and ease of blending. Liquid SAPs, while limited in volume, are gaining attention in medical and cosmetic applications requiring specialized performance. The Superabsorbent Polymers (SAP) Market continues to evolve with innovation in form factors that match application-specific needs.
Segmentations:
By Product Type
- Sodium Polyacrylate
- Polyacrylamide Copolymers
- Others
By Application
- Personal Hygiene
- Agriculture
- Medical
- Industrial
By Form
- Granular
- Powder
- Liquid
By End-User Industry
- Healthcare
- Agriculture
- Personal Care
- Packaging
- Construction
By Distribution Channel
- Direct Sales
- Distributors/Wholesalers
- Online Retail
- Specialty Stores
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific Leads with Expanding Hygiene and Agricultural Demand
Asia-Pacific held 42% of the global Superabsorbent Polymers (SAP) Market in 2024, making it the largest regional segment. China and India played a major role due to strong demand in hygiene and agriculture sectors. Countries like Japan also contribute through advanced manufacturing and steady domestic consumption. Increasing birth rates, rising hygiene awareness, and rapid urbanization continue to drive growth in baby diapers and feminine care products. Governments across the region are promoting water-saving agricultural practices, encouraging SAP adoption among farmers. It benefits from cost-effective production and a robust local supply chain catering to both domestic and export markets. Investments in biodegradable SAPs are also gaining momentum in the region.
North America Sustains Growth through Innovation and High Per Capita Consumption
North America accounted for 25% of the global Superabsorbent Polymers (SAP) Market in 2024, ranking as the second-largest regional market. The United States drives demand due to widespread use of hygiene and medical products and a well-developed healthcare system. Consumers demand high-performance and skin-friendly solutions, pushing innovation in SAP technology. Companies are focusing on sustainable product lines to align with tightening environmental regulations. It benefits from a stable retail infrastructure and strong distribution networks that ensure consistent product availability. Expanding use of SAPs in agriculture and industrial sectors is also contributing to steady market growth.
Europe Focuses on Sustainable Solutions and Regulatory Compliance
Europe captured 20% of the global Superabsorbent Polymers (SAP) Market in 2024, reflecting its emphasis on sustainability and strict environmental policies. EU regulations are encouraging the shift toward bio-based and biodegradable SAP materials. Germany, France, and the UK remain key countries driving demand through their advanced hygiene sectors and environmentally conscious consumers. It supports innovation through partnerships between manufacturers and research institutes focused on reducing environmental impact. Strong demand for eco-friendly hygiene products and medical-grade SAPs is shaping regional growth. The region's policy-driven market environment continues to support long-term adoption of sustainable SAP technologies.
Key Player Analysis:
- BASF
- Kao
- Nippon Shokubai
- Yixing Danson
- Nuoer
- Sumitomo Seika Chemicals
- Zhejiang Satellite Petrochemical
- Evonik Industries
- LG Chem
- Shanghai Huayi Acrylic Acid
- Archer Daniels Midland
- Acuro Organics
- Sanyo Chemical
- Formosa Plastics
- Songwon
Competitive Analysis:
The Superabsorbent Polymers (SAP) Market features a competitive landscape shaped by innovation, capacity expansion, and strategic partnerships. Leading players such as BASF, Nippon Shokubai, and Evonik Industries maintain dominance through robust R&D and diversified product portfolios. Companies focus on sustainable and bio-based SAPs to align with environmental regulations and shifting consumer preferences. It continues to witness high competition from regional manufacturers in Asia-Pacific, particularly China, which offers low-cost alternatives. Strategic mergers and joint ventures help global players enhance market reach and technological capabilities. Firms invest in advanced production techniques to reduce energy use and improve polymer performance. The market's competitiveness intensifies with rising demand from personal care, agriculture, and medical applications. Companies strengthen supply chain networks and customer relationships to retain market share in a price-sensitive environment. The Superabsorbent Polymers (SAP) Market evolves through continuous innovation, regulatory compliance, and efforts to meet customized application needs across multiple sectors.
Recent Developments:
- In April, 2025, BASF launched L-Menthol FCC rPCF, its first aroma ingredient with a reduced Product Carbon Footprint (rPCF), and announced further rPCF product launches planned for 2025.
- In September 2024, Nippon Shokubai Indonesia announced a fourth expansion phase in Cilegon, Banten, to begin in 2025, focusing on superabsorbent polymer (SAP) production.
- In February2025, LG Chem announced the launch of prototype production of 100% bio-acrylic acid, certified as a USDA Biobased Product, with plans to scale up production based on demand.
Market Concentration & Characteristics:
The Superabsorbent Polymers (SAP) Market displays moderate to high concentration, with a few global players controlling a significant share. It is characterized by high entry barriers due to capital-intensive manufacturing, stringent regulatory standards, and the need for advanced technology. Major companies such as BASF, Nippon Shokubai, and Evonik Industries dominate through vertical integration, broad distribution networks, and continuous product innovation. The market prioritizes performance attributes such as absorption capacity, retention, and biodegradability, particularly in hygiene and medical applications. It shows strong alignment with environmental regulations, pushing manufacturers to develop sustainable alternatives. Price competitiveness, supply chain efficiency, and long-term contracts with end-users play critical roles in shaping market dynamics. The Superabsorbent Polymers (SAP) Market reflects stable demand growth supported by its essential role in baby diapers, adult incontinence products, and agricultural water retention solutions.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, Form, End-User Industry, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The personal hygiene sector will continue to lead SAP consumption, driven by rising demand for baby diapers and adult incontinence products.
- Agricultural applications will expand as SAPs improve water retention and reduce irrigation frequency in drought-prone regions.
- Medical usage will increase, especially in wound care and surgical products that require high absorbency and fluid retention.
- Development of bio-based and biodegradable SAPs will intensify, supporting environmental sustainability and regulatory compliance.
- Asia-Pacific will retain market dominance due to growing urban populations, improved healthcare access, and rising hygiene awareness.
- Innovations in SAP chemistry will deliver faster absorption rates and improved gel strength for specialized industrial uses.
- Construction industries will explore SAP integration into self-healing concrete and water control systems.
- Strategic alliances among major players will focus on expanding production capacity and advancing product innovation.
- Regulatory bodies will enforce stricter controls on product composition, pushing manufacturers to invest in safer alternatives.
- The industry will adopt automation and digital manufacturing tools to optimize production efficiency and reduce operational costs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Hygiene Product Penetration in Emerging Markets
Rapid urbanization and rising awareness of personal hygiene in developing economies are increasing the adoption of baby diapers, feminine hygiene, and adult incontinence products, directly boosting SAP demand.
Aging Population in Developed Regions
Demographic shifts in North America, Europe, and East Asia are driving higher consumption of adult incontinence products, which rely heavily on SAPs for superior fluid absorption and comfort.
Agricultural Water Conservation Initiatives
SAPs are increasingly used in agriculture for their water-retention properties, especially in arid and drought-prone regions, supporting crop yields and aligning with government-backed water management programs.
Innovation in Sustainable and Biodegradable SAPs
Stricter environmental regulations and consumer demand for eco-friendly products are prompting manufacturers to invest in bio-based and biodegradable SAPs, opening new market opportunities and ensuring regulatory compliance.
Product Diversification into Non-Traditional Sectors
The adoption of SAPs in construction, packaging, and medical applications is broadening the market's scope, reducing dependency on hygiene products and unlocking new revenue streams.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected size of the Superabsorbent Polymers (SAP) Market?
Which region leads the SAP market and why?
How is the SAP market adapting to sustainability trends?
What challenges does the Super Absorbent Polymer market face?
What role does agriculture play in the SAP market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Granular
- 1.2.2 Powder
- 1.2.3 Liquid
- 1.3 By Application
- 1.3.1 Personal Hygiene
- 1.3.2 Agriculture
- 1.3.3 Medical
- 1.3.4 Industrial
- 1.4 By Product Type
- 1.4.1 Sodium Polyacrylate
- 1.4.2 Polyacrylamide Copolymers
- 1.4.3 Others
- 1.5 By End-User Industry
- 1.5.1 Healthcare
- 1.5.2 Agriculture
- 1.5.3 Personal Care
- 1.5.4 Packaging
- 1.5.5 Construction
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,550 million → 2032: USD 23,405 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Superabsorbent Polymers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Superabsorbent Polymers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Superabsorbent Polymers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Superabsorbent Polymers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Superabsorbent Polymers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Superabsorbent Polymers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Superabsorbent Polymers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Superabsorbent Polymers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,550 million → 2032: USD 23,405 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Superabsorbent Polymers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Granular
- 12.3.7.2 Powder
- 12.3.7.3 Liquid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Personal Hygiene
- 12.4.7.2 Agriculture
- 12.4.7.3 Medical
- 12.4.7.4 Industrial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sodium Polyacrylate
- 12.5.7.2 Polyacrylamide Copolymers
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Healthcare
- 12.6.7.2 Agriculture
- 12.6.7.3 Personal Care
- 12.6.7.4 Packaging
- 12.6.7.5 Construction
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Superabsorbent Polymers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Superabsorbent Polymers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Superabsorbent Polymers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Superabsorbent Polymers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nippon Shokubai
- 18.4 Evonik Industries
- 18.5 Kao Corporation
- 18.6 LG Chem
- 18.7 Sumitomo Seika Chemicals
- 18.8 Yixing Danson
- 18.9 Nuoer
- 18.10 Sanyo Chemical
- 18.11 Zhejiang Satellite Petrochemical
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

