
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| 3D Food Printing Market Size 2024 | USD 395 million |
| 3D Food Printing Market, CAGR | 19.8% |
| 3D Food Printing Market Size 2032 | USD 1,675.913 million |
Market Overview
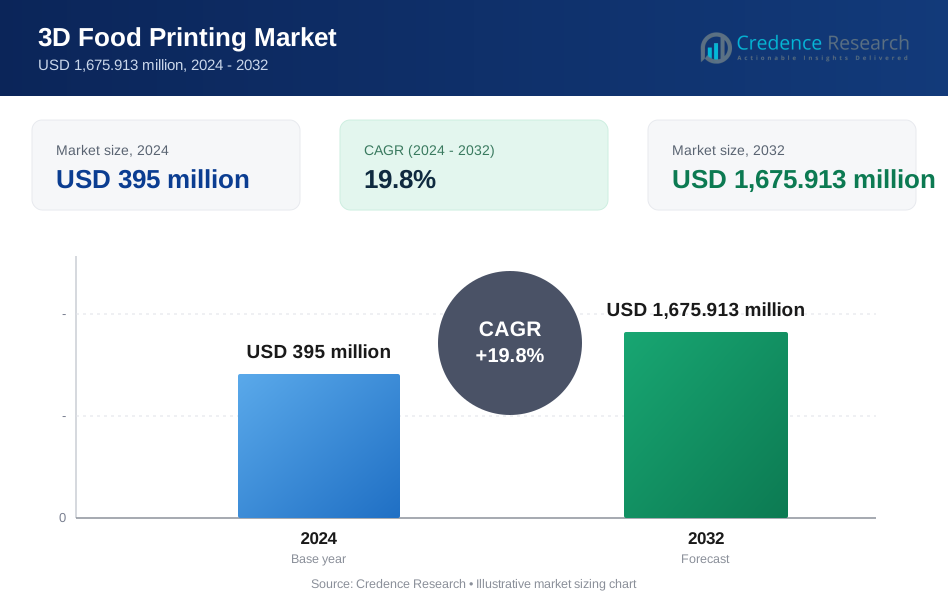
The global 3D food printing market is projected to grow from USD 395 million in 2024 to USD 1,675.913 million by 2032, at a compound annual growth rate (CAGR) of 19.8%.
The 3D food printing market is driven by increasing demand for personalized nutrition, innovative food design, and sustainable food production methods. The technology enables customization of food textures and nutrient profiles, appealing to the growing health-conscious consumer base. Additionally, advancements in printing materials, such as plant-based and alternative proteins, align with sustainability trends. The rising interest from sectors like hospitality, healthcare, and aerospace for efficient food production solutions also propels market growth. Furthermore, 3D food printing supports reduced food waste, enhancing its appeal in an era focused on environmental responsibility and resource optimization.
The geographical landscape of the 3D food printing market is diverse, with significant growth in regions such as North America and Europe, driven by technological advancements and consumer interest in innovative culinary experiences. North America holds a prominent market share, fueled by key players like 3D Systems, NATURAL MACHINES, and beehex, who are leading in research and development. Europe is witnessing rapid expansion, supported by companies such as byFlow B.V. and Choc Edge, which are pioneering unique food printing solutions. This dynamic environment fosters collaboration and innovation, enhancing the overall market potential for 3D food printing technologies.
Market Drivers
Customization and Personalization
3D food printing is revolutionizing the way dietary needs are addressed by offering precise control over ingredients. This technology is especially beneficial for individuals with allergies, intolerances, or those following vegan or vegetarian diets, as it allows for the creation of meals tailored to specific requirements. For instance, a study by the National Institute of Food Technology Entrepreneurship and Management (NIFTEM) highlighted that 3D food printing can significantly enhance dietary customization for health-sensitive consumers. In addition to addressing dietary restrictions, 3D food printing also supports personalized nutrition plans, where meals can be designed to meet individual nutritional goals and preferences. As consumers increasingly seek tailored diets for better health and wellness, the customization potential of 3D printing becomes a key driver in the food industry.
Reduced Food Waste
One of the most significant advantages of 3D food printing is its ability to reduce food waste through precise portioning and on-demand production. By producing meals with exact quantities of ingredients, this technology eliminates the need for excess food preparation, reducing the likelihood of leftover waste. For instance, research from the University of Queensland demonstrated that 3D food printing could repurpose nearly expiring food into more appealing products, thereby reducing waste. Additionally, food can be printed as needed, minimizing the risk of spoilage and waste associated with overproduction. These efficiencies not only help address global food waste issues but also contribute to cost savings for businesses, making it a highly attractive solution for both consumers and the food service industry.
Innovative Food Design
3D food printing opens up new possibilities for food design, enabling the creation of intricate shapes and textures that are difficult or impossible to achieve with traditional methods. This capability allows chefs and food manufacturers to experiment with novel forms, enhancing the visual appeal of dishes. The aesthetic possibilities of 3D printing make it an ideal tool for elevating the dining experience, particularly in high-end restaurants and event catering. As consumers increasingly value the presentation of food, 3D printing offers a creative advantage, appealing to those seeking unique and visually engaging culinary experiences.
Efficiency, Productivity, and Technological Advancements
The efficiency and productivity benefits of 3D food printing are driving its adoption in restaurants and food manufacturing. Automation of certain tasks not only speeds up food preparation but also reduces labor costs, making operations more cost-effective. Ongoing advancements in material development and software improvements further enhance the technology, making it more accessible and user-friendly for a wider range of applications. As these technological developments continue, 3D food printing is becoming a more practical and appealing option for businesses looking to innovate and improve operational efficiency in the food industry.
Market Trends
Diversification of Food Materials and Sustainability Focus
The 3D food printing industry is rapidly diversifying its use of food materials, moving beyond traditional ingredients like chocolate and sugar to incorporate plant-based proteins, fruits, vegetables, and even cell-cultured meat. This expansion opens up new opportunities for creating customized nutrition products, tailored to meet specific dietary needs, including vegan, gluten-free, and high-protein diets. For instance, a report by the International Union of Food Science and Technology (IUFoST) highlighted the use of diverse food materials in 3D printing, including fruits, vegetables, and plant-based proteins. Such innovations not only enhance the nutritional value of 3D-printed food but also cater to the growing demand for personalized nutrition plans. Additionally, there is a strong focus on sustainability within the industry. By enabling on-demand production and precise portioning, 3D food printing significantly reduces food waste, addressing one of the major environmental concerns in the food sector. Furthermore, the development of sustainable materials, such as biodegradable packaging or eco-friendly ingredients, demonstrates the industry's commitment to minimizing its environmental impact.
Integration with AI, IoT, and Growing Commercial Applications
The integration of 3D food printing with advanced technologies such as artificial intelligence (AI) and the Internet of Things (IoT) is revolutionizing food production. AI-driven intelligent food systems can analyze consumer preferences, dietary data, and health information to suggest personalized recipes and optimize the printing process, improving efficiency and customization. This technological synergy enhances the precision of food production, ensuring each meal meets individual nutritional goals. Simultaneously, 3D-printed food is gaining traction in commercial applications, particularly in restaurants and cafes that seek to provide unique and visually stunning dining experiences. These establishments use 3D printing to create intricate food designs that captivate consumers. In food manufacturing, 3D printing offers the potential for mass production of customized food products, allowing companies to cater to specific market niches. However, with these innovations come important regulatory and ethical considerations, including food safety, labeling, and consumer protection, which will shape the future of 3D food printing as it becomes more widespread.
Market Challenges Analysis
High Costs and Technical Limitations
The high costs associated with 3D food printing pose a significant barrier to widespread adoption, particularly for small businesses and individual consumers. The equipment itself, including specialized 3D food printers, can be prohibitively expensive, and the cost of the specific materials needed for printing food remains a limiting factor. Additionally, ongoing research and development efforts are essential to improving the technology, but they also add to the overall cost burden. This limits the technology's accessibility, especially for businesses operating on tighter budgets. For instance, a report by the Food and Agriculture Organization (FAO) noted that the high initial costs and material expenses are significant barriers for small-scale adoption. Besides, technical limitations further complicate the adoption of 3D food printing. For instance, the current speed of most 3D food printers is relatively slow, making large-scale commercial production difficult. While the range of materials suitable for 3D printing is growing, challenges remain regarding texture, taste, and nutritional value, which are crucial for consumer satisfaction.
Regulatory Hurdles, Consumer Acceptance, and Competition
Regulatory hurdles are another major challenge for the 3D food printing industry. Ensuring that 3D-printed food adheres to food safety regulations is essential but can be complex and difficult to manage, especially as new technologies emerge. In addition, providing accurate labeling and consumer information for these novel products can be complicated, leading to potential confusion among consumers. Consumer acceptance is another key issue, with some individuals being skeptical or hesitant to try 3D-printed food due to its novelty. Cultural and social factors also play a role in influencing how receptive consumers are to this technology, with traditional food preparation methods often viewed as more trustworthy. Lastly, 3D food printing faces stiff competition from traditional food production methods, which tend to have lower costs, higher efficiency, and established distribution networks. The cost and complexity of sourcing ingredients suitable for 3D printing and distributing the final products can further hinder its competitiveness in the broader food market.
Market Segmentation Analysis:
By Ingredient:
The 3D food printing market is segmented by various ingredients, including dough, fruits and vegetables, proteins, sauces, dairy products, carbohydrates, and other ingredients like algae and yeast. Each ingredient type offers unique advantages in terms of nutrition, texture, and aesthetic appeal. Dough is widely used in confectioneries and bakeries to create intricate designs, while fruits and vegetables are popular for health-conscious consumers. Proteins, including plant-based and cultured meat, cater to the growing demand for sustainable food options. Other ingredients like algae and yeast are gaining traction for their nutritional benefits and potential to create innovative food products. The flexibility to use a variety of ingredients highlights the versatility of 3D food printing technology, allowing manufacturers to cater to diverse consumer preferences and dietary needs. As more research is conducted to expand the range of printable food materials, this segment is expected to grow, particularly in specialized food applications such as personalized nutrition and sustainable food production.
By Vertical:
The 3D food printing market is also segmented by vertical, with applications spanning education, emergency services, government, defense, and commercial sectors like retail stores, bakeries, confectioneries, restaurants, and residential consumers. In the education sector, 3D food printing is used to teach students about food technology and nutrition, while emergency services and government agencies leverage the technology for efficient food production in disaster relief situations. In the commercial sector, bakeries and confectioneries utilize 3D printers to create customized designs and enhance aesthetic appeal, attracting customers with unique offerings. Restaurants are adopting 3D printing to create personalized dishes and improve efficiency. Residential users are also exploring 3D food printers for personalized meal preparation at home. The versatility of 3D food printing across these verticals underscores its potential to revolutionize the food industry by offering customization, efficiency, and innovation in various settings. This growing adoption is likely to drive further advancements in the technology, expanding its reach in both commercial and residential applications.
Segments:
Based on Ingredient:
- Dough
- Fruits and vegetables
- Proteins
- Sauces
- Dairy Products
- Carbohydrates
Based on Vertical:
- Education
- Emergency Services
- Government
- Defense
- Commercial
- Retail Store
- Bakeries
- Confectioneries
- Restaurants
- Residential
Based on Technology:
- Extrusion-based printing
- Binder jetting
- Selective laser sintering
- Inkjet printing
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the global 3D food printing market, accounting for over 35% of the total market in 2023. The region's leadership is driven by technological advancements, strong consumer demand for personalized food options, and the presence of key players pioneering 3D printing technologies. The United States, in particular, is at the forefront of the market, with a growing number of restaurants, bakeries, and food manufacturing companies adopting 3D food printing solutions. Additionally, the region benefits from substantial investment in research and development, focusing on improving 3D printing materials, processes, and applications across various sectors such as defense, healthcare, and retail. The increasing awareness of sustainability and reduced food waste also propels the market's growth in North America, as 3D printing allows for precise portioning and on-demand food production, minimizing excess.
Europe
Europe follows closely behind North America, holding a market share of around 30%. The region's growth is fueled by the rising demand for innovative food solutions, particularly in countries like Germany, the UK, and the Netherlands. European consumers have shown a strong preference for sustainable food production, which aligns with the capabilities of 3D food printing, such as reducing waste and utilizing alternative food sources like plant-based proteins and algae. Moreover, Europe has a robust regulatory framework supporting food safety and innovation, encouraging companies to explore new applications for 3D food printing in commercial sectors such as restaurants and bakeries. The region also sees growing interest in integrating 3D food printing into the healthcare and education sectors, further broadening the market's potential. European companies are continuously investing in new technologies and materials to stay competitive in this evolving industry.
Key Player Analysis
- byFlow B.V. (Netherlands)
- CandyFab (US)
- Choc Edge (UK)
- Wiiboox (China)
- TNO (Netherlands)
- 3D Systems (US)
- ZMORPH S.A (Poland)
- Systems & Materials Research Corporation (US)
- NATURAL MACHINES (Spain)
- beehex (US)
Competitive Analysis
The competitive landscape of the 3D food printing market is characterized by a mix of established and emerging players, each vying for innovation and market share. Leading companies such as 3D Systems, TNO, NATURAL MACHINES, Choc Edge, Systems & Materials Research Corporation, byFlow B.V., beehex, CandyFab, ZMORPH S.A, and Wiiboox are at the forefront of technological advancements. These companies leverage unique printing technologies, such as extrusion-based printing and selective laser sintering, to offer diverse food products tailored to consumer preferences. With a focus on customization and sustainability, these key players are investing in R&D to enhance product offerings and streamline production processes. Strategic partnerships and collaborations are also prevalent, as companies aim to expand their market presence and cater to the growing demand for personalized food experiences. As competition intensifies, innovation and adaptability will be crucial for maintaining a competitive edge in this evolving market.
Recent Developments
- In January 2024, Cocuus announced its plans to produce 1,000 tonnes of 3D-printed plant-based bacon in 2024 at its newly opened facility in Northern Spain, pioneering industrial-scale production for retail distribution. The company has introduced its plant-based bacon in 400 Carrefour supermarkets and plans to expand production to include vegan tuna and shrimp.
- In September 2023, SavorEat Ltd. and Sodexo launched the first 3D-printing robot for plant-based burgers at the University of Denver two years after announcing their partnership in 2021. This collaboration aims to expand Sodexo’s plant-based offerings and reduce its carbon footprint, aligning with its commitment to make 42% of its college and university plant-based by 2025.
- In February 2022, FELIXprinters launched a new line of 3D food printers designed to revolutionize food preparation and presentation. These printers can create intricate designs with various edible materials, including chocolate and avocado, improving kitchen efficiency and addressing issues like food waste and swallowing difficulties. With options for single or dual print heads, these printers offer versatile and creative solutions for both commercial and industrial kitchens.
Market Concentration & Characteristics
The market concentration of 3D food printing is characterized by a mix of established players and emerging startups, creating a dynamic and competitive environment. While a few key companies dominate the market, such as 3D Systems and NATURAL MACHINES, numerous smaller firms are entering the space, driving innovation and diversification in product offerings. This fragmentation fosters a competitive landscape where businesses continuously seek to enhance their technologies and develop unique applications for 3D food printing. The industry exhibits a strong focus on customization and personalization, catering to individual dietary needs and preferences. Additionally, companies are increasingly emphasizing sustainability by exploring eco-friendly materials and reducing food waste through on-demand production. As consumer interest in novel culinary experiences grows, the market is witnessing a surge in investment and research aimed at advancing 3D food printing technologies. Overall, the market's characteristics highlight its potential for growth and transformation in the food industry.
Report Coverage
The research report offers an in-depth analysis based on Ingredient, Vertical, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The 3D food printing market is projected to reach approximately USD 1,675.913 million by 2032, indicating significant growth potential.
- Enhanced printing technologies will lead to faster and more efficient production processes in the food industry.
- Integration of AI and IoT will facilitate personalized nutrition solutions and optimized food preparation methods.
- Sustainability initiatives will focus on reducing food waste through on-demand production and utilizing eco-friendly materials.
- The range of printable materials will expand, allowing for more diverse and customized food options tailored to individual dietary needs.
- Increasing consumer awareness and acceptance of 3D-printed food will drive market adoption and growth.
- Restaurants and food service providers will leverage 3D printing to create unique culinary experiences that attract customers.
- Regulatory frameworks will develop to ensure food safety and transparency in labeling for 3D-printed products.
- Ongoing research and development efforts will address current technical limitations and enhance material properties for better food quality.
- The competitive landscape will become more dynamic, with both established companies and startups innovating to capture market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Personalized Nutrition and Customization
3D food printing enables precise control over ingredients, textures, and nutrient profiles, allowing for the creation of meals tailored to individual dietary needs and preferences. This capability is particularly valuable for consumers with allergies, intolerances, or specific health goals, driving adoption in both healthcare and commercial food sectors.
Sustainability and Food Waste Reduction
The technology supports on-demand production and exact portioning, significantly reducing food waste by minimizing overproduction and repurposing nearly expiring ingredients. This aligns with global sustainability initiatives and appeals to environmentally conscious consumers and businesses seeking cost savings.
Innovative Food Design and Culinary Experiences
3D food printing allows chefs and manufacturers to create intricate shapes, textures, and visually appealing dishes that are difficult to achieve with traditional methods. This innovation enhances the dining experience, especially in high-end restaurants and event catering, attracting consumers seeking unique and memorable culinary offerings.
Advancements in Printing Materials and Technologies
Ongoing improvements in 3D printing hardware, software, and printable food materials - including plant-based proteins and alternative ingredients - are expanding the range of applications and making the technology more accessible. These advancements increase efficiency, lower operational barriers, and support the development of new food products.
Integration with AI and IoT for Enhanced Efficiency
The incorporation of artificial intelligence and Internet of Things technologies enables intelligent recipe customization, real-time monitoring, and process optimization. This integration streamlines food production, improves consistency, and supports the delivery of personalized nutrition at scale, further driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of 3D Food Printing Market?
What factors are driving the growth of the 3D Food Printing market?
What are the key segments within the 3D Food Printing market?
What are some challenges faced by the 3D Food Printing market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vertical
- 1.2.1 Education
- 1.2.2 Emergency Services
- 1.2.3 Government & Defense
- 1.2.4 Commercial (Retail Stores, Bakeries, Confectioneries, Restaurants)
- 1.2.5 Residential
- 1.3 By Ingredient
- 1.3.1 Dough
- 1.3.2 Fruits and Vegetables
- 1.3.3 Proteins
- 1.3.4 Sauces
- 1.3.5 Dairy Products
- 1.3.6 Carbohydrates
- 1.4 By Technology
- 1.4.1 Extrusion-based Printing
- 1.4.2 Binder Jetting
- 1.4.3 Selective Laser Sintering
- 1.4.4 Inkjet Printing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 395 million → 2032: USD 1,675.913 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 3D Food Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 3D Food Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 3D Food Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 3D Food Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 3D Food Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 3D Food Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global 3D Food Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 3D Food Printing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 395 million → 2032: USD 1,675.913 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 3D Food Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vertical - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Education
- 12.3.7.2 Emergency Services
- 12.3.7.3 Government & Defense
- 12.3.7.4 Commercial (Retail Stores, Bakeries, Confectioneries, Restaurants)
- 12.3.7.5 Residential
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Ingredient - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dough
- 12.4.7.2 Fruits and Vegetables
- 12.4.7.3 Proteins
- 12.4.7.4 Sauces
- 12.4.7.5 Dairy Products
- 12.4.7.6 Carbohydrates
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Extrusion-based Printing
- 12.5.7.2 Binder Jetting
- 12.5.7.3 Selective Laser Sintering
- 12.5.7.4 Inkjet Printing
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global 3D Food Printing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 3D Food Printing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 3D Food Printing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 3D Food Printing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3D Systems
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 NATURAL MACHINES
- 18.4 beehex
- 18.5 byFlow B.V.
- 18.6 Choc Edge
- 18.7 CandyFab
- 18.8 Wiiboox
- 18.9 TNO
- 18.10 ZMORPH S.A
- 18.11 Systems & Materials Research Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

