
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
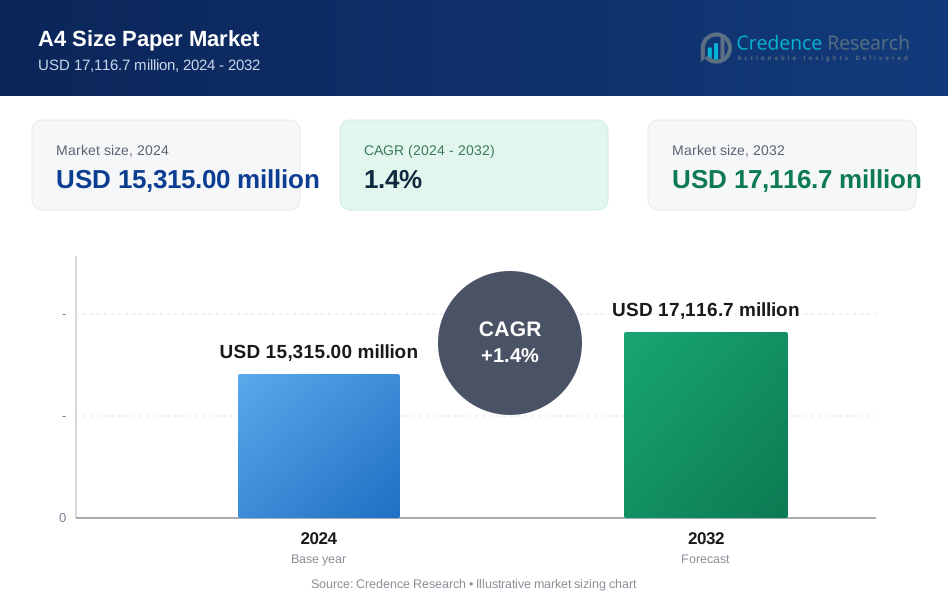
| A4 Size Paper Market Size 2024 | USD 15,315.00 million |
| A4 Size Paper Market, CAGR | 1.4% |
| A4 Size Paper Market Size 2032 | USD 17116.7 million |
Market Overview:
The A4 Size Paper Market is projected to grow from USD 15,315.00 million in 2024 to an estimated USD 17116.7 million by 2032, with a compound annual growth rate (CAGR) of 1.4% from 2024 to 2032.
The market is primarily driven by consistent demand from educational institutions, government agencies, and corporate offices. These sectors rely heavily on physical documentation for exams, administrative tasks, compliance, legal processes, and archival purposes. The expansion of small and medium-sized enterprises (SMEs) and the rise in e-commerce also boost demand for printed invoices, packaging documents, and promotional materials. Additionally, specialty papers such as glossy, matte, and recycled A4 formats are gaining traction in creative, environmental, and corporate applications. The market is also benefiting from the rising preference for eco-friendly paper solutions, spurred by environmental regulations and increasing awareness among consumers and organizations. While digital transformation and paperless initiatives pose challenges, the need for physical documentation in regulated and resource-limited environments helps maintain a baseline demand. Volatility in raw material prices and environmental compliance costs remain key concerns for manufacturers, prompting investments in sustainable practices and efficient production technologies.
Regionally, Asia-Pacific holds the largest market share due to its dense population, expanding educational systems, and rapid urbanization, especially in countries like India, China, and Indonesia. The region's growth is further supported by an expanding base of SMEs and increasing literacy rates. North America and Europe represent mature markets with slower growth but strong per-capita consumption, bolstered by legal standards, continued office usage, and commercial printing activities. Regulatory frameworks in these regions also drive innovation in sustainable paper production. In contrast, Latin America, the Middle East, and Africa are emerging as growth regions, with improving digital literacy and expanding infrastructure creating new demand for standardized A4 formats. These regions present long-term opportunities as governments and institutions adopt more formalized documentation systems. Overall, the A4 size paper market remains resilient and diversified across geographies, supported by enduring institutional needs and evolving environmental priorities.
Market Insights:
- The A4 Size Paper Market is projected to grow from USD 15,315.00 million in 2024 to USD 17,116.7 million by 2032, registering a CAGR of 1.4%, reflecting steady demand despite increasing digitalization.
- Consistent usage across educational institutions and government agencies drives year-round demand, as printed documents remain essential for exams, legal records, and administrative compliance in many regions.
- Corporate offices and the global expansion of SMEs significantly contribute to sustained consumption, with A4 paper being a standard medium for invoicing, contracts, reporting, and documentation.
- The rise of e-commerce and remote work has increased demand for printed materials such as shipping labels, product guides, and branding collateral, which rely heavily on standard A4 formats.
- Specialty papers like recycled, glossy, and colored A4 variants are gaining traction due to growing interest in personalized and sustainable print solutions across creative, environmental, and commercial sectors.
- Digital transformation and paperless initiatives continue to challenge the market, particularly in developed regions, urging producers to add value through hybrid applications and innovative product features.
- Asia-Pacific dominates the global market due to its population scale, urban growth, and expanding educational infrastructure, while North America and Europe lead in per-capita usage and sustainable paper innovation.
Market Drivers:
Sustained Demand from Educational and Government Institutions Supports Market Stability:
The A4 Size Paper Market benefits significantly from steady demand across educational institutions and government bodies. Schools, colleges, and universities continue to rely on A4 paper for assignments, examinations, and administrative documentation. Government agencies use A4 paper extensively for record-keeping, legal documentation, and correspondence. These segments require large volumes of standardized paper formats to maintain operational efficiency and regulatory compliance. Despite digitalization efforts, paper remains critical in regions with limited technological infrastructure or legal mandates for hard-copy records. The market maintains its base volume through this ongoing institutional reliance, which sustains year-round consumption and buffers against digital disruption.
- For instance, Stora Enso achieved a 13% increase in deliveries to Finnish educational institutions, totaling 180 million sheets, supported by eco-friendly production.
Corporate Usage and SME Growth Drive Consistent Commercial Consumption:
Widespread use of A4 paper in corporate environments ensures continuous market activity. Companies across sectors utilize it for internal communication, reporting, contract printing, invoicing, and employee records. The rising number of small and medium-sized enterprises (SMEs) globally contributes to demand, particularly in developing economies. SMEs generate paperwork for operations, logistics, customer relations, and documentation, increasing consumption volume. The A4 Size Paper Market benefits from the formalization of business practices, where paper documentation still plays a central role. It supports a significant portion of printing needs for daily operations, especially where digital adoption remains partial.
- For instance, companies like Canon supplying 500 million sheets to corporate offices globally in 2024, marking a 10% year-over-year increase.
E-Commerce Expansion and Retail Printing Increase Specialty Paper Demand:
The rise of e-commerce has boosted the need for printed materials such as shipping labels, invoices, product manuals, and packaging inserts. These applications rely on A4-sized formats due to their compatibility with standard home and office printers. The proliferation of home-based businesses and remote work has also led to higher usage of consumer-grade printing materials. A4 paper in various finishes-such as matte, glossy, or colored-caters to promotional, branding, and packaging needs. The A4 Size Paper Market benefits from product diversification that serves both functional and aesthetic requirements. It continues to evolve to meet the dynamic needs of modern retail, logistics, and home office settings.
Environmental Concerns and Regulatory Trends Push Sustainable Paper Innovation:
Environmental awareness and government regulations are reshaping paper production and consumption patterns. Customers increasingly demand recycled, FSC-certified, and chlorine-free paper products, prompting manufacturers to shift towards sustainable sourcing and processing methods. Governments enforce stricter rules on deforestation and carbon emissions, creating pressure on suppliers to innovate. It encourages investment in green technologies and waste reduction measures across the supply chain. The A4 Size Paper Market is adapting to these trends by promoting eco-friendly product lines and transparency in sourcing. It enhances brand value for producers while aligning with broader sustainability commitments in both public and private sectors.
Market Trends:
Product Diversification Supports Customized and Niche Applications:
Manufacturers are expanding their product portfolios to include a wider variety of A4 paper types to meet evolving consumer and business needs. Options such as recycled paper, colored sheets, glossy and matte finishes, and high-GSM formats are gaining popularity. These variants serve distinct purposes in marketing, design, legal, and educational settings. Consumers seek paper that aligns with branding goals, printing precision, and environmental values. The A4 Size Paper Market responds to this demand with tailored offerings that improve functionality and visual appeal. It enables suppliers to access premium segments and differentiate in a highly commoditized market.
- For instance, Double A introduced a high-GSM A4 paper variant with 120 gsm weight, optimized for inkjet and laser printing, achieving 98% brightness and 4% opacity.
Sustainable Manufacturing Practices Gain Traction Across the Supply Chain:
Sustainability continues to reshape manufacturing practices in the A4 paper industry. Companies are investing in eco-friendly raw materials, including bamboo pulp and post-consumer recycled fibers, to reduce their carbon footprint. Chlorine-free bleaching, water-efficient processing, and sustainable forestry certifications are becoming industry standards. Brands emphasize transparency in their environmental impact through ecolabels and compliance with regional sustainability norms. The A4 Size Paper Market reflects a broader shift toward responsible sourcing and production, driven by consumer awareness and regulatory demands. It supports long-term competitiveness and aligns with corporate ESG goals.
- For instance, UPM-Kymmene uses bamboo pulp and post-consumer recycled fibers in 40% of its A4 paper production, employing chlorine-free bleaching and water-efficient processes.
Growth of Remote Work and Home Office Printing Drives Consumer Demand:
Remote and hybrid work models have led to increased demand for A4 paper at the consumer level. Individuals now require home-based printing solutions for contracts, forms, labels, and personal documentation. Sales of printer-compatible A4 packs have grown through e-commerce and retail outlets. Households contribute significantly to paper consumption during school-from-home sessions and freelance work. The A4 Size Paper Market benefits from this decentralization of print demand from centralized corporate hubs to millions of home offices. It creates opportunities for lightweight packaging, smaller pack sizes, and retail-specific product design.
Digital Integration with Print Technology Enhances Paper Utility:
Paper manufacturers are integrating print technology features to improve the user experience and efficiency. QR codes, watermarking, and augmented reality elements are being embedded into A4 paper for interactive applications. Such innovations enhance value for businesses using printed materials for marketing, authentication, or education. Smart packaging and traceability functions are also being explored to support logistics and documentation. The A4 Size Paper Market is adapting to coexist with digital platforms, offering hybrid functionalities that extend beyond traditional print. It strengthens the relevance of paper in an increasingly connected ecosystem.
Market Challenges Analysis:
Digital Substitution Reduces Dependence on Physical Documentation:
The widespread adoption of digital platforms continues to challenge the traditional role of A4 paper in both corporate and educational settings. Businesses are shifting toward paperless workflows, cloud-based storage, and digital signatures, reducing the need for printed materials. Educational institutions are increasing the use of digital assignments, e-books, and online assessments. Government services are also embracing electronic documentation and e-governance platforms to streamline operations. These trends directly impact volume-based demand, particularly in urban and technologically advanced regions. The A4 Size Paper Market must adapt to this digital transition by identifying new applications and integrating value-added features that maintain relevance in a paper-light environment.
Raw Material Volatility and Environmental Pressures Strain Margins:
Fluctuations in raw material prices, especially for wood pulp and recycled fibers, continue to put pressure on manufacturers’ profitability. Supply chain disruptions, energy costs, and regulatory shifts further contribute to rising operational expenses. Environmental regulations targeting deforestation, water usage, and carbon emissions add to compliance burdens for producers. Meeting sustainability targets while maintaining competitive pricing remains a significant challenge for many small and mid-sized manufacturers. The A4 Size Paper Market faces a delicate balance between scaling eco-friendly practices and protecting cost efficiency. It must navigate these pressures while ensuring consistent product quality and supply continuity in global and regional markets.
Market Opportunities:
Rising Demand in Emerging Markets Unlocks Growth Potential:
Developing countries present strong opportunities for expansion due to rising literacy rates, growing administrative needs, and infrastructure development in education and governance. Rapid urbanization and formalization of small businesses in Asia, Africa, and Latin America are increasing the need for printed documentation. Governments and institutions in these regions continue to depend on physical paperwork for compliance and record-keeping. The A4 Size Paper Market can capitalize on this demand by expanding distribution networks and offering affordable, region-specific product lines. It benefits from demographic growth and increased investment in education across these regions. Localization and efficient logistics can further strengthen market presence.
Eco-Friendly Paper Products Appeal to Sustainability-Conscious Consumers:
The growing global focus on sustainability creates a significant opportunity for innovation in recycled and responsibly sourced paper products. Customers, especially in Europe and North America, are seeking alternatives that align with environmental values. FSC certification, biodegradable packaging, and low-impact production methods enhance brand trust and drive purchasing decisions. The A4 Size Paper Market can differentiate through green product portfolios tailored to corporate sustainability goals and government procurement policies. It gains competitive advantage by aligning product development with environmental standards. This shift opens new channels in both retail and institutional segments focused on sustainable supply chains.
Market Segmentation Analysis:
By Type
White paper dominates the A4 Size Paper Market due to its widespread use in formal documentation, office printing, and academic purposes. Colored paper holds a smaller share but sees demand in creative, promotional, and educational segments.
- For instance, HP reported that over 85% of its global A4 paper shipments in 2024 were white paper, reflecting its preference for business and institutional clients.
By Application
The office segment leads in volume, driven by extensive use in corporate communications, reports, and record-keeping. Educational institutions follow closely, using A4 paper for exams, assignments, and administrative needs. Print shops and commercial users rely on it for brochures, forms, and manuals, while home usage is growing with remote work and school-from-home trends.
- For instance, Print shops and commercial users rely on it for brochures, forms, and manuals, with Brother reporting that 15% of its A4 paper sales in 2024 were to commercial printing businesses.
By Material
Virgin paper maintains a strong lead due to its consistent quality and print performance. Recycled paper is gaining ground as sustainability becomes a priority for businesses and institutions.
By Thickness
70–80 gsm paper is the most commonly used, offering cost-effective printing for daily needs. The 81–100 gsm range serves higher-quality documentation, while 101–120 gsm is used in premium and branded printing applications.
By Distribution Channel
Offline sales dominate due to bulk procurement by businesses, schools, and government offices. Online channels are expanding, driven by retail demand and the convenience of home delivery.
Segmentation:
By Type
- White Paper
- Colored Paper
By Application
- Office
- Home
- Print Shop
- Educational Institutions
- Commercial
- Others
By Material
- Recycled
- Virgin
By Thickness
- 70–80 gsm
- 81–100 gsm
- 101–120 gsm
By Distribution Channel
- Online
- Offline
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Asia-Pacific Holds the Largest Market Share Driven by Population and Institutional Demand
Asia-Pacific dominates the A4 Size Paper Market, accounting for approximately 40% of the global market share. High population density, expanding educational institutions, and growing governmental documentation requirements fuel this regional demand. Countries like China, India, and Indonesia continue to invest in education infrastructure, literacy programs, and administrative capacity, increasing the need for standardized paper formats. The rise of small and medium-sized enterprises further strengthens consumption through office documentation, billing, and logistics paperwork. Rapid urbanization and ongoing industrialization in emerging economies sustain growth across both public and private sectors. The region benefits from domestic manufacturing capabilities and cost-effective supply chains, reinforcing its leadership position.
North America and Europe Maintain Strong Usage with Focus on Sustainability
North America and Europe together hold around 35% of the global A4 Size Paper Market, supported by well-established corporate and legal systems. In these mature markets, per-capita paper usage remains high, especially in sectors like education, healthcare, law, and commercial printing. Regulatory frameworks in both regions encourage the use of sustainable paper products, leading to increased adoption of recycled and FSC-certified variants. Organizations are balancing digital transformation with hybrid print-digital workflows, preserving the role of A4 paper in daily operations. Environmental compliance requirements and consumer preference for green products push innovation in paper manufacturing. The market remains stable in these regions due to continued demand for quality, traceable paper sources.
Emerging Regions Offer Growth Potential Through Infrastructure Expansion
Latin America, the Middle East, and Africa collectively contribute about 25% to the A4 Size Paper Market, with opportunities emerging through infrastructure development and formalization of administrative systems. Countries in these regions are witnessing improved literacy rates and increasing investments in education, which support long-term demand. Government institutions continue to rely on physical documentation in legal and public service workflows. Growth in small businesses and rising digital literacy also create new use cases for printed communication and records. Limited digital penetration in rural and semi-urban areas ensures that physical paper remains essential. These regions represent strategic markets for suppliers looking to expand distribution networks and capture first-mover advantages.
Key Player Analysis:
- HP (U.S.)
- Staples (U.S.)
- Brother (Japan)
- Hammermill (U.S.)
- Kodak (U.S.)
- Deli (China)
- Canon (Japan)
- International Paper (U.S.)
- UPM-Kymmene (Finland)
- Stora Enso (Sweden/Finland)
- Asia Pulp & Paper (APP, Indonesia)
- Sappi (South Africa)
- Double A (Thailand)
- JK Paper (India)
- Mondi Group (UK/Austria)
- Domtar (U.S./Canada)
Competitive Analysis:
The A4 Size Paper Market features a mix of global and regional players competing on product quality, distribution reach, and sustainability. Major companies like HP, Canon, Brother, and Staples leverage strong brand equity and global distribution networks to maintain market share. International Paper, UPM-Kymmene, Stora Enso, and Asia Pulp & Paper dominate in terms of scale, offering a wide range of paper grades with a focus on sustainable sourcing. Regional manufacturers such as JK Paper, Double A, and Sappi serve local markets efficiently with competitive pricing and tailored products. Companies are investing in recycled paper production and eco-friendly certifications to meet rising environmental expectations. Product differentiation based on thickness, finish, and packaging remains a key strategy. The A4 Size Paper Market remains moderately fragmented, with both price competition and quality differentiation shaping vendor strategies. It rewards suppliers who combine operational efficiency with product innovation and environmental compliance.
Recent Developments:
- In April 2025, HP launched nine new LaserJet A4 printers, including Wi-Fi models, and introduced the HP LaserJet Enterprise 8000 Series with advanced security features.
- In April 2025, Brother received the BLI 2025 A4 Line of the Year Award for its new mono laser printer range, recognized for quality and security.
- At Printpack India 2025, Kodak showcased the new PROSPER Print Bar for high-speed A4 inkjet printing, targeting commercial and book printing.
Market Concentration & Characteristics:
The A4 Size Paper Market is moderately concentrated, with a few global players holding significant market share alongside numerous regional and local manufacturers. It is characterized by high-volume production, standardized product specifications, and price-sensitive demand. Large firms like International Paper, UPM-Kymmene, and Asia Pulp & Paper benefit from scale, integrated supply chains, and global distribution. Regional producers compete through cost efficiency, proximity to end users, and product customization. The market shows stable demand from institutional and commercial segments, but it faces margin pressure due to raw material volatility and growing sustainability requirements. It continues to balance operational scale with the need for environmentally compliant, value-added paper products.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Material, By Distribution Channel and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand from educational institutions and government bodies will sustain baseline volume in developing economies.
- Growth in e-commerce and home offices will continue to drive consumer-level paper usage.
- Manufacturers will expand eco-friendly product lines to align with rising sustainability mandates.
- Digital substitution will slow growth in mature markets, shifting focus to value-added paper segments.
- Emerging economies in Asia, Africa, and Latin America will offer long-term expansion opportunities.
- Innovation in packaging, finishes, and paper thickness will help differentiate brands and maintain relevance.
- Online distribution channels will gain traction due to increasing retail and direct-to-consumer sales.
- Strategic partnerships and capacity upgrades will improve supply chain efficiency and cost control.
- Environmental regulations will influence raw material sourcing and production technologies.
- The A4 Size Paper Market will remain stable, with steady demand across institutional and commercial applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the A4 Size Paper Market?
What factors are driving the growth of the A4 Size Paper Market?
What are some challenges faced by the A4 Size Paper Market?
Who are the major players in the A4 Size Paper Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 A4 Size Paper Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global A4 Size Paper Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 15,315.00 million → 2032: USD 17,116.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 A4 Size Paper Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. A4 Size Paper Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 A4 Size Paper Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 A4 Size Paper Market Drivers
- 3.3 A4 Size Paper Market Restraints & Challenges
- 3.4 A4 Size Paper Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 A4 Size Paper Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 A4 Size Paper Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, A4 Size Paper category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 A4 Size Paper Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. A4 Size Paper Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the A4 Size Paper market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 A4 Size Paper Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 A4 Size Paper Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 A4 Size Paper Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in A4 Size Paper (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New A4 Size Paper Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global A4 Size Paper Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America A4 Size Paper Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe A4 Size Paper Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific A4 Size Paper Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America A4 Size Paper Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East A4 Size Paper Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa A4 Size Paper Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. A4 Size Paper Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
