
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Acid Citrate Dextrose (ACD) Tubes Market Size 2024 | USD 540.6 Million |
| Acid Citrate Dextrose (ACD) Tubes Market, CAGR | 5% |
| Acid Citrate Dextrose (ACD) Tubes Market Size 2032 | USD 798.71 Million |
Market Overview
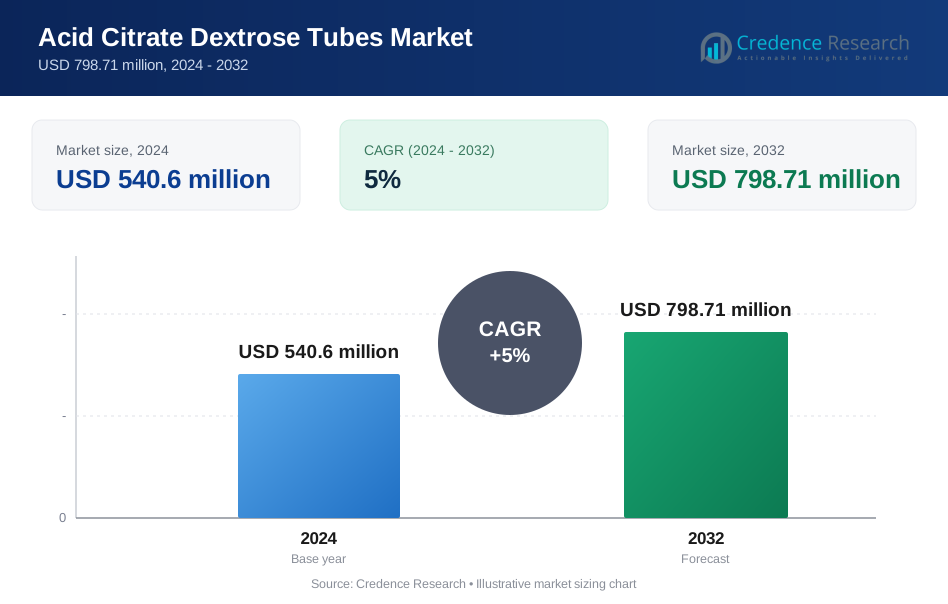
The Acid Citrate Dextrose (ACD) Tubes Market is projected to grow from USD 540.6 million in 2024 to an estimated USD 798.71 million by 2032, with a compound annual growth rate (CAGR) of 5% from 2024 to 2032.
Key drivers of the ACD tubes market include the increasing demand for blood collection tubes in healthcare settings, particularly for diagnostic testing and blood banking. The growing prevalence of chronic diseases, along with the expansion of medical research and clinical trials, is contributing to a rise in blood sample collection, driving the market for ACD tubes. Furthermore, ACD tubes are preferred in blood collection due to their ability to preserve blood components for longer periods, making them crucial in transfusion medicine and other clinical applications.
Technological advancements in blood collection devices, including innovations that improve the efficiency and safety of the collection process, are also supporting market growth. The adoption of automated systems for blood collection and storage, which help improve accuracy and reduce human error, is another factor boosting demand for ACD tubes. Additionally, the growing emphasis on personalized medicine and the increasing number of blood tests being conducted worldwide further contribute to the demand for these tubes. Regionally, North America and Europe are leading the ACD tubes market due to advanced healthcare infrastructure, high awareness of diagnostic procedures, and a large number of research institutions and blood banks. In Asia Pacific, the market is expected to witness significant growth, driven by rising healthcare expenditures, increasing healthcare infrastructure, and growing demand for blood collection tubes in countries like China, India, and Japan. Latin America and the Middle East & Africa regions are also seeing steady growth in the ACD tubes market, supported by improving healthcare systems and the expansion of medical research initiatives.
Market Insights
- The Acid Citrate Dextrose (ACD) Tubes Market is expected to grow from USD 540.6 million in 2024 to USD 798.71 million by 2032, with a CAGR of 5% from 2024 to 2032.
- Increasing demand for diagnostic testing and blood collection procedures in healthcare and research sectors is driving the growth of the ACD tubes market.
- The rising prevalence of chronic diseases and the expanding clinical research and trials market are major factors contributing to market growth.
- Technological advancements in blood collection devices, along with the growing adoption of automated systems, are enhancing the demand for ACD tubes.
- Challenges such as the high cost of certain blood collection systems and regulatory issues surrounding medical device approvals may hinder market growth.
- North America and Europe dominate the ACD tubes market due to advanced healthcare infrastructure, high awareness, and strong research activities.
- The Asia Pacific region is expected to experience significant market growth, driven by expanding healthcare infrastructure and increasing demand for medical supplies.
Market Drivers
Increasing Demand for Diagnostic Testing
The increasing need for diagnostic testing is driving the demand for blood collection tubes such as Acid Citrate Dextrose (ACD) tubes. The rise in chronic diseases such as diabetes, cardiovascular conditions, and cancer has substantially boosted the volume of blood tests performed globally. For instance, the World Health Organization (WHO) reports that 422 million people worldwide have diabetes, a condition that requires regular diagnostic testing. As a result, healthcare systems are seeing a surge in demand for diagnostic tools, including blood collection tubes. This growing demand is directly influencing the need for ACD tubes, ensuring their critical role in the medical testing process.
Growth in Medical Research and Clinical Trials
Medical research and clinical trials are key drivers of the ACD tubes market. The increasing global investment in healthcare research is encouraging pharmaceutical companies and research institutions to conduct more clinical studies. For instance, in 2023, the U.S. National Institutes of Health (NIH) allocated $47 billion to medical research, marking a 3.5% increase from 2022. Clinical trials are essential for the advancement of medical treatments and require reliable blood collection systems to ensure accurate results. As the number of clinical trials and studies increases globally, the demand for high-quality blood collection tools like ACD tubes rises, as these tubes help preserve blood samples during testing.
Technological Advancements in Blood Collection Devices
Technological innovations in blood collection devices have also played a crucial role in increasing the demand for ACD tubes. For instance, the U.S. Food and Drug Administration (FDA) approved over 10 blood collection device innovations in 2022 alone. These technologies, which include automated blood collection systems, have enhanced the efficiency, accuracy, and safety of the blood collection process. With the increasing adoption of these automated systems in hospitals and clinics, the need for high-quality blood collection tubes like ACD tubes has surged, as they are required to meet the higher standards set by these devices.
Rising Healthcare Investments in Emerging Markets
Rising healthcare investments in emerging markets are contributing to the growth of the ACD tubes market. For instance, India’s Ministry of Health and Family Welfare allocated ₹2.23 lakh crore (approximately $30 billion) for healthcare spending in 2023. This increased spending in healthcare infrastructure, combined with a growing population, is expanding the need for medical supplies, including diagnostic tools such as ACD tubes. These emerging markets are seeing significant growth in their healthcare sectors, which directly influences the demand for ACD tubes to meet the rising need for blood testing.
Market Trends
Expansion of Blood Collection in Healthcare Settings
One of the most notable trends in the ACD tubes market is the growing use of blood collection tubes in healthcare settings. As healthcare systems around the world modernize, the demand for high-quality blood collection systems increases. For instance, the European Union’s healthcare expenditure reached €1.7 trillion in 2023, and the region’s healthcare spending continues to rise annually. This surge in healthcare investments has led to an increase in diagnostic testing, particularly blood testing, thereby driving the demand for reliable and efficient blood collection tubes like ACD tubes. Governments are emphasizing the importance of diagnostic testing for disease prevention, fueling this trend.
Advancements in Automation for Blood Collection
Automation in blood collection devices is another key trend in the market. Many healthcare facilities are adopting automated blood collection systems to improve efficiency and reduce human error. For instance, in 2022, the U.S. Department of Health and Human Services (HHS) allocated $10 billion for the enhancement of healthcare technologies, including automated devices for blood collection. These systems reduce the time needed for sample processing and enhance accuracy, contributing to the increased demand for specialized blood collection tubes such as ACD tubes, which are designed to work seamlessly with these technologies.
Increased Focus on Personalized Medicine
Personalized medicine is driving growth in diagnostic testing, which in turn supports the ACD tubes market. For Instance, The U.S. Food and Drug Administration (FDA) has approved over 40 new personalized medicines in 2023, significantly increasing the need for precise blood collection methods. Personalized treatments often require frequent blood tests to monitor patient responses, thus enhancing the demand for high-quality ACD tubes capable of preserving blood samples for accurate testing.
Government Support for Healthcare Infrastructure
Governments across emerging markets are increasingly investing in healthcare infrastructure, which is expected to boost the demand for blood collection tubes. For example, in 2023, the Brazilian government allocated RS$ 189 billion for health sector investments, with a significant portion directed towards improving diagnostic services. This investment is expected to increase the demand for medical tools such as ACD tubes as more healthcare facilities expand and enhance their diagnostic capabilities.
Market Challenges Analysis
Regulatory and Compliance Challenges
One of the key challenges in the ACD tubes market is the stringent regulatory and compliance requirements imposed by governments and health authorities. Blood collection devices, including ACD tubes, are subject to rigorous regulations to ensure safety, quality, and effectiveness. For instance, the U.S. Food and Drug Administration (FDA) mandates that blood collection tubes undergo extensive testing and certification before they can be marketed. Manufacturers must comply with these regulations, which can result in lengthy approval processes and increased costs. Furthermore, international regulations differ significantly, which can complicate market entry for companies looking to expand globally. In the European Union, the Medical Device Regulation (MDR) introduced in 2021 places additional responsibilities on manufacturers to ensure continuous product monitoring and post-market surveillance. These regulatory hurdles can delay product launches and create challenges for companies seeking to maintain compliance across multiple regions.
Supply Chain and Cost Management Issues
Another significant challenge faced by the ACD tubes market is the complexity of the supply chain and cost management. Blood collection tube manufacturers rely on raw materials such as plastic, glass, and chemical agents that are used to preserve blood samples. Disruptions in the supply of these materials, such as those caused by global supply chain issues or geopolitical tensions, can lead to production delays and increased costs. For example, the COVID-19 pandemic created significant disruptions in the global supply chain, affecting the availability of key raw materials used in medical devices. In addition to raw material costs, transportation and logistics expenses are also rising, further increasing the overall cost of manufacturing ACD tubes. This puts pressure on manufacturers to balance cost-efficiency with product quality, a challenge that many companies continue to grapple with. the World Bank reported that global supply chain disruptions led to an average increase in production costs by 10-15% in 2022.
Market Opportunities
The Acid Citrate Dextrose (ACD) Tubes Market presents significant opportunities driven by advancements in diagnostic technologies and the growing emphasis on personalized medicine. With the rise in chronic diseases such as diabetes, cardiovascular disorders, and cancer, there is an increased demand for diagnostic tests, leading to a higher volume of blood sample collection. This, in turn, creates opportunities for ACD tube manufacturers to expand their product offerings and develop innovative solutions tailored to specific diagnostic and research needs. Moreover, the global push for precision medicine and personalized healthcare is fueling the demand for more accurate and efficient blood collection systems, creating room for ACD tubes to cater to the evolving needs of healthcare providers. By focusing on developing next-generation blood collection technologies that ensure better preservation of blood components, companies can capture a larger market share and align with the trend toward advanced healthcare practices.
In addition, the expanding healthcare infrastructure in emerging economies presents a significant growth opportunity for the ACD tubes market. Countries such as China, India, and Brazil are investing heavily in healthcare systems, improving their diagnostic capabilities, and establishing more research facilities. This creates a favorable environment for the adoption of ACD tubes in both routine clinical settings and advanced medical research. Furthermore, increased government initiatives and public-private partnerships aimed at enhancing healthcare accessibility in these regions can lead to a higher demand for quality blood collection solutions. By targeting these emerging markets with cost-effective and high-performance products, ACD tube manufacturers can capitalize on the expanding healthcare landscape and drive long-term growth in these regions.
Market Segmentation Analysis
By Type
The Acid Citrate Dextrose (ACD) tubes market is segmented based on the type of ACD solution used, which includes ACD solution A and ACD solution B. ACD solution A is primarily used in blood banking and hematology applications due to its ability to preserve red blood cells. ACD solution B, on the other hand, is preferred for plasma and platelet preservation, making it suitable for clinical and research applications. The demand for each type is influenced by its specific use case, with solution A seeing a larger share in blood donation and solution B gaining popularity in specialized diagnostic and therapeutic areas.
By Technology
Technological advancements in blood collection systems are contributing to the growth of the ACD tubes market. Automation is a key trend, with the development of automated blood collection systems enhancing accuracy and reducing the risk of human error. These technologies are particularly beneficial in high-volume blood collection environments, such as hospitals and research labs. Additionally, innovations aimed at improving tube material, sealing techniques, and preservation features are driving the adoption of advanced ACD tubes, making them more reliable for longer-term storage of blood samples.
By End-User
The ACD tubes market is segmented by end-user, including hospitals, diagnostic laboratories, research institutions, and blood banks. Hospitals are the largest end-users, driven by their need for blood collection in routine diagnostics and emergency settings. Diagnostic laboratories also account for a significant share, driven by the increasing volume of diagnostic tests conducted. Research institutions and blood banks are seeing growing demand for ACD tubes due to the need for blood preservation in clinical trials and blood donation programs.
Segmentations
Based on Type:
- ACD Solution A
- ACD Solution B
Based on Technology:
- Automated Blood Collection Systems
- Manual Blood Collection Systems
Based on End-User:
- Hospitals
- Diagnostic Laboratories
- Research Institutions
- Blood Banks
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a dominant share of the ACD tubes market, accounting for 40% of the global market. The U.S. is the leading contributor to this growth due to its advanced healthcare infrastructure, high healthcare spending, and significant research investments. The Centers for Disease Control and Prevention (CDC) reports that the U.S. conducts over 1 billion diagnostic tests annually, which significantly boosts the demand for blood collection tubes. In addition, the U.S. FDA’s stringent regulations ensure that only high-quality and compliant blood collection devices, such as ACD tubes, are used in medical settings. The strong presence of key market players in the region, along with an increasing focus on personalized medicine, further fuels demand. For instance, in 2022, the U.S. Department of Health and Human Services (HHS) allocated over $10 billion for healthcare technology enhancements, including blood collection systems, further driving market expansion.
Europe
Europe accounts for 30% of the global ACD tubes market share. Countries such as Germany, the United Kingdom, and France are the key contributors to this market, primarily due to their advanced healthcare systems and high demand for diagnostic testing. The European Union’s healthcare expenditure reached €1.7 trillion in 2023, which is expected to continue to rise, promoting the need for high-quality blood collection solutions. In addition, the introduction of the European Union’s Medical Device Regulation (MDR) in 2021 has increased the focus on the safety and effectiveness of medical devices, further boosting the demand for reliable blood collection tubes like ACD. The region also sees significant research activity, with numerous clinical trials being conducted, creating a growing demand for ACD tubes to maintain blood sample integrity.
Asia Pacific
Asia Pacific is experiencing rapid growth and is expected to hold a 25% share of the ACD tubes market by 2032. Countries such as China, India, and Japan are investing heavily in healthcare infrastructure, making it one of the fastest-growing regions for medical device adoption. For instance, China’s healthcare expenditure reached ¥7.1 in 2023, which has translated into increased demand for medical products like ACD tubes. With an expanding population and rising incidence of chronic diseases, the demand for blood collection solutions is expected to rise significantly. Additionally, technological advancements and increased focus on improving healthcare accessibility in emerging markets are contributing to the growth of the ACD tubes market in the region.
Key Player Analysis
- Becton, Dickinson and Company (BD)
- Thermo Fisher Scientific Inc.
- Roche Diagnostics
- Siemens Healthineers
- Greiner Bio-One International GmbH
- Sarstedt AG & Co. KG
- Abbott Laboratories
- Bio-Rad Laboratories, Inc.
- Hologic, Inc.
- Medtronic plc
Competitive Analysis
The ACD tubes market is highly competitive, with several global and regional players vying for market share. Key companies like Becton, Dickinson and Company (BD), Thermo Fisher Scientific, and Roche Diagnostics lead the market, offering a broad range of blood collection products and technologies. These companies are continuously innovating, focusing on the development of advanced automated blood collection systems and improving tube materials to enhance performance. For instance, BD recently launched a new blood collection system that integrates automation for enhanced precision and reduced error rates. Regional players such as Greiner Bio-One and Sarstedt AG are also significant contributors, leveraging their expertise in manufacturing cost-effective blood collection solutions tailored to local market needs. The competition is further intensified by ongoing investments in research and development, regulatory compliance, and strategic partnerships, particularly in emerging markets such as Asia Pacific, where healthcare infrastructure is rapidly growing.
Recent Developments
- In October 2024, BD announced that its Vacutainer® Citrate Blood Collection Tubes met all non-clinical testing requirements, demonstrating substantial equivalence to predicate devices. The performance tests confirmed clinical equivalence for coagulation parameters, supporting the reliability of their ACD tubes in clinical settings.
- In January 2025, Thermo Fisher launched an updated line of Dextrose products, enhancing its blood collection and diagnostic offerings. This update includes improvements to the formulation of their ACD tubes, aimed at improving sample preservation and stability.
- In November 2024, Roche released its fourth-quarter results for fiscal year 2024, highlighting advancements in its diagnostics portfolio, including blood collection systems featuring ACD tubes. The company emphasized the importance of these tubes in maintaining sample integrity for various diagnostic tests.
- In November 2024, Siemens Healthineers reported achieving its fiscal year 2024 targets and highlighted ongoing developments in its blood collection systems that incorporate ACD tubes. These systems are part of their integrated solutions for laboratories.
- In January 2025, Greiner Bio-One announced the completion of a new sterilization facility in Kremsmünster, enhancing production capabilities for their ACD tubes and other blood collection products. The facility is expected to meet rising demand and improve logistics management.
- In January 2025, Sarstedt emphasized its commitment to research and innovation by sponsoring awards in biochemical analytics. This initiative aims to advance the quality and efficiency of products, such as ACD tubes, used in diagnostics.
Market Concentration & Characteristic
The ACD tubes market is moderately concentrated, with a few major players holding a significant share of the market. Global leaders such as Becton, Dickinson and Company (BD), Thermo Fisher Scientific, and Roche Diagnostics dominate the market, benefiting from their extensive product portfolios, strong distribution networks, and established reputations in the healthcare sector. These companies invest heavily in research and development to drive innovation, with a focus on improving product efficiency, safety, and automation. Smaller regional players, such as Greiner Bio-One and Sarstedt, account for a substantial portion of the market, offering specialized products that cater to specific local needs and price-sensitive markets. The market is characterized by high competition in terms of product quality, regulatory compliance, and technological advancements. As the demand for diagnostic testing and research grows, particularly in emerging markets, companies continue to seek strategic partnerships and expand their product offerings to maintain a competitive edge.
Report Coverage
The research report offers an in-depth analysis Based on Product Type, Based on Technology, Based on End-User, Based on Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The ACD tubes market is expected to see sustained growth driven by increasing demand for diagnostic testing, especially due to the rise in chronic diseases such as diabetes and cardiovascular disorders.
- The market will continue to benefit from advancements in blood collection technologies, particularly the adoption of automated and more efficient systems for blood sample collection and processing.
- Growing government investments in healthcare infrastructure, particularly in emerging markets like India, China, and Brazil, will contribute significantly to the market's expansion.
- The increasing focus on personalized medicine will fuel the demand for more frequent and precise diagnostic tests, further driving the need for reliable blood collection solutions like ACD tubes.
- Technological innovations aimed at improving tube materials and preservation methods will enhance the effectiveness of ACD tubes in long-term storage and transportation of blood samples.
- The integration of digital technologies in healthcare settings, such as the use of electronic health records and real-time data monitoring, will promote the use of standardized and high-quality blood collection solutions.
- The rise of clinical trials and medical research worldwide, supported by increased healthcare research funding, will drive demand for ACD tubes used in sample collection for these studies.
- The increasing prevalence of blood donation programs in both developed and developing countries will contribute to the steady demand for ACD tubes used in blood banks.
- North America and Europe will continue to lead the market due to their advanced healthcare systems and strong regulatory frameworks, but growth in Asia Pacific will accelerate.
- Increased collaboration between key players and research institutions will foster innovation and improve the efficiency of blood collection processes, further advancing the ACD tubes market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Acid Citrate Dextrose (ACD) Tubes Market?
What factors are driving the growth of the ACD tubes market?
Why are ACD tubes preferred in blood collection?
What role do technological advancements play in the ACD tubes market?
Which regions are leading the ACD tubes market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Acid Citrate Dextrose Tubes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Acid Citrate Dextrose Tubes Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 540.6 million → 2032: USD 798.71 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Acid Citrate Dextrose Tubes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Acid Citrate Dextrose Tubes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Acid Citrate Dextrose Tubes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Acid Citrate Dextrose Tubes Market Drivers
- 3.3 Acid Citrate Dextrose Tubes Market Restraints & Challenges
- 3.4 Acid Citrate Dextrose Tubes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Acid Citrate Dextrose Tubes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Acid Citrate Dextrose Tubes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Acid Citrate Dextrose Tubes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Acid Citrate Dextrose Tubes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Acid Citrate Dextrose Tubes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Acid Citrate Dextrose Tubes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Acid Citrate Dextrose Tubes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Acid Citrate Dextrose Tubes Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Acid Citrate Dextrose Tubes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Acid Citrate Dextrose Tubes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Acid Citrate Dextrose Tubes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Acid Citrate Dextrose Tubes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Acid Citrate Dextrose Tubes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Acid Citrate Dextrose Tubes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Acid Citrate Dextrose Tubes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Acid Citrate Dextrose Tubes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Acid Citrate Dextrose Tubes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Acid Citrate Dextrose Tubes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Acid Citrate Dextrose Tubes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
