
Market Overview:
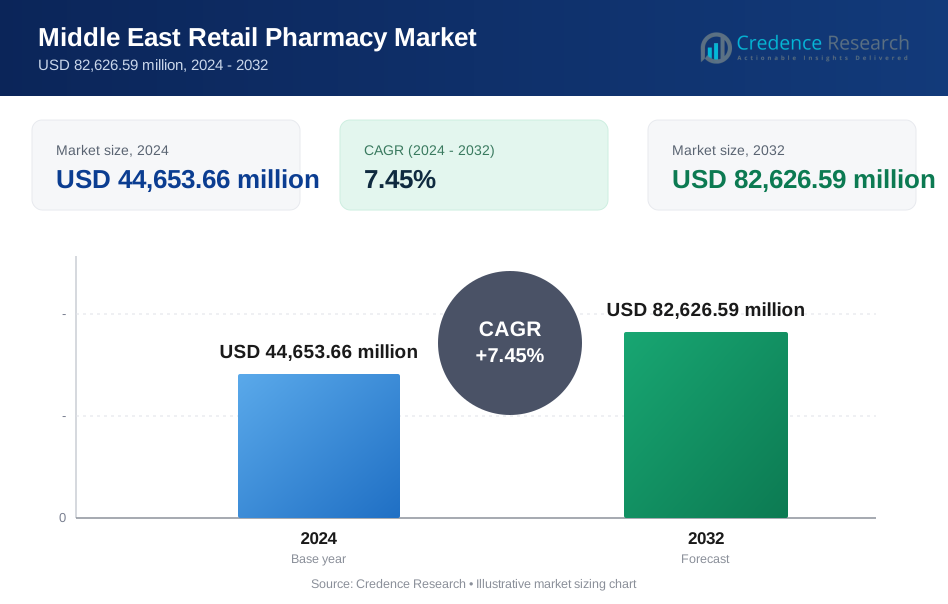
The Middle East Retail Pharmacy Market size was valued at USD 28,385.58 million in 2018 to USD 44,653.66 million in 2024 and is anticipated to reach USD 82,626.59 million by 2032, at a CAGR of 7.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Middle East Retail Pharmacy Market Size 2024 | USD 44,653.66 Million |
| Middle East Retail Pharmacy Market, CAGR | 7.45% |
| Middle East Retail Pharmacy Market Size 2032 | USD 82,626.59 Million |
Rising demand for prescription drugs, growing chronic disease prevalence, and increased health awareness are driving the market. Retail pharmacy chains are expanding rapidly due to urbanization and insurance penetration. Digitally enabled services, home delivery, and e-prescription systems enhance consumer access. Governments support private-sector participation and regulatory reforms. Retailers also broaden product ranges with OTC medicines and wellness offerings. Aging populations and lifestyle-related conditions continue to support stable volume growth. Improved medication adherence programs and pharmacy-based consultations further boost service value. The market benefits from a shift toward integrated healthcare models.
GCC countries lead the market due to advanced healthcare infrastructure and high per capita spending. Saudi Arabia dominates with strong policy support and retail chain expansion under Vision 2030. The UAE sees growth in digital pharmacy models and medical tourism demand. Qatar and Kuwait maintain steady performance driven by insurance-backed access. Jordan and Lebanon anchor growth in the Levant, supported by manufacturing and tourism. Iraq and Iran show emerging demand despite operational barriers. The market landscape reflects both developed and underserved zones, shaped by investment, regulation, and demographic shifts.

Market Insights
- The Middle East Retail Pharmacy Market was valued at USD 28,385.58 million in 2018, reached USD 44,653.66 million in 2024, and is projected to hit USD 82,626.59 million by 2032, growing at a CAGR of 7.45%.
- Saudi Arabia leads the market with over 35% share due to Vision 2030 reforms and retail chain expansion, followed by the UAE at around 17% supported by e-pharmacy growth and medical tourism, and Kuwait with 10% driven by high per capita healthcare spending.
- Iraq is the fastest-growing market with a 6% share, driven by urban population growth, essential drug demand, and investment in pharmacy infrastructure despite regulatory constraints.
- In 2024, prescription drugs accounted for the largest segment with a 44.8% share, followed by OTC medicines at 28.6%, reflecting high dependence on chronic care and self-medication trends.
- Nutraceuticals held a 16.5% share while medical devices made up 10.1%, supported by rising consumer health awareness and growing demand for home diagnostics and therapy aids.
Market Drivers
Rising Chronic Disease Burden and Aging Population Expands Long-Term Pharmaceutical Demand
The Middle East Retail Pharmacy Market is driven by a rising burden of chronic diseases like diabetes, hypertension, and cardiovascular conditions. An aging population increases long-term medication adherence needs and demand for specialty drugs. Retail pharmacies cater to recurring prescriptions, follow-up care, and disease monitoring. Governments promote preventive care and screening programs that drive footfall in pharmacy outlets. Patients seek convenience, resulting in higher traffic to nearby pharmacy stores. High rates of obesity and lifestyle-related illnesses further support steady pharmaceutical purchases. Long-term care patients rely on retail pharmacies for prescription continuity. National health strategies recognize the pharmacy’s role in non-hospital care access. Population health trends continue to fuel consistent prescription volume growth.
Healthcare Infrastructure Investments and Government Reforms Drive Retail Channel Expansion
Gulf countries are investing heavily in public and private healthcare infrastructure, driving pharmacy network expansion. The Middle East Retail Pharmacy Market benefits from reforms that liberalize licensing and encourage private sector entry. Governments streamline pharmacy approvals to increase service coverage in underserved regions. PPP models are expanding access in semi-urban and remote areas. Health insurance mandates promote regular prescription purchases through retail networks. Retail chains expand footprints in hospitals, malls, and standalone locations. National transformation plans prioritize healthcare access, boosting organized retail pharmacy formats. Government incentives attract regional and global investors into the sector. These factors improve pharmacy availability and service quality across income levels.
- For instance, Tabuk Pharmaceuticals in Saudi Arabia manufactured over 150 million doses of local generics in 2024 via its expanded Jeddah facility, as per SFDA production logs and their Vision 2030 update, shortening supply lead times by 30% for chain pharmacies.
Urbanization and Changing Consumer Lifestyles Support Organized Retail Pharmacy Growth
Fast urban growth across Saudi Arabia, the UAE, and Egypt increases demand for modern pharmacy formats. Consumers prefer organized outlets that offer trusted brands, clean environments, and digital payment support. The Middle East Retail Pharmacy Market responds with wider product portfolios and personalized service. Shopping habits shift toward health-focused retail destinations offering quick access to medications and wellness products. Lifestyle changes also increase demand for OTC supplements, personal care, and nutrition products. Working professionals favor outlets with fast checkout, e-prescription, and loyalty programs. Pharmacies inside malls and hypermarkets gain traction due to location convenience. Organized retail growth supports efficiency and customer trust. These shifts reinforce sustained demand across pharmacy formats.
- For example, BinDawood Holdings' 2024 Annual Report details 25 new urban mall stores, achieving 5 million loyalty app visits
Digital Healthcare Ecosystem and Telemedicine Growth Enhance Pharmacy Integration
Governments across the region are building digital health ecosystems integrating e-prescription and health records. This shift strengthens the Middle East Retail Pharmacy Market by enabling faster and safer dispensing. Telemedicine platforms collaborate with retail pharmacies for seamless prescription fulfillment. Digital apps link patients to pharmacies for consultation, delivery, and medicine tracking. Pharmacies adopt automation, e-payment, and remote dispensing systems to improve efficiency. Consumers demand digital interfaces for convenience, driving IT investments across large chains. Regional healthcare digitization encourages pharmacies to become tech-enabled hubs. E-commerce platforms also partner with pharmacies for real-time delivery services. Digital integration enhances access, speed, and accuracy in prescription services.
Market Trends
Growth of E-Pharmacy and App-Based Delivery Channels Across Urban and Semi-Urban Areas
E-pharmacy platforms continue to reshape the retail delivery model across the region. The Middle East Retail Pharmacy Market sees growing partnerships between local chains and tech startups for app-based delivery. Consumers favor doorstep delivery for repeat prescriptions and chronic disease medications. Real-time order tracking, digital invoices, and online consultations build platform loyalty. Chain pharmacies develop proprietary apps with integrated loyalty programs and digital wallets. COVID-19 accelerated consumer trust in digital healthcare, which continues post-pandemic. Urban households rely on e-pharmacy for elderly care and follow-up medications. Regulations are adapting to ensure safety and data protection in digital medicine sales. E-pharmacy is gaining traction as a preferred channel.
- For instance, Nahdi Medical in Saudi Arabia launched its app in 2020, achieving over 2.5 million downloads by end-2023 as per their official Tadawul filings, with delivery orders surpassing 5 million through 2024 partnerships like Jahez.
Rise of Health and Wellness Retailing Within Modern Pharmacy Chains
Retail pharmacies are expanding into wellness segments, offering health monitoring, supplements, and cosmetic products. The Middle East Retail Pharmacy Market integrates wellness zones into store formats to drive premium spending. Demand for skin care, nutrition, and lifestyle products is rising among youth and women. In-store diagnostic kiosks and wellness screenings increase footfall and cross-selling. Pharmacies are becoming holistic health destinations rather than just medicine outlets. Product curation focuses on immunity, weight management, and personal hygiene. Partnerships with global wellness brands support premiumization and brand differentiation. Store layouts are optimized for browsing and consultative sales. Wellness product margins boost revenue per store.
- For instance, Al-Dawaa Pharmacy in Saudi Arabia rolled out wellness screening stations in over 100 stores by 2024, performing more than 200,000 screenings annually per their 2024 annual report, driving a 25% increase in non-pharma sales.
Pharmacy Chain Consolidation and Entry of Global Investors Reshape Competition Landscape
Market consolidation continues as regional leaders acquire smaller outlets to expand geographic reach. The Middle East Retail Pharmacy Market attracts FDI and regional conglomerates seeking scale and vertical integration. Chain pharmacies gain advantages in procurement, branding, and technology adoption. Franchise models expand footprints across Saudi Arabia, Egypt, and UAE. Consolidation reduces fragmentation and enhances operational efficiency. Investors target multi-outlet brands with scalable tech and supply chains. Competitive pressures push small players to join larger platforms or niche down. Pharmacy brands also align with insurance providers and hospitals for recurring patient traffic. Consolidation builds stronger, standardized service networks.
Localization of Manufacturing and Supply Chain Digitization Strengthen Pharmacy Efficiency
Local pharmaceutical manufacturing is increasing across the Gulf, reducing import dependency. The Middle East Retail Pharmacy Market gains from faster inventory availability and lower logistics risk. Governments support local drug production through industrial zones and incentives. Pharmacies benefit from improved supply timelines and competitive pricing. Supply chain digitization enables real-time inventory monitoring across outlets. Integrated systems improve procurement planning and stock management. Local sourcing aligns with regional drug pricing and regulation goals. Temperature-sensitive drugs are better managed with tech-enabled logistics. These improvements raise service levels and reduce stockouts.

Market Challenges Analysis
Fragmented Regulatory Landscape and Pricing Controls Affect Margin Stability Across Regions
The Middle East Retail Pharmacy Market faces margin pressure due to strict pricing controls on essential drugs. Each country operates with its own regulatory framework, slowing cross-border standardization. Centralized price caps restrict pharmacy profitability in branded generics and chronic care. Delayed drug approvals or limited import quotas create supply disruptions. Smaller players struggle to remain competitive against large chains with better procurement terms. Non-uniform licensing rules affect expansion timelines across GCC and Levant markets. Government push for localization also disrupts foreign drug brand availability in select regions. These issues challenge operational consistency and growth scalability. Retailers must adapt pricing strategies while ensuring service quality.
Workforce Shortages, High Rent, and Infrastructure Constraints Impact Smaller Retail Operators
Retail pharmacies in lower-tier cities face challenges in staffing trained pharmacists and managing rental overheads. The Middle East Retail Pharmacy Market sees skill gaps in rural and remote locations where pharmacy access remains limited. Chain outlets in urban malls face rent spikes and utility costs that strain profitability. Infrastructure limitations affect the rollout of cold chain logistics and automation. Staff attrition is high in high-footfall locations due to long shifts and limited upskilling. Smaller operators lack capital for digital upgrades or in-store diagnostics. These constraints limit customer experience enhancements and scalability. Market entry remains capital-intensive and operationally complex for new players.

Market Opportunities
Expansion into Preventive Health Services and In-Store Diagnostics Offers Growth Headroom
Retail pharmacies can expand service offerings through preventive health checkups, point-of-care diagnostics, and vaccination drives. The Middle East Retail Pharmacy Market shows rising demand for accessible wellness screening. Pharmacies can partner with diagnostics labs to offer bundled packages for chronic conditions. These services increase ticket size and customer retention. Staff training and digital booking platforms enable seamless service integration. Regulatory support for non-hospital screening creates an enabling environment. Expansion into preventive health opens new growth pathways for urban and semi-urban pharmacies.
Growth of Medical Tourism and Expat Healthcare Spending Creates Cross-Border Retail Demand
Medical tourism in the UAE, Turkey, and Jordan supports growth in premium pharmacy sales. The Middle East Retail Pharmacy Market benefits from demand for specialty medication and wellness products from foreign patients. Pharmacies near hospitals and clinics see strong tourist-driven revenue. Expats with insurance coverage favor branded products and value-added services. Multilingual staff, global inventory, and loyalty programs enhance patient experience. Retailers can target this segment through tailored promotions and partnerships. This emerging niche supports value growth and service differentiation.
Market Segmentation Analysis
By Product Type
The Middle East Retail Pharmacy Market sees strong demand for prescription drugs due to chronic disease prevalence and long-term care needs. OTC medicines continue to gain traction among self-medication users. Nutraceuticals are expanding as wellness awareness rises. Medical devices, such as glucose monitors and nebulizers, support at-home treatment. Retailers diversify offerings to include both essential therapies and preventive care solutions.
- For instance, Boots Pharmacy in the UAE expanded its OTC range in 2024, achieving over 1.2 million units sold quarterly across 150 stores per their regional sales disclosures.
By Distribution Channel
Retail chains dominate the market due to scale, branding, and tech integration. Independent pharmacies remain vital in rural and semi-urban areas. Online pharmacies are growing through app-based ordering and last-mile delivery. Hospital pharmacies play a key role in post-discharge medication continuity. The Middle East Retail Pharmacy Market is gradually shifting toward omni-channel models to improve access.
By Consumer Type
Urban consumers drive most retail sales due to higher healthcare access, insurance coverage, and lifestyle needs. Rural consumers contribute steady volumes through essential and chronic care purchases. The Middle East Retail Pharmacy Market adapts channel strategies and store footprints to meet both urban and rural needs.
- For instance, SPIMACO reported an annual production capacity exceeding 2.5 billion units in 2024 across its regional facilities, including its flagship Qassim plant in Saudi Arabia. The company launched Endosa, the GCC’s first fully integrated biosimilar, strengthening its role in supplying generics to retail and government pharmacy channels.
By Therapeutic Area
Cardiovascular and diabetes therapies lead prescription volumes. Oncology and respiratory drugs show faster growth driven by rising diagnosis rates. The Middle East Retail Pharmacy Market also sees increasing sales under the “Others” segment, including dermatology and neurology therapies.
By Company Type
International players offer global brands and advanced service models. Domestic players leverage local networks and regulatory familiarity. The Middle East Retail Pharmacy Market balances both, with joint ventures and franchise models driving competitive presence.
By Adherence Risk Profile
Chronic disease and elderly patients require high-frequency dispensing and support services. Acute therapy users need fast access and advice. OTC users favor convenience and availability. The Middle East Retail Pharmacy Market tailors service models by patient risk profile.
By Medication Journey Stage
Retail pharmacies are active in diagnosis support, dispensing, adherence management, follow-up, and refills. The Middle East Retail Pharmacy Market plays a key role across every stage, reinforcing its importance in long-term patient care.
Segmentation
By Product Type
- Prescription Drugs
- Over-the-Counter (OTC) Medicines
- Nutraceuticals
- Medical Devices
By Distribution Channel
- Retail Chains
- Independent Pharmacies
- Online Pharmacies
- Hospital Pharmacies
By Consumer Type
- Urban Consumers
- Rural Consumers
By Therapeutic Area
- Cardiovascular
- Diabetes
- Oncology
- Respiratory
- Others
By Company Type
- Domestic Players
- International Players
By Adherence Risk Profile
- Chronic Disease Patients
- Elderly / Polypharmacy Patients
- Acute Therapy Patients
- Self-medication / OTC Users
By Medication Journey Stage
- Prescription & Diagnosis
- Dispensing at Retail Pharmacy
- Post-Dispensing Usage (Adherence Phase)
- Monitoring & Follow-up
- Refill & Therapy Continuation

Regional Analysis
The Gulf Cooperation Council (GCC) holds the largest share of the Middle East Retail Pharmacy Market, accounting for nearly 62% of total revenue. Saudi Arabia leads due to its large population, high prevalence of chronic diseases, and investments under Vision 2030. The UAE follows with strong demand from urban centers, growing medical tourism, and regulatory support for retail pharmacy chains. Kuwait and Qatar also contribute meaningfully, driven by high per capita healthcare spending and strong private sector participation. Organized pharmacy formats dominate in the GCC, supported by digital infrastructure and consumer preference for branded services.
The Levant region represents around 21% of the Middle East Retail Pharmacy Market, with key contributions from Jordan and Lebanon. Jordan benefits from a strong pharmaceutical manufacturing base and medical tourism. Lebanon, despite economic headwinds, maintains steady prescription sales supported by private healthcare providers. Independent pharmacies are more prevalent in this region compared to GCC countries. Supply chain challenges and currency fluctuations impact pharmacy operations, but ongoing donor and private investments help sustain access in urban zones. Growth remains moderate but steady due to demand for essential and chronic care drugs.
The Rest of the Middle East, including Iraq, Iran, Syria, and Yemen, holds approximately 17% of the market share. The Middle East Retail Pharmacy Market in these countries is shaped by humanitarian needs, fragmented healthcare access, and reconstruction efforts. Urban centers in Iraq and Iran support growing demand for generics and OTC medicines. Supply chain limitations and uneven regulatory frameworks restrict retail expansion. International NGOs and aid-driven health programs play a key role in pharmacy accessibility. Long-term potential remains tied to political stability and infrastructure recovery.\
Key Player Analysis
- Pure Health
- Malaffi
- Seha
- Vezeeta
- Altibbi
Competitive Analysis
The Middle East Retail Pharmacy Market is highly competitive, led by a mix of regional chains, domestic operators, and international brands. Large players like Al Nahdi Medical, Aster Pharmacy, and Boots command significant retail share in urban areas. These companies invest in digital platforms, supply chain automation, and loyalty programs to retain customers. Franchising and strategic acquisitions support geographic expansion across GCC markets. Domestic players, including Tadawi, Al-Dawaa, and Al Mutawa Pharmacies, leverage local knowledge and regulatory agility to compete with global brands. New entrants focus on e-pharmacy models, targeting tech-savvy consumers and chronic care patients. Competitive pricing, bundled services, and subscription models are becoming key differentiators. The Middle East Retail Pharmacy Market also sees growing competition in wellness, nutrition, and diagnostics offerings. Companies are integrating with telemedicine platforms and insurance networks to gain recurring revenue. Mergers and partnerships with healthcare providers, logistics firms, and startups are shaping a new competitive dynamic.
Recent Developments
- In January 2026, Kuwait-based Royal Pharmacy completed a digital transformation by launching a new eCommerce website and mobile apps to improve customer experience and operational efficiency across its retail pharmacy network.
- In March 2026, United Pharmaceutical Company announced a formal agreement with Global Healthcare Company to acquire Kunooz Pharmacies, reinforcing its expansion in Saudi Arabia and strengthening access to pharmacy services in Riyadh and other areas.
- In March 2026, Idorsia entered an exclusive agreement with Pharmalink Drug Store L.L.C to distribute and commercialize QUVIVIQ™ - daridorexant for adult insomnia across the UAE, Kuwait, Qatar, Oman, and Bahrain; Pharmalink’s Medicina and Al Manara pharmacy chains provide retail penetration for the product.
- In April 2026, Farmak International reported 23 product launches in Q1 2026 across Europe, the Middle East and Africa, and Southeast Asia, covering therapeutic areas such as ophthalmology and diagnostic imaging.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel, Consumer Type, Therapeutic Area, Company Type, Adherence Risk Profile and Medication Journey Stage. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Organized pharmacy chains will expand footprints through franchising, tech investments, and cross-border partnerships.
- E-pharmacy growth will accelerate, driven by mobile-first users and chronic care patients demanding convenience.
- Wellness and preventive care retailing will gain importance, especially in urban, high-income clusters.
- AI and analytics will guide inventory, customer profiling, and adherence monitoring across leading chains.
- Integration with telehealth and insurance platforms will create closed-loop medication service models.
- Local pharmaceutical manufacturing will strengthen, reducing dependency on imports and supply delays.
- Governments will increase regulatory oversight for quality control, data security, and prescription tracking.
- Specialty drugs and biosimilars will enter retail channels, requiring pharmacist upskilling and cold-chain support.
- Urban-rural channel strategies will evolve, with tailored offerings for low-access areas via mobile units and digital orders.
- Cross-border players will target the Middle East Retail Pharmacy Market through strategic joint ventures and digital-first models.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Chronic Disease Burden and Aging Population
The increasing prevalence of chronic diseases such as diabetes, hypertension, and cardiovascular conditions, along with an aging population, is driving sustained demand for prescription medications and long-term pharmaceutical care through retail pharmacies.
Healthcare Infrastructure Investments and Regulatory Reforms
Significant investments in healthcare infrastructure and government reforms across the GCC are expanding pharmacy networks, liberalizing licensing, and encouraging private sector participation, which increases access and coverage of retail pharmacy services.
Urbanization and Changing Consumer Lifestyles
Rapid urbanization in major Middle Eastern cities is fueling demand for organized pharmacy chains that offer a wide range of products, digital payment options, and wellness services, catering to evolving consumer preferences for convenience and quality.
Digital Health Ecosystem and E-Pharmacy Growth
The integration of digital health platforms, e-prescription systems, and app-based pharmacy delivery is enhancing consumer access, improving medication adherence, and driving the adoption of omni-channel retail pharmacy models.
Localization of Pharmaceutical Manufacturing
Government support for local drug production and supply chain digitization is reducing import dependency, improving inventory availability, and enabling pharmacies to offer competitive pricing and faster service, especially for essential and chronic care medications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Middle East Retail Pharmacy Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Middle East Retail Pharmacy Market projected to grow between 2024 and 2032?
Which Middle East Retail Pharmacy Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Middle East Retail Pharmacy Market?
Who are the leading companies in the Middle East Retail Pharmacy Market?
Which region commanded the largest share of the Middle East Retail Pharmacy Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Prescription Drugs
- 1.2.2 Over-the-Counter (OTC) Medicines
- 1.2.3 Nutraceuticals
- 1.2.4 Medical Devices
- 1.3 By Consumer Type
- 1.3.1 Urban Consumers
- 1.3.2 Rural Consumers
- 1.4 By Therapeutic Area
- 1.4.1 Cardiovascular
- 1.4.2 Diabetes
- 1.4.3 Oncology
- 1.4.4 Respiratory
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 44,653.66 million → 2032: USD 82,626.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Middle East Retail Pharmacy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Middle East Retail Pharmacy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Middle East Retail Pharmacy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Middle East Retail Pharmacy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Middle East Retail Pharmacy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Middle East Retail Pharmacy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Middle East Retail Pharmacy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Middle East Retail Pharmacy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 44,653.66 million → 2032: USD 82,626.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Middle East Retail Pharmacy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Prescription Drugs
- 12.3.7.2 Over-the-Counter (OTC) Medicines
- 12.3.7.3 Nutraceuticals
- 12.3.7.4 Medical Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Consumer Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Urban Consumers
- 12.4.7.2 Rural Consumers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Therapeutic Area - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cardiovascular
- 12.5.7.2 Diabetes
- 12.5.7.3 Oncology
- 12.5.7.4 Respiratory
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Middle East Retail Pharmacy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Middle East Retail Pharmacy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Middle East Retail Pharmacy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Al Nahdi Medical Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Aster Pharmacy
- 17.4 Boots Pharmacy
- 17.5 Al-Dawaa Pharmacies
- 17.6 BinDawood Holdings
- 17.7 SPIMACO
- 17.8 Pure Health
- 17.9 Farmak International
- 17.10 United Pharmaceutical Company
- 17.11 Vezeeta
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

