
Software, data exchange and AI reshape clinical work
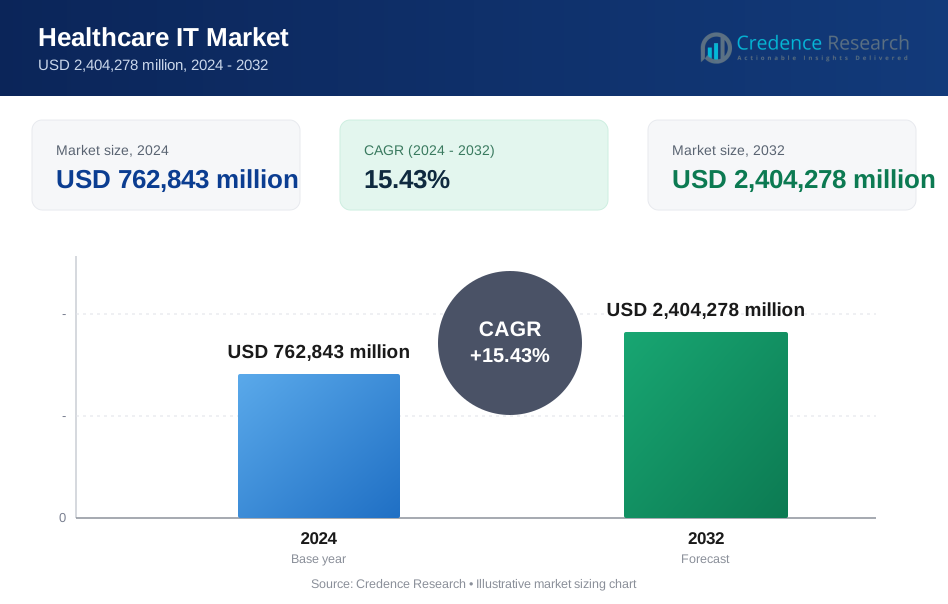
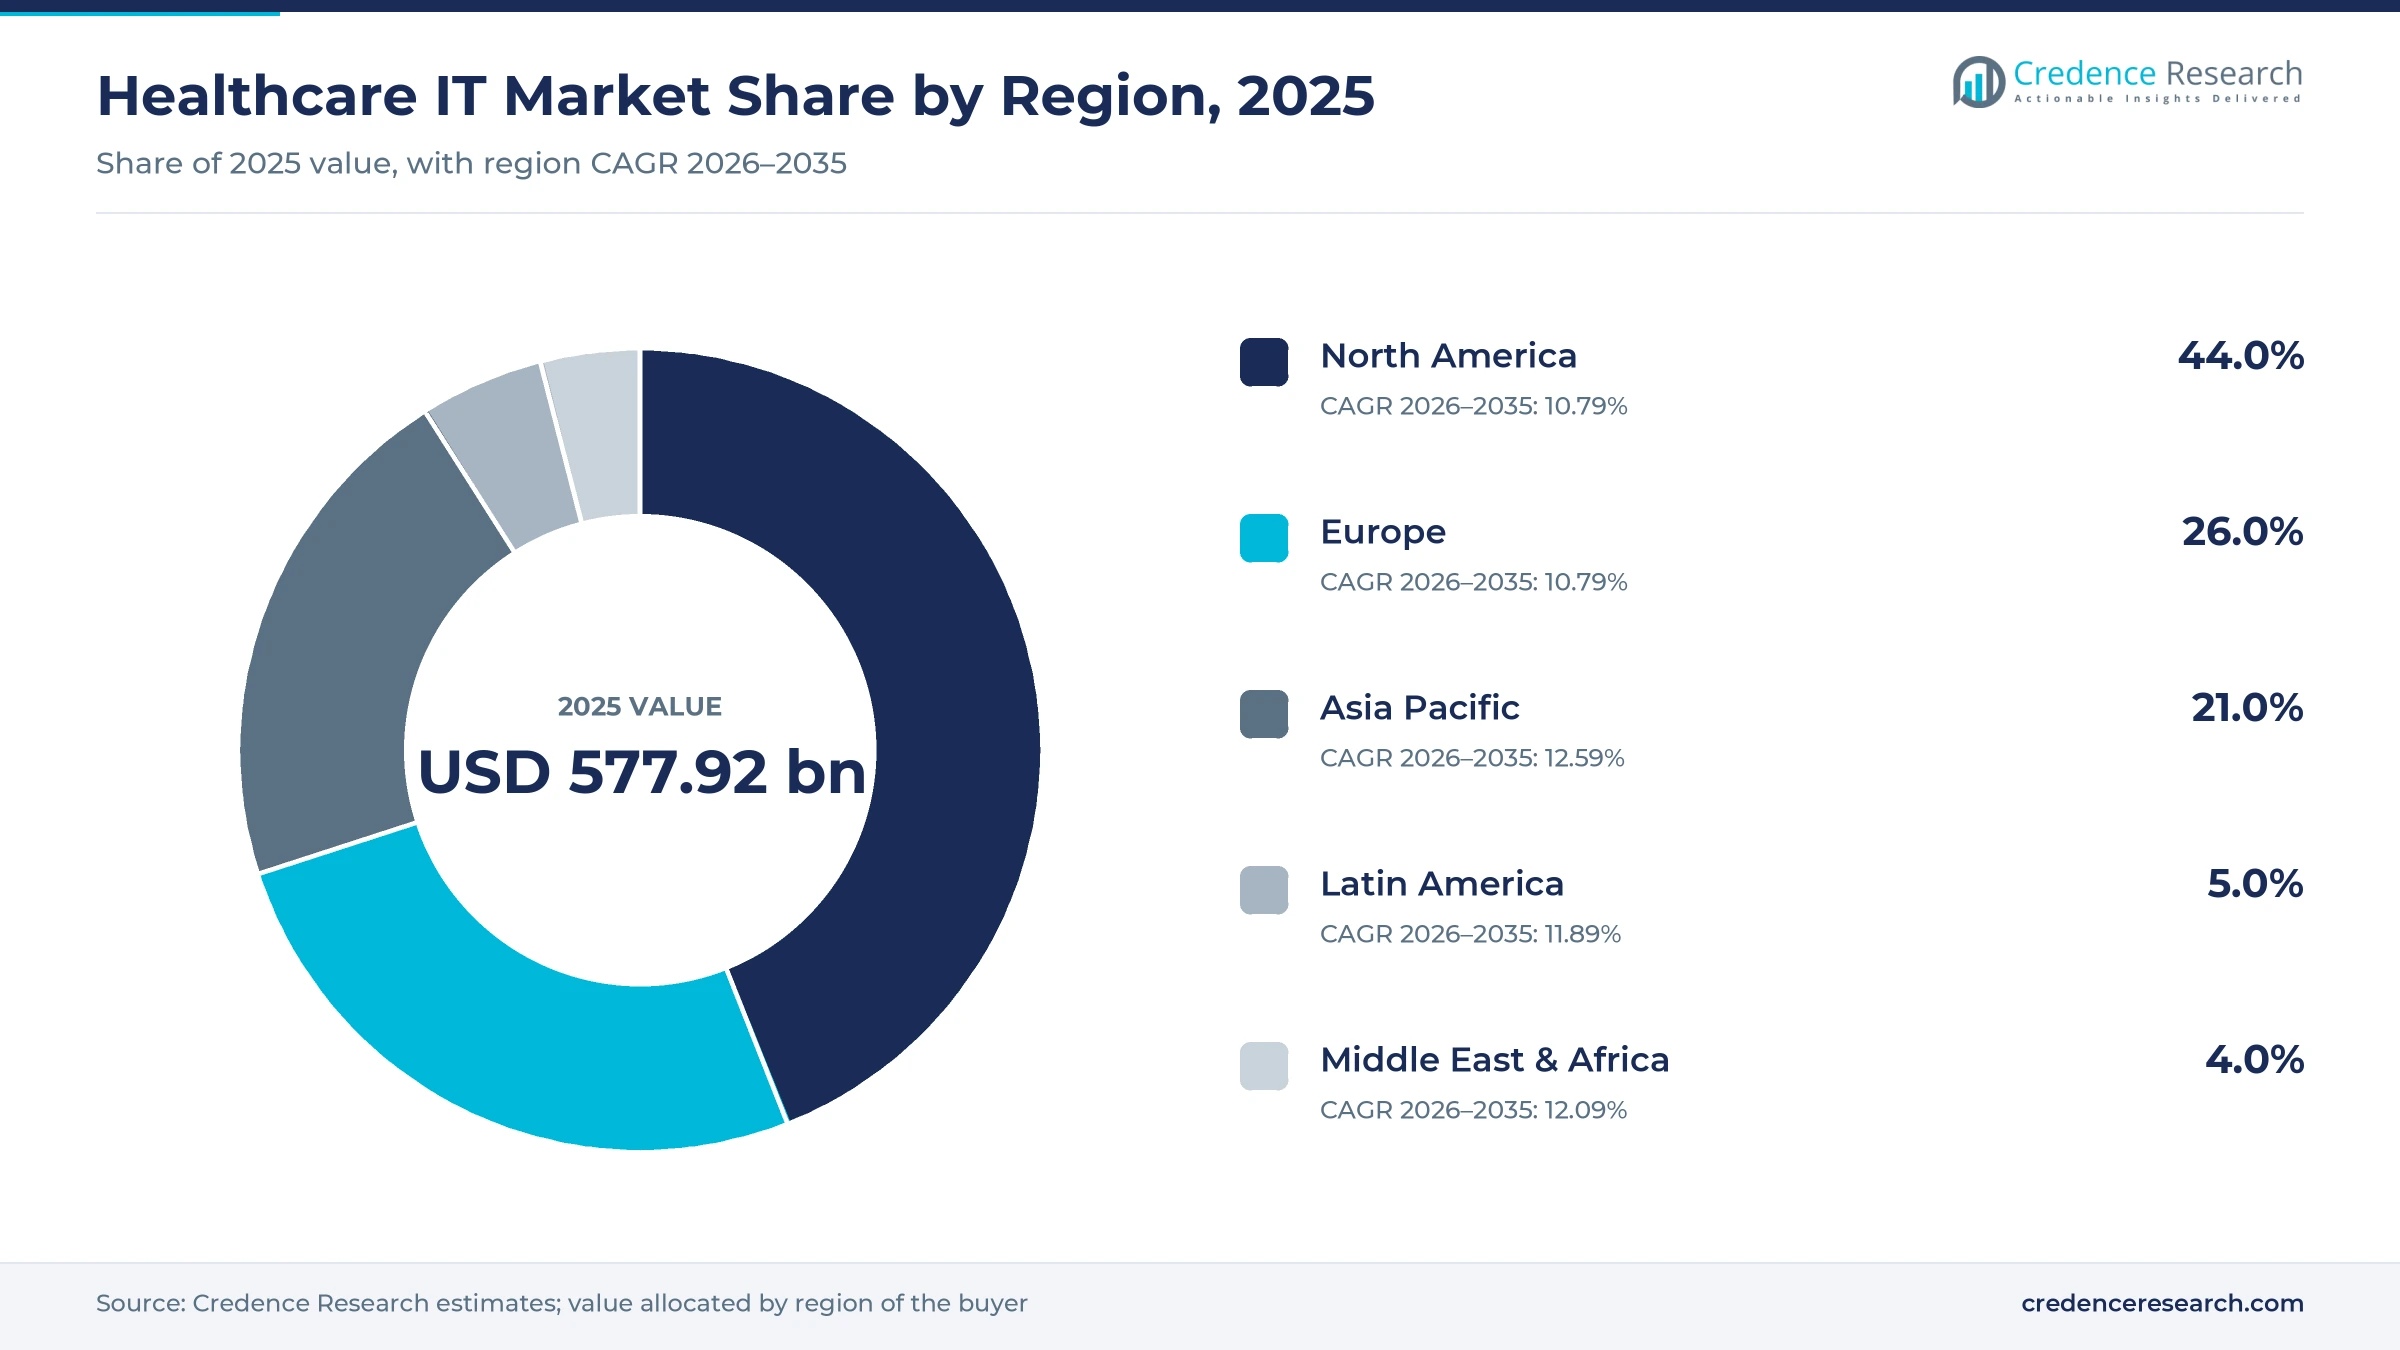
The global healthcare IT market was valued at USD 577.92 billion in 2025 and is projected to increase from USD 643.24 billion in 2026 to USD 1,686.22 billion by 2035, registering a CAGR of 11.30% during 2026–2035. Demand comes from hospitals, physician groups, insurers and drug developers that need software, devices and services to record care, exchange data, bill claims and run analytics. North America held the largest regional share, 44.0% in 2025, on mature electronic record use, federal data exchange rules and high spending per patient. Asia Pacific is the fastest-growing region at 12.59% a year, as national digital health programs in China, India and Southeast Asia connect public hospitals. The main change is a shift from basic record keeping toward artificial intelligence assistants and mandatory application programming interfaces that let patients, providers and payers share data in near real time.
Which digital health products count toward total value?
The market counts spending on hardware, software and services that health care organizations use to capture, store, exchange and analyze clinical, financial and operational data. It covers electronic records, order entry, e-prescribing, laboratory and imaging information systems, virtual care platforms, analytics and population health tools, and clinical trial software used by drug developers.
The scope excludes medical devices whose main role is diagnosis or therapy, such as scanners and infusion pumps, and general office software not built for health care. Value runs from platform vendors through integrators and managed service firms to hospitals, physician practices, insurers and life sciences companies that buy licenses, subscriptions and support contracts.
Healthcare IT Market Insights
- The healthcare IT market grows from USD 577.92 billion in 2025 to USD 1,686.22 billion by 2035, an 11.30% CAGR over 2026–2035, as data exchange rules and AI tools widen software use.
- North America held 44.0% of global healthcare IT value in 2025, backed by near-universal electronic record use in hospitals and federal data exchange mandates.
- Software led components with 47.0% of 2025 value, because records, analytics and revenue tools are sold as recurring licenses and subscriptions.
- CMS finalized its interoperability and prior authorization rule in January 2024, requiring payers to build new data exchange APIs by January 2027.
- GE HealthCare completed its USD 2.3 billion Intelerad purchase in March 2026, showing strong deal interest in cloud imaging software.
Software and electronic records hold the largest value
Why does software hold the largest component share?
Based on component, the market is categorized into hardware, software and services. Software led with 47.0% of 2025 value and also grows fastest at 11.67% a year, because electronic records, analytics and revenue cycle tools move to recurring cloud subscriptions. Services follow as hospitals pay for implementation, data migration and managed hosting. Hardware such as servers and workstations grows more slowly as computing shifts to cloud data centers.
How do records, imaging and analytics divide value?
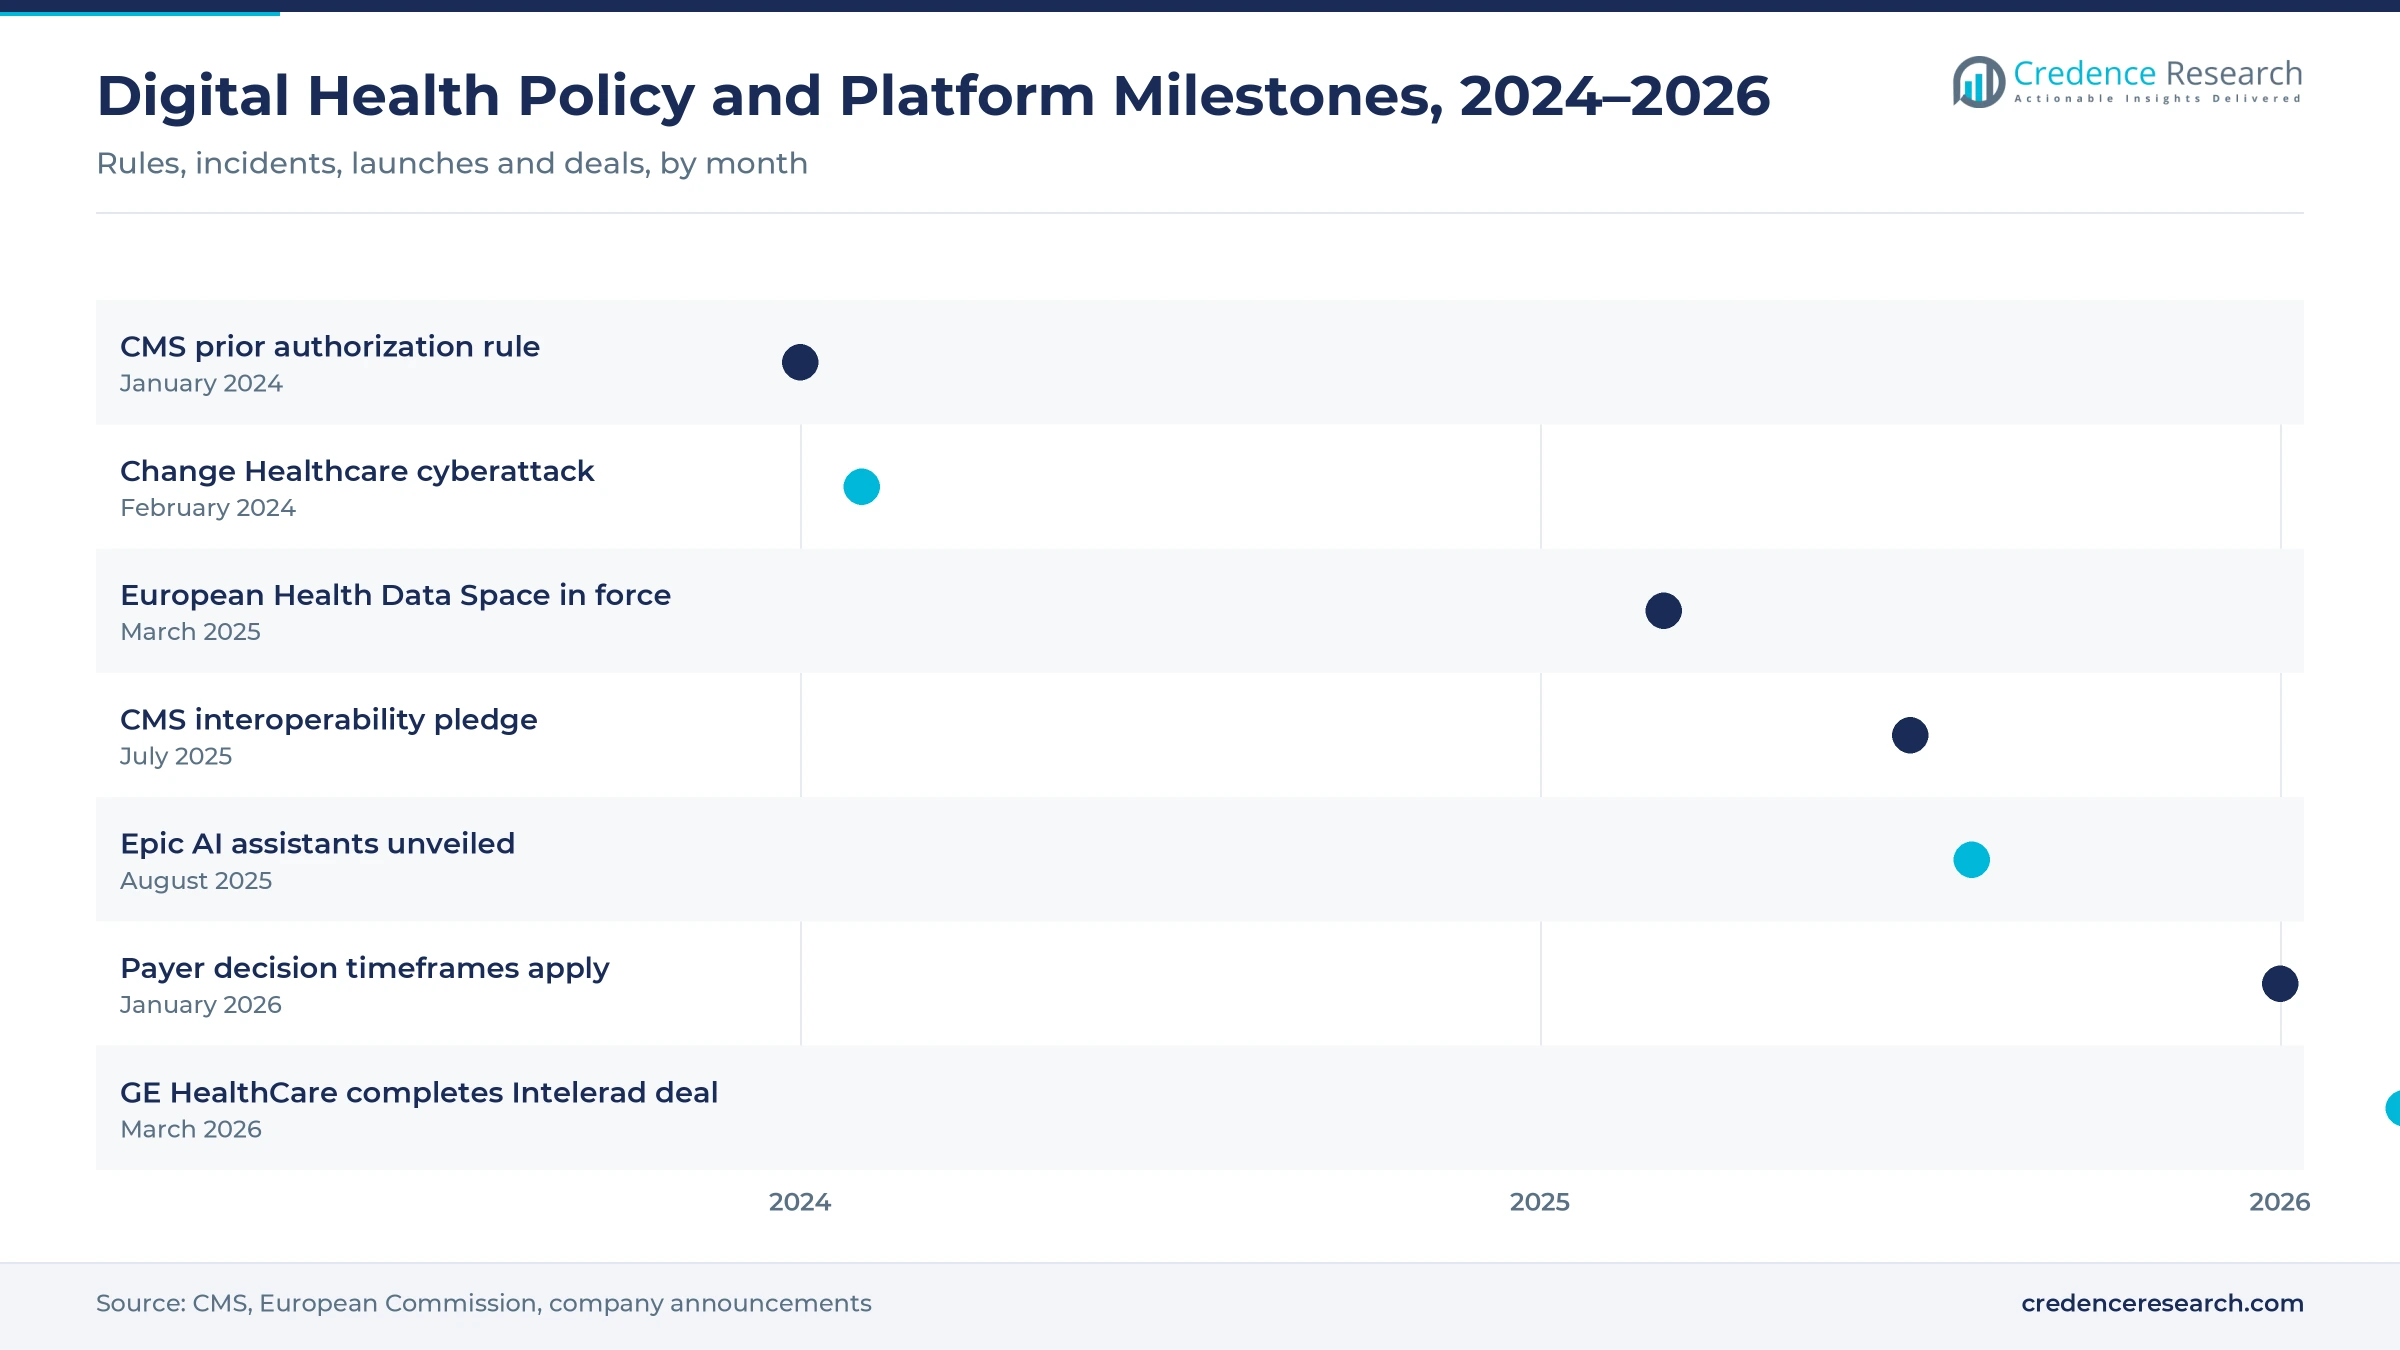
Based on application, the market is categorized into order entry, e-prescribing, laboratory, clinical, imaging, electronic records, tele-healthcare, eClinical, population health, analytics and other systems. Electronic Health Records led with 24.0% of 2025 value, because every hospital and practice runs a core record platform. Healthcare Analytics grows fastest at 12.86% a year, as providers and payers use predictive models and AI to manage cost, risk and quality.
Which buyers account for most spending?
Based on end use, the market is categorized into healthcare providers, healthcare payers and the life sciences industry. Healthcare Providers led with 62.0% of 2025 value, because hospitals and physician groups buy records, imaging and clinical systems at large scale. The Life Sciences Industry grows fastest at 11.89% a year, as drug developers adopt decentralized trial software and real-world data platforms.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Component | Software | 47.0% | Software | 11.67% |
| By Application | Electronic Health Records | 24.0% | Healthcare Analytics | 12.86% |
| By End Use | Healthcare Providers | 62.0% | Life Sciences Industry | 11.89% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Interoperability rules and AI assistants lift spending
How do payer data exchange rules drive new spending?
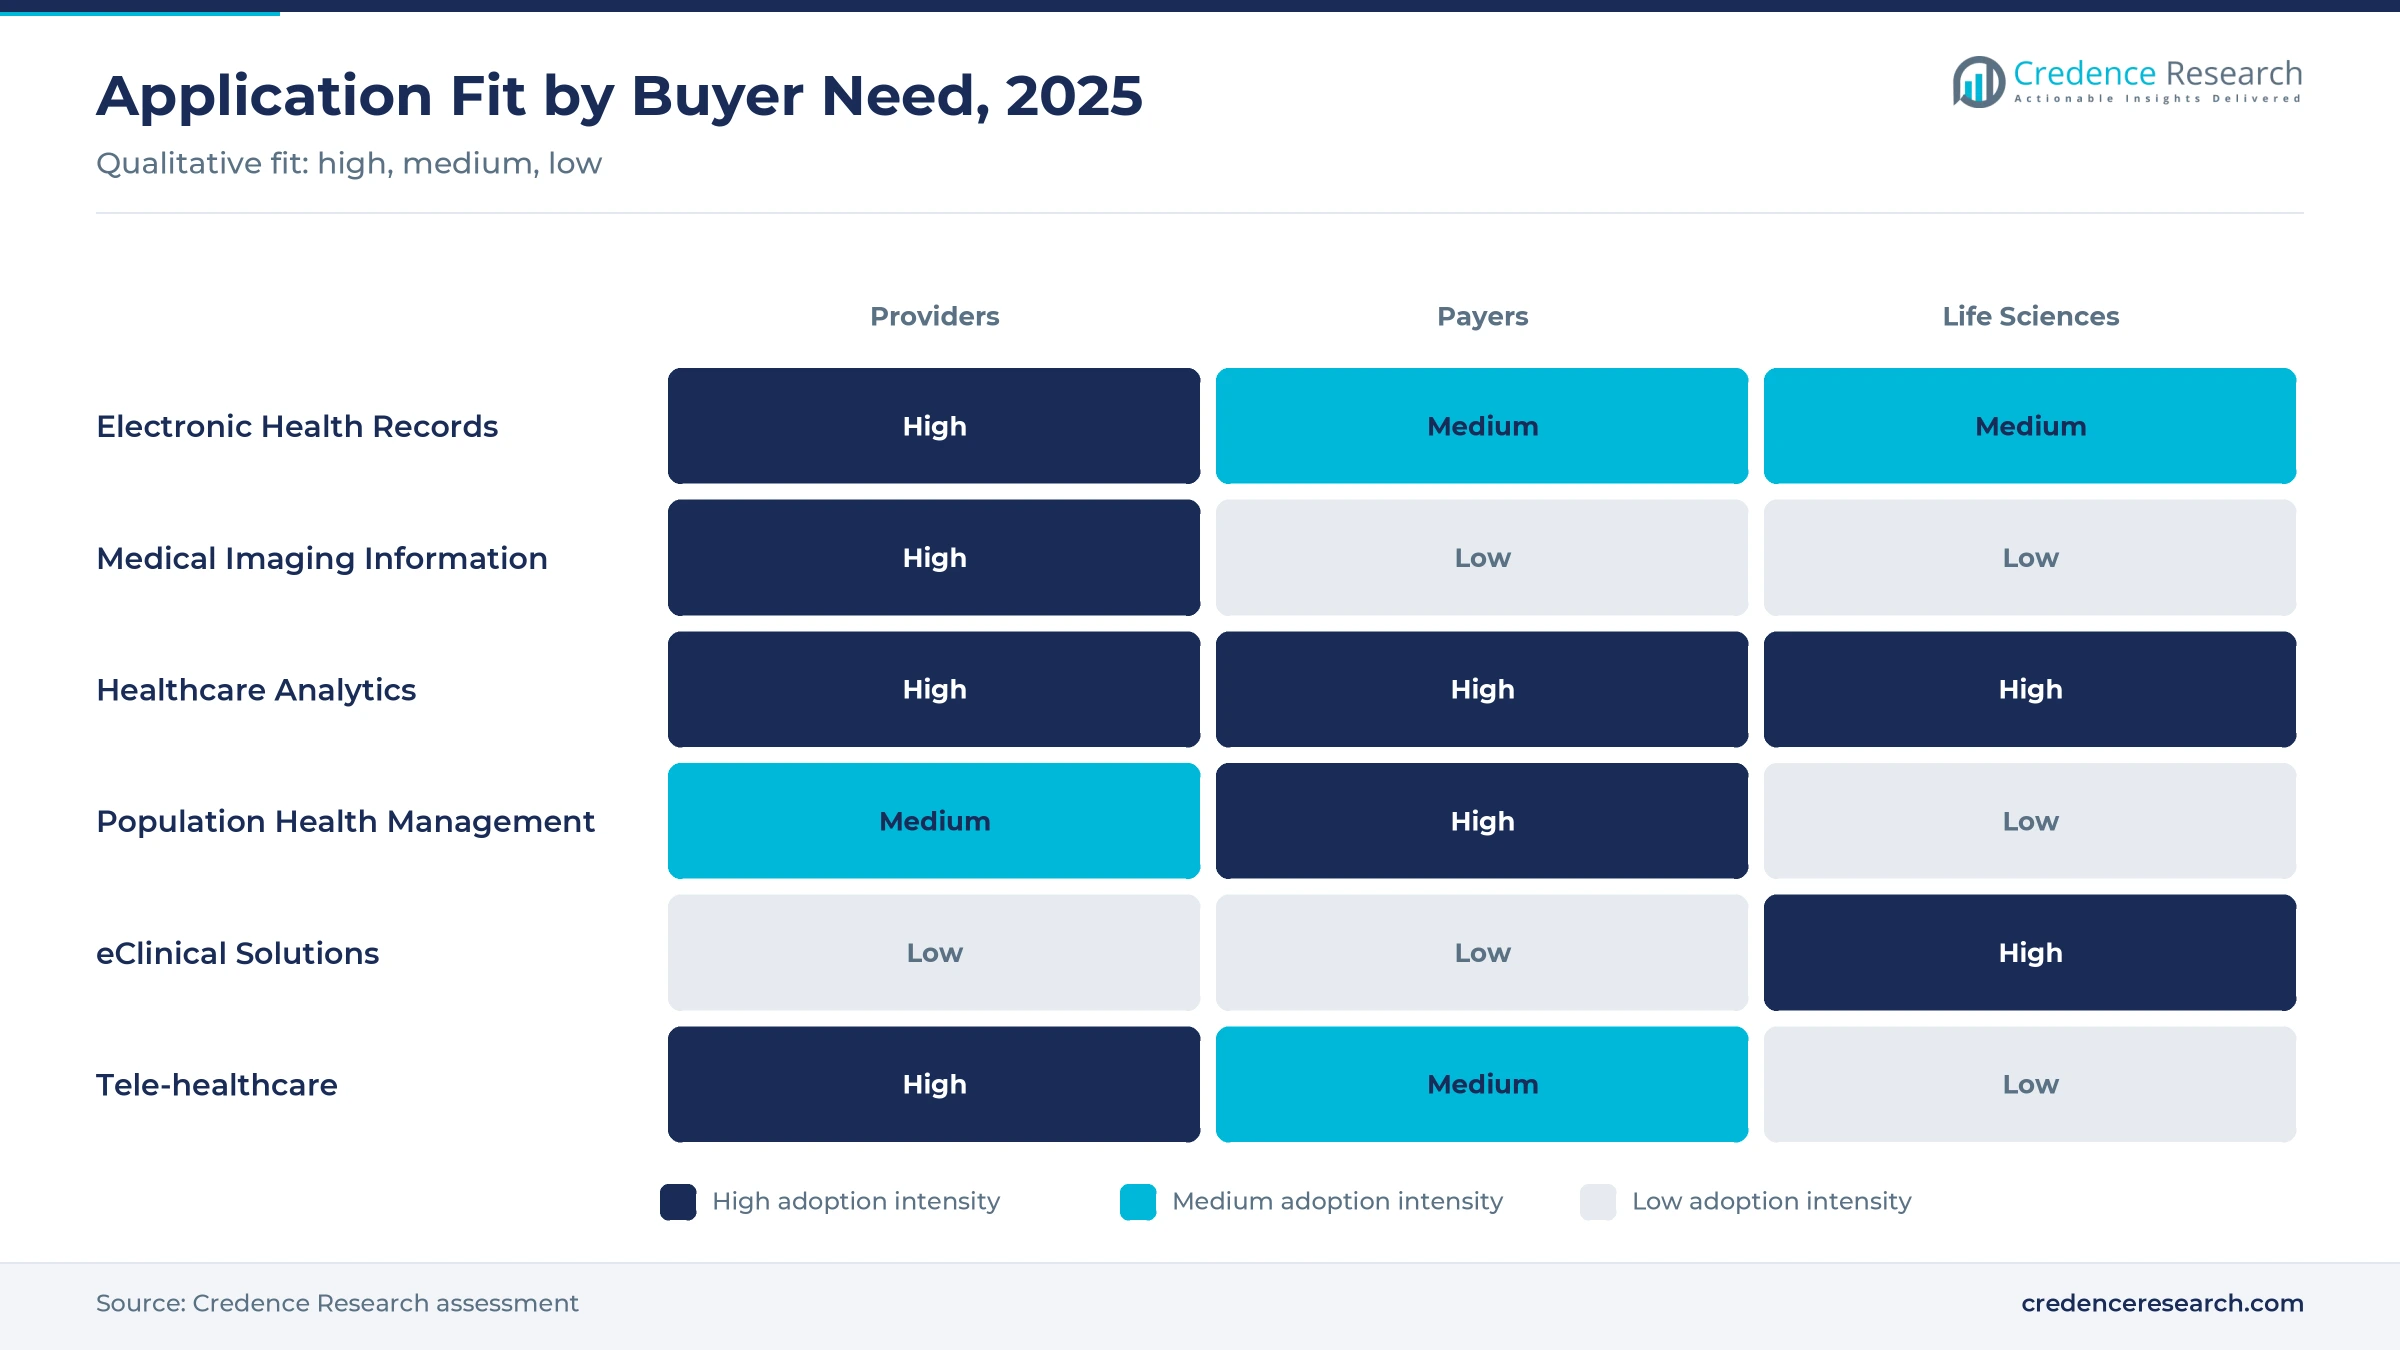
Federal rules in the U.S. now require insurers to build modern data exchange links with patients and providers. On Jan. 17, 2024, CMS released its interoperability and prior authorization final rule, which sets 72-hour decisions for urgent requests and 7-day decisions for standard ones from Jan. 1, 2026. Impacted payers must also build patient, provider, payer-to-payer and prior authorization APIs by January 2027. As a result, Medicare Advantage plans, Medicaid programs and their vendors invest in new software through the decade.
Why does the European data space widen record upgrades?
European rules are pushing hospitals and software makers toward common record formats and cross-border data sharing. The European Health Data Space regulation entered into force on March 26, 2025, and key functions such as cross-border patient summaries and ePrescriptions are expected across the EU by March 2029. This timeline forces record vendors to certify their products and gives hospitals a reason to replace older systems. In turn, European spending on records and data exchange rises steadily to 2030.
How do AI assistants raise the value of record platforms?
Generative AI is turning record platforms into tools that draft notes, answer patient questions and prepare claims. In August 2025, Epic introduced AI assistants named Art, Emmie and Penny for clinicians, patients and billing staff at its annual users meeting. These tools build on the clinical decision support tools that hospitals already use for alerts and order guidance. Because AI features are sold as add-ons, they lift spending per hospital without new installations.
Why do virtual care and remote monitoring keep growing?
Health systems now run virtual visits, remote monitoring and digital check-in as routine parts of care rather than emergency workarounds. Patients with chronic conditions such as diabetes and heart failure use connected devices that send readings to care teams between visits. Platforms for telehealth visits now link directly into record systems, which reduces duplicate entry for clinicians. This integration keeps tele-healthcare among the faster-growing applications through 2035. In July 2025, CMS also reported that 30 companies pledged to promote health outcomes with apps for diabetes and obesity management, symptom checks and scheduling.
Cloud imaging, agentic AI and patient data access rise
Why is cloud imaging software gaining ground?
Imaging departments are shifting from local servers to cloud archives that let radiologists read studies from any site. In March 2026, GE HealthCare completed its acquisition of Intelerad for a base price of USD 2.3 billion in cash, adding cloud-enabled enterprise imaging software. The deal extends its reach into specialized clinics and ambulatory care sites. This shift points to more subscription revenue in imaging information systems as hospitals retire older on-site archives.
How is agentic AI changing record platforms?
Record vendors are moving from single AI features toward agents that complete multi-step tasks for staff. Ambient scribes now listen to visits and draft notes, while billing assistants generate appeal letters for denied claims. Hospitals that adopt these tools aim to cut documentation time and reduce burnout among physicians and nurses. As a result, AI becomes a standard line item in record contracts rather than a pilot project.
Where is the opening in payer and provider data sharing?
The 2027 API deadline in the U.S. creates a clear opening for vendors that sell data exchange, prior authorization and claims software. In July 2025, CMS said more than 60 companies had pledged to support a new interoperability framework, including 21 networks and 7 record vendors. Payers that automate prior authorization can cut manual review costs and speed decisions for providers. Vendors with ready FHIR-based products are well placed to win these contracts before the deadline.
Can life sciences data platforms add a new buyer group?
Drug developers offer a growing opening, because clinical trials now rely on electronic data capture, remote monitoring and real-world evidence. Companies such as IQVIA sell trial software and data services that draw on de-identified records from health systems. Regulators increasingly accept real-world evidence to support label changes and safety studies. In turn, the life sciences industry adds spending that grows faster than provider demand through 2035.
Cyberattacks, integration gaps and staff shortages
How do cyberattacks raise risk and cost?
Health care data is a prime target for ransomware, because a single breach can stop billing and clinical work for weeks. The February 2024 attack on Change Healthcare, a unit of UnitedHealth Group, disrupted claims processing across the U.S. In January 2025, the company estimated that 190 million people were affected. Such incidents force providers to spend more on cyber security defenses, backups and recovery plans, which diverts budgets from new clinical software.
Why do integration gaps slow data use?
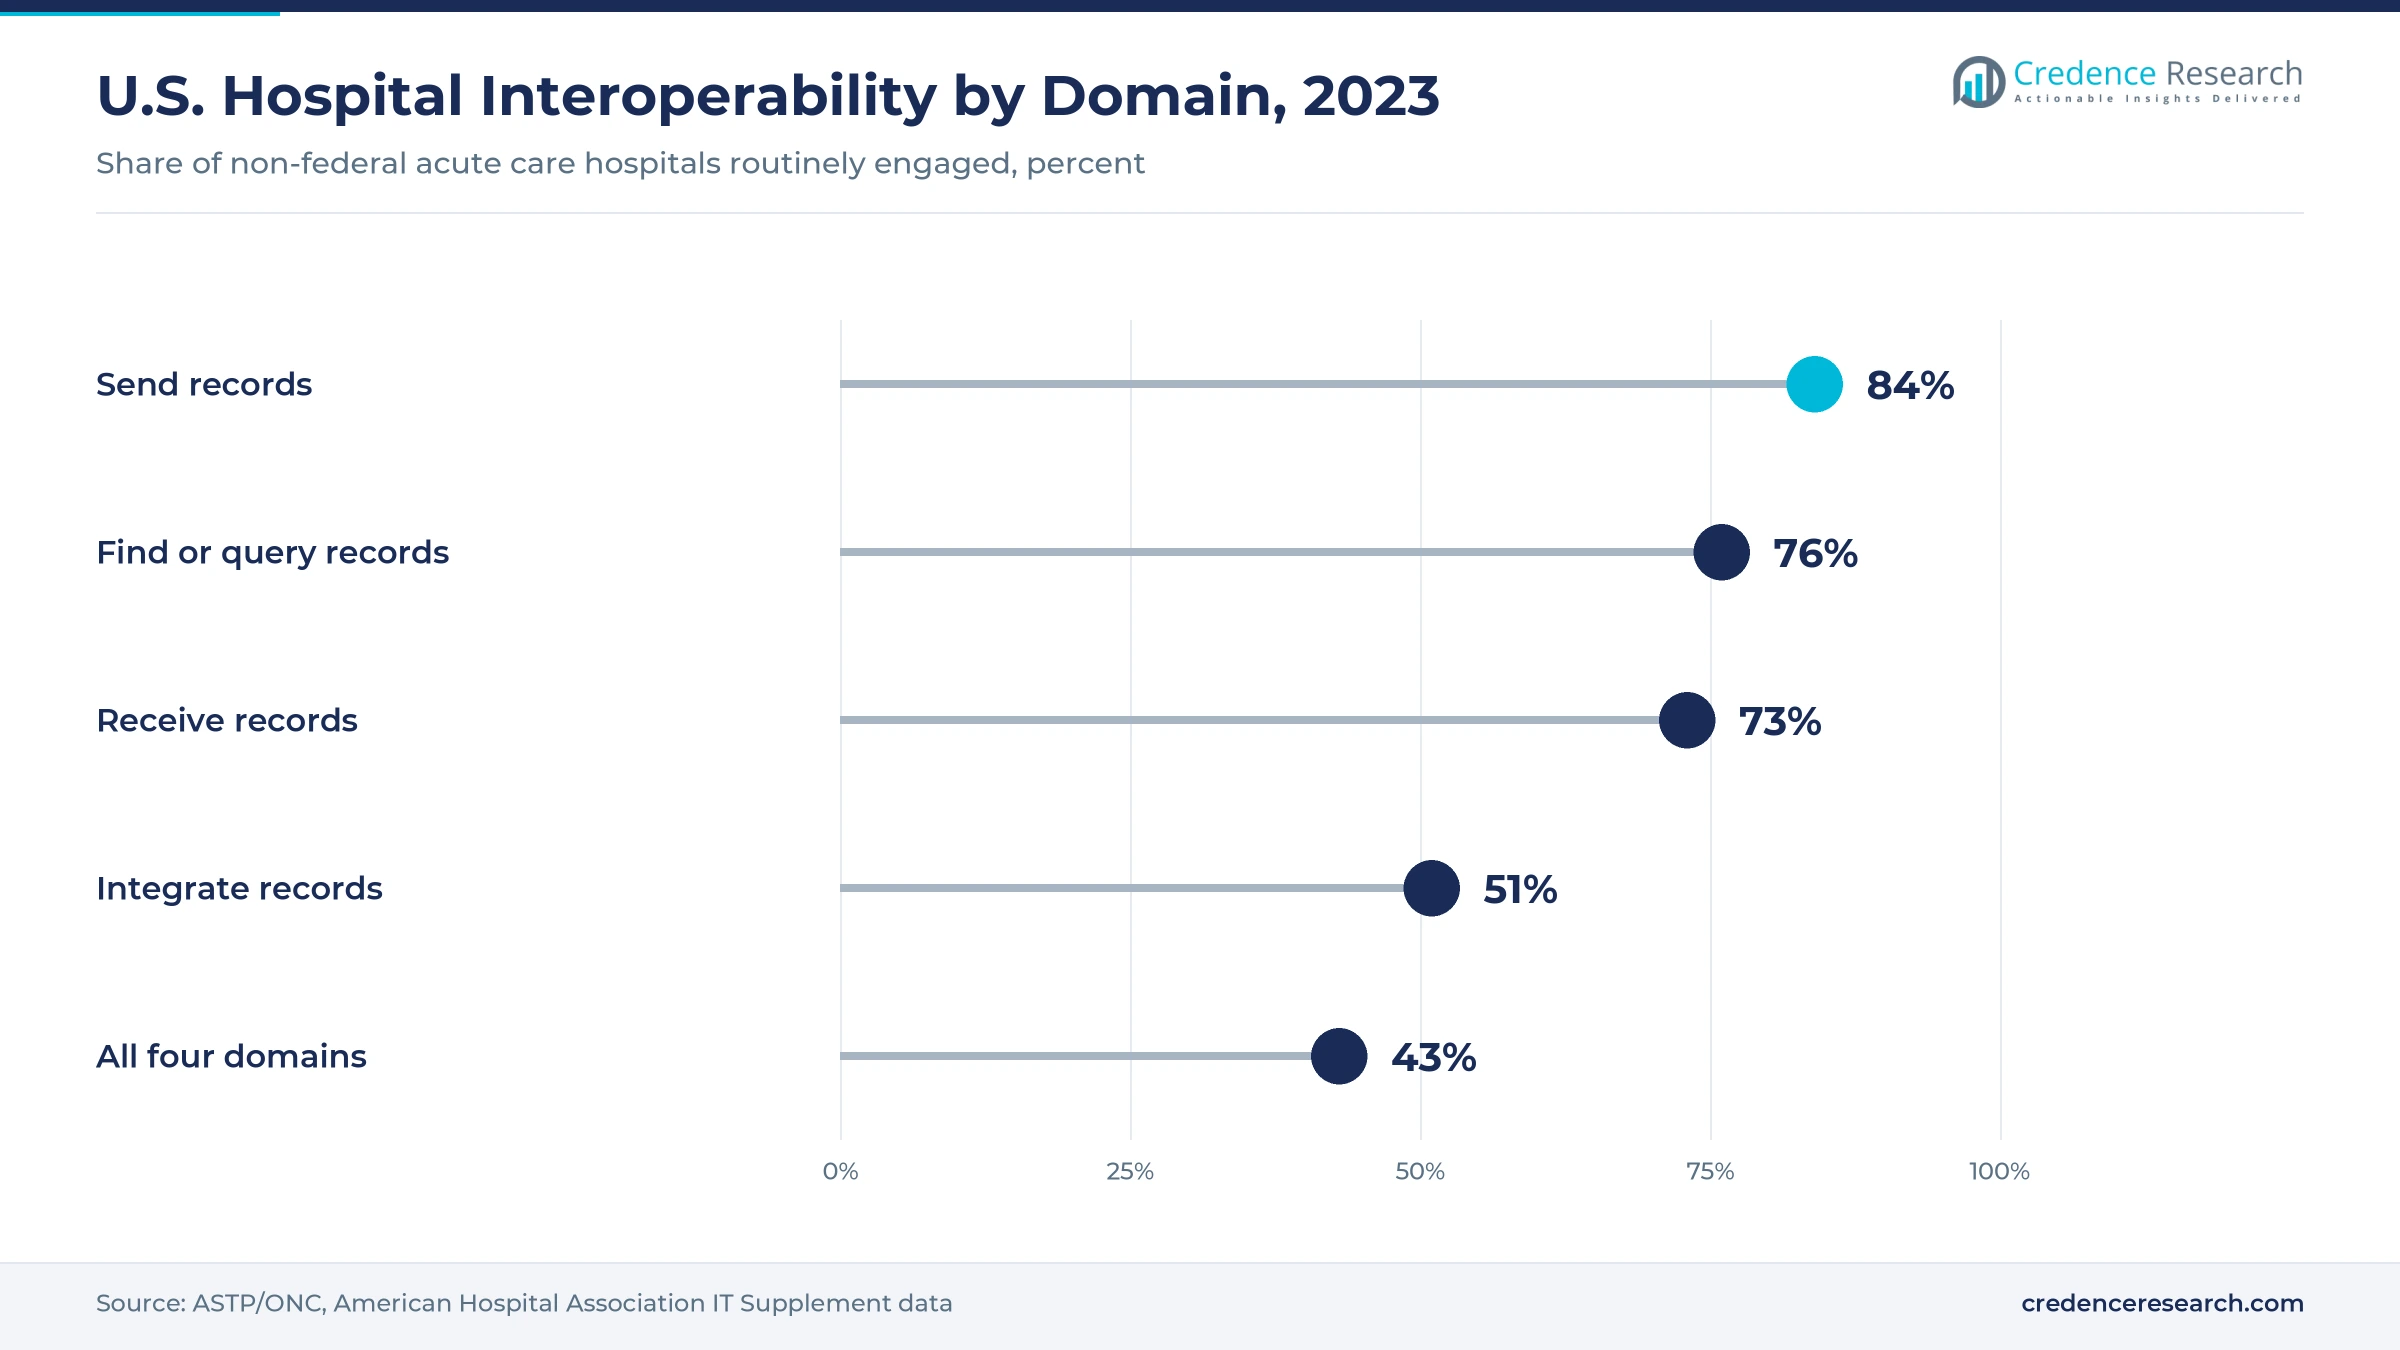
Many hospitals can send and receive records but still struggle to bring outside data into their own systems. Federal survey data for 2023 show that only 43% of non-federal acute care hospitals were routinely interoperable across all 4 exchange domains. Integration of outside records lagged at 51%, well below sending at 84% and receiving at 73%. Outside information was routinely available to clinicians in 71% of hospitals, yet only 42% of hospitals said clinicians often used outside information at the point of care. As a result, clinicians often re-enter outside data by hand.
What limits adoption in smaller providers?
Small hospitals, rural clinics and independent practices often lack the budgets and staff to replace older systems. Implementation projects for large record platforms can take 12 months or more and require trained analysts and clinical champions. Because of these limits, many small providers delay upgrades or rely on basic systems with fewer features. Vendors respond with cloud-hosted versions and bundled services, although uptake remains slower than in large health systems.
Why do AI governance rules add compliance work?
Hospitals and vendors must show that AI tools are safe, accurate and fair before using them widely in patient care. Regulators in the U.S. and Europe are adding transparency requirements for predictive models built into record systems. Health systems now set up review committees to test models and monitor their performance over time. This oversight adds cost and slows rollouts, especially for smaller vendors that lack formal validation teams.
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 254.28 | 44.0% | 10.79% |
| Europe | 150.26 | 26.0% | 10.79% |
| Asia Pacific | 121.36 | 21.0% | 12.59% |
| Latin America | 28.90 | 5.0% | 11.89% |
| Middle East & Africa | 23.12 | 4.0% | 12.09% |
North America leads on mandates and AI adoption
North America held a 44.0% share of 2025 value and grows at 10.79% a year through 2035. The U.S. leads spending, because nearly all hospitals already run certified record systems and now add AI assistants, analytics and payer data exchange tools. Federal rules on prior authorization and patient access set firm deadlines for insurers in 2026 and 2027. Canada adds demand through provincial record programs and virtual care services that reach remote communities.
Europe builds toward a shared data space
Europe held a 26.0% share of 2025 value and grows at 10.79% a year through 2035. Germany, France, the U.K., the Netherlands and the Nordic countries account for most regional demand. The European Health Data Space sets common rules for record systems and cross-border exchange, which drives certification and replacement projects before the March 2029 target for cross-border summaries. Public procurement cycles and tight hospital budgets, however, keep growth slightly below the global average.
Asia Pacific grows on national digital programs
Asia Pacific held a 21.0% share of 2025 value and is the fastest-growing region at 12.59% a year. China and India are connecting public hospitals through national digital health programs and unique patient identifiers. Japan and Australia upgrade records and picture archiving and communication systems in large hospitals. As private hospital chains expand, demand rises for cloud-hosted records and analytics across the region.
Latin America expands public record programs
Latin America held a 5.0% share of 2025 value and grows at 11.89% a year through 2035. Brazil and Mexico lead demand, with public systems investing in shared records and virtual care for underserved areas. Private hospital groups buy imaging and revenue cycle software, while budget limits slow adoption in smaller public facilities.
Middle East and Africa invest in new hospitals
The Middle East & Africa held a 4.0% share of 2025 value and grows at 12.09% a year. Gulf states such as Saudi Arabia and the United Arab Emirates build new hospitals with integrated record and imaging platforms from the start. In much of Africa, donor-funded programs focus on basic records and laboratory systems for public clinics.
Rules, platform deals and AI launches since 2024
| Development | Status and market relevance |
|---|---|
| In January 2024, CMS released its interoperability and prior authorization final rule, requiring new payer APIs by January 2027. | In force. Drives payer spending on data exchange software. |
| In March 2025, the European Health Data Space regulation entered into force, with cross-border patient summaries due by March 2029. | In force. Drives record certification across the EU. |
| In July 2025, CMS announced that more than 60 companies pledged to support a new interoperability framework and patient apps. | Voluntary. Results expected from early 2026. |
| In August 2025, Epic introduced AI assistants named Art, Emmie and Penny for clinicians, patients and billing staff. | Rolling out. Adds AI features to record platforms. |
| In March 2026, GE HealthCare completed its acquisition of Intelerad for a base price of USD 2.3 billion in cash. | Completed. Expands cloud imaging software reach. |
AI agents, FHIR APIs and cloud archives reach care teams
- Generative AI assistants draft clinical notes, answer patient questions and prepare claim appeals inside record platforms.
- FHIR-based APIs let patients, providers and payers exchange records and prior authorization data in standard formats, with four payer APIs due in 2027.
- Cloud imaging archives store and share radiology studies across sites and support AI reading tools.
- Predictive analytics flag patients at risk of readmission or high cost so care managers can act earlier.
- Remote monitoring platforms send readings from connected home devices into the record for review by care teams.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Record vendors, imaging firms and payer platforms compete
Competition splits into large record platforms, imaging software makers, payer and pharmacy services firms, and data specialists. Epic Systems leads hospital records in the U.S. and expands AI assistants across its platform, while Veradigm, Athenahealth and eMDs serve physician practices and ambulatory groups. Koninklijke Philips, GE Healthcare and Agfa-Gevaert compete in imaging information systems, with GE Healthcare adding Intelerad in March 2026. McKesson and Optum sell pharmacy, revenue cycle and payer software and services, and IQVIA serves drug developers with trial technology and real-world data. Vendors compete on integration, AI features, cloud hosting and compliance with new data exchange rules. Large health systems tend to consolidate on one core platform, which raises switching costs and rewards vendors with broad product suites.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Epic Systems Corporation | Record platform | Hospital records and AI assistants |
| Koninklijke Philips N.V. | Imaging and informatics | Enterprise imaging and patient monitoring software |
| GE Healthcare | Imaging and informatics | Enterprise imaging, including Intelerad |
| Agfa-Gevaert Group | Imaging software | Enterprise imaging platforms |
| McKesson Corporation | Services and software | Pharmacy and provider technology |
| Optum, Inc. | Payer and provider services | Claims, analytics and revenue cycle software |
| Veradigm Inc. | Ambulatory software | Practice records and payer data services |
| Athenahealth, Inc. | Cloud ambulatory software | Practice records and revenue cycle |
| eMDs, Inc. | Ambulatory software | Records and practice management for small practices |
| IQVIA | Life sciences data | Clinical trial technology and real-world data |
Data exchange mandates set the spending agenda to 2030
Credence Research's view is that data exchange mandates and AI assistants will set the spending agenda through 2030. Payers face firm API deadlines on Jan. 1, 2027, and European record makers must certify products for the shared data space before 2029. At the same time, AI tools give hospitals a reason to expand contracts with existing vendors instead of switching. Vendors that combine broad platforms, cloud hosting and strong security are best placed, although cyber risk remains the main threat to buyer confidence.
How the 2025 baseline and forecast were built
The report uses 2025 as the base year and forecasts market value to 2035, with growth rates stated for 2026–2035. Market values come from the Credence Research market model, which combines provider, payer and life sciences spending on software, hardware and services by region. Splits by component, application, end use and region are Credence Research estimates. Sources used include CMS, ASTP and EU publications, and company press releases and filings. No primary interviews or surveys were used to build the estimates in this report.
Connected records and AI shape digital care to 2035
By 2035, the market reaches USD 1,686.22 billion, with value moving toward cloud software, AI assistants and data exchange services. Electronic records remain the largest application, although analytics and tele-healthcare gain share every year. Payers and life sciences companies become larger buyers as API rules and real-world evidence spread. Asia Pacific narrows the gap with Europe as national programs connect more hospitals. Security and AI oversight become standard parts of every contract, shaping how vendors design and sell their products.
Frequently Asked Questions
How big is the healthcare IT market?
Which component leads the market?
Which application grows fastest?
Which region holds the largest share?
What does the CMS prior authorization rule require?
How interoperable are U.S. hospitals?
Who are the leading companies?
What are the main challenges?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Application
- 1.3.1 Electronic Health Records
- 1.3.2 Clinical Information Systems
- 1.3.3 Medical Imaging Information Systems
- 1.3.4 Tele-healthcare
- 1.3.5 Healthcare Analytics
- 1.3.6 Population Health Management
- 1.3.7 Computerized Provider Order Entry Systems
- 1.3.8 eClinical Solutions
- 1.3.9 Laboratory Information
- 1.3.10 E-Prescribing Solutions
- 1.3.11 Others
- 1.4 By End Use
- 1.4.1 Healthcare Providers
- 1.4.2 Healthcare Payers
- 1.4.3 Life Sciences Industry
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 577.92 billion → 2035: USD 1,686.22 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Healthcare IT Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Healthcare IT Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Healthcare IT Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Healthcare IT Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Healthcare IT Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Healthcare IT Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Healthcare IT Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Healthcare IT Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 577.92 billion → 2035: USD 1,686.22 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Healthcare IT Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Electronic Health Records
- 12.4.7.2 Clinical Information Systems
- 12.4.7.3 Medical Imaging Information Systems
- 12.4.7.4 Tele-healthcare
- 12.4.7.5 Healthcare Analytics
- 12.4.7.6 Population Health Management
- 12.4.7.7 Computerized Provider Order Entry Systems
- 12.4.7.8 eClinical Solutions
- 12.4.7.9 Laboratory Information
- 12.4.7.10 E-Prescribing Solutions
- 12.4.7.11 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Healthcare Providers
- 12.5.7.2 Healthcare Payers
- 12.5.7.3 Life Sciences Industry
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Healthcare IT End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Healthcare IT Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Healthcare IT Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Healthcare IT Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Koninklijke Philips N.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 McKesson Corporation
- 18.4 eMDs, Inc.
- 18.5 Veradigm Inc.
- 18.6 GE Healthcare
- 18.7 Athenahealth, Inc.
- 18.8 Agfa-Gevaert Group
- 18.9 Optum, Inc.
- 18.10 IQVIA
- 18.11 Epic Systems Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

