
Market Overview
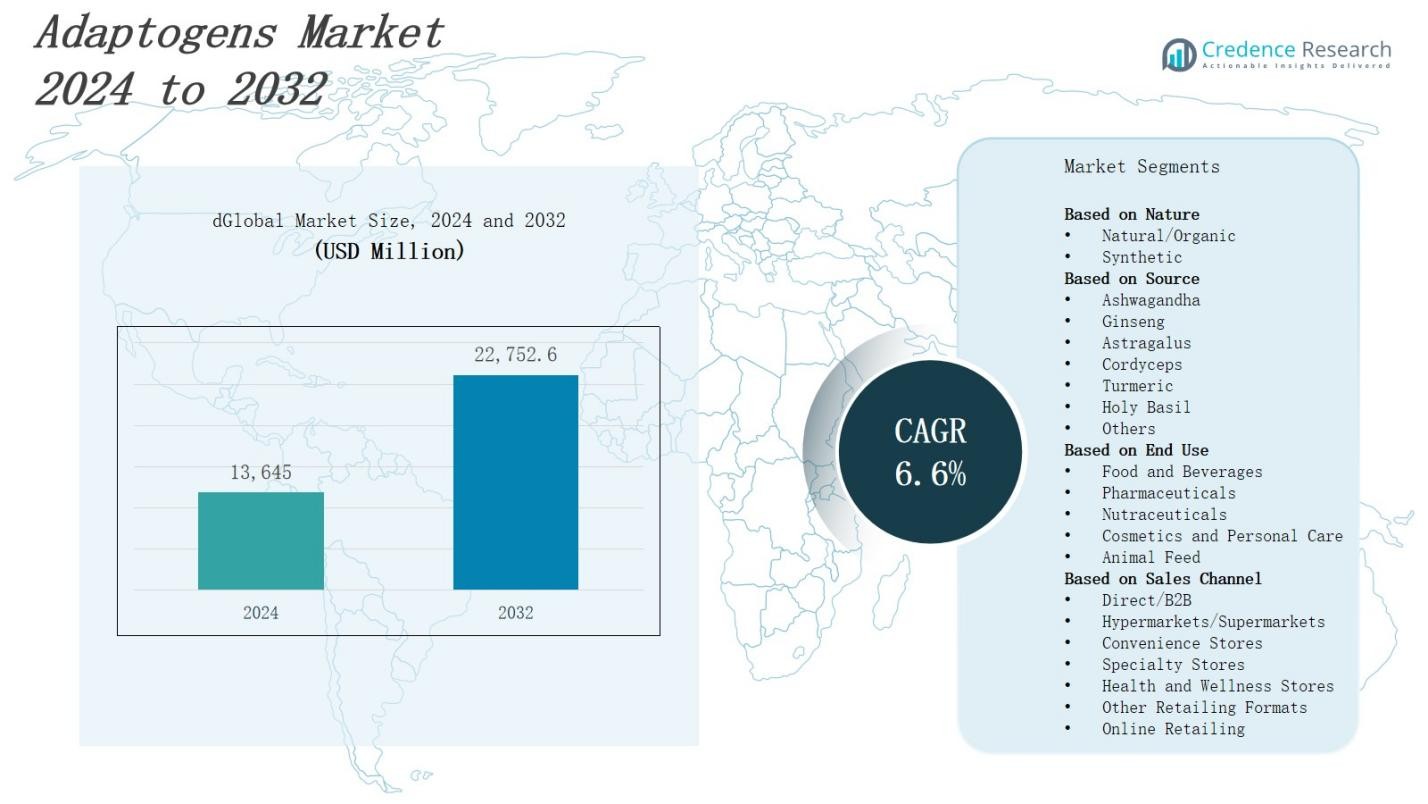
The adaptogens market is projected to grow from USD 13,645 million in 2024 to USD 22,752.6 million by 2032, registering a compound annual growth rate (CAGR) of 6.6%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Adaptogens Market Size 2024 | USD 13,645 Million |
| Adaptogens Market, CAGR | 6.6% |
| Adaptogens Market Size 2032 | USD 22,752.6 Million |
Rising consumer demand for natural health solutions drives the adaptogens market, fueled by increasing awareness of their stress-relief and immune-boosting benefits. Growing interest in holistic wellness and preventive healthcare encourages product innovation and diversification. Advances in extraction and formulation technologies improve product efficacy and appeal. Expanding applications across functional foods, beverages, and dietary supplements broaden market reach. Additionally, the rise of e-commerce and specialty health stores enhances accessibility and distribution. These factors collectively accelerate market growth, while ongoing research investments validate health claims, reinforcing consumer confidence and supporting sustained adoption worldwide.
The adaptogens market spans key regions including North America, Europe, Asia-Pacific, and the Rest of the World, with North America leading in market share followed by Europe and Asia-Pacific. Emerging markets in Latin America, the Middle East, and Africa contribute to expanding demand in the Rest of the World segment. Leading key players in the market include REBBL, Organic India, NutraScience Labs, Nutracap Labs, Organika Health Products Inc, PLT Health Solutions, Xi’an Greena Biotech Co. Ltd., Organic Herb Inc, Xian Yuensun Biological Technology Co. Ltd., and UNO VETCHEM. These companies drive innovation and growth globally.
Market Insights
- The adaptogens market is projected to grow from USD 13,645 million in 2024 to USD 22,752.6 million by 2032, with a CAGR of 6.6%.
- Rising consumer demand for natural health solutions drives market growth, supported by increasing awareness of stress-relief and immune-boosting benefits.
- Growing interest in holistic wellness and preventive healthcare encourages product innovation and diversification across supplements, foods, and beverages.
- Advances in extraction and formulation technologies improve product efficacy and consumer appeal, expanding market reach.
- E-commerce platforms and specialty health stores enhance accessibility, facilitating wider distribution and adoption.
- The market faces challenges due to regulatory uncertainty and lack of standardized definitions, complicating compliance and delaying product launches.
- Supply chain constraints, including seasonal availability and raw material variability, create risks that require sustainable sourcing and strategic partnerships to manage effectively.
Market Drivers
Increasing Consumer Preference for Natural and Holistic Health Solutions
Rising awareness of the adverse effects of synthetic drugs motivates consumers to seek natural alternatives, driving demand in the adaptogens market. People increasingly turn to herbal supplements and natural remedies to manage stress, fatigue, and immunity. This shift encourages manufacturers to develop diverse adaptogenic products that cater to health-conscious buyers. The trend toward preventive healthcare amplifies the focus on natural ingredients. Growing interest in wellness and balanced lifestyles supports the adoption of adaptogens in daily routines. It promotes continuous innovation and wider acceptance across demographics.
- For instance, Nordic Naturals has innovated in omega fatty acid supplements, emphasizing natural extraction and bioavailability improvements, which cater to consumers prioritizing natural solutions for cognitive and heart health.
Expansion of Functional Food and Beverage Applications
The integration of adaptogens into functional foods and beverages broadens market potential significantly. Consumers demand products that combine health benefits with convenience, leading companies to infuse adaptogens in teas, energy drinks, and snacks. This expansion helps brands differentiate their offerings in a crowded marketplace. It also fosters collaboration between supplement producers and food manufacturers. The rising popularity of ready-to-consume health products boosts the incorporation of adaptogens. This development strengthens the market’s penetration into mainstream retail and online platforms, driving sales growth.
- For instance, ADM incorporates adaptogenic extracts such as guarana and yerba mate in their functional teas and energy drinks, providing natural caffeine sources alongside health-promoting botanicals, thus aligning with demand for clean-label wellness products.
Technological Advancements in Extraction and Formulation
Improvements in extraction techniques enhance the potency and purity of adaptogenic ingredients, increasing product effectiveness. Innovative formulation technologies allow for better bioavailability and consumer-friendly delivery formats like capsules, powders, and liquids. These advancements raise product appeal by addressing taste, stability, and absorption challenges. It enables companies to meet stringent quality standards and regulatory requirements. Enhanced efficacy fosters consumer trust and repeat purchases. Such progress in technology underpins sustained market growth and diversification of adaptogen-based offerings.
Growing Distribution Channels and Market Accessibility
The expansion of e-commerce platforms and specialty health stores increases adaptogens market accessibility globally. Consumers benefit from convenient online shopping and a wider product range, encouraging trial and adoption. Retail partnerships and collaborations facilitate entry into new geographic regions and consumer segments. The rise of subscription models and direct-to-consumer sales enhances brand loyalty and customer retention. It also supports small and emerging players by reducing traditional market entry barriers. This broader distribution network accelerates product availability and supports ongoing demand growth.
Market Trends
Integration of Adaptogens in Beverages and Functional Foods
The adaptogens market witnesses a strong trend toward incorporation into beverages and functional foods, meeting consumer demand for convenient health products. Brands introduce adaptogenic teas, energy drinks, and smoothies to appeal to on-the-go lifestyles. These products combine wellness benefits with enjoyable flavors, attracting a broad audience. Companies invest in innovative recipes that maintain ingredient potency while enhancing taste. This trend encourages collaboration between supplement manufacturers and food and beverage companies, expanding market reach and diversifying product portfolios.
- For instance, Kin Euphorics targets mood-enhancing experiences with adaptogenic drinks that serve as alcohol-free substitutes by blending nootropics and herbal ingredients for relaxation, focus, and social engagement.
Focus on Clean-Label and Sustainable Sourcing Practices
Consumers increasingly prefer products with transparent ingredient lists and sustainable sourcing, shaping the adaptogens market. Brands emphasize organic cultivation and ethical harvesting of raw materials to align with environmental and social responsibility goals. Companies highlight clean-label certifications to build consumer trust and justify premium pricing. It also supports regulatory compliance in various regions. The emphasis on sustainability drives innovation in supply chain management and packaging, helping companies meet evolving consumer expectations and reinforce their market position.
- For instance, brands like REBBL incorporate eco-friendly packaging made from recyclable materials to reinforce sustainability commitments and meet evolving consumer expectations for both the product and its environmental impact.
Rising Investments in Research and Clinical Validation
The adaptogens market benefits from growing investments in scientific research to substantiate health claims and improve product credibility. Clinical trials and studies focus on stress reduction, immune support, and cognitive enhancement associated with adaptogenic herbs. Companies collaborate with academic institutions and research organizations to develop evidence-based formulations. This trend helps overcome skepticism and regulatory hurdles in global markets. It also facilitates product differentiation by emphasizing proven efficacy, thereby strengthening consumer confidence and driving market growth.
Expansion of Digital Marketing and E-commerce Channels
The adaptogens market leverages digital marketing strategies and e-commerce platforms to enhance visibility and accessibility. Brands engage consumers through social media, influencer partnerships, and targeted advertising campaigns that educate about adaptogen benefits. Online sales channels provide convenience and detailed product information, encouraging purchases. Subscription services and personalized recommendations further improve customer experience. This trend reduces geographic limitations, enabling brands to reach diverse consumer segments efficiently. It accelerates market penetration and supports sustained demand growth.
Market Challenges Analysis
Regulatory Uncertainty and Lack of Standardization
The adaptogens market faces challenges due to inconsistent regulatory frameworks across different regions. It complicates product approval processes and limits global market expansion. Lack of standardized definitions and quality benchmarks for adaptogenic ingredients creates confusion among manufacturers and consumers. Companies struggle to ensure compliance while maintaining product efficacy and safety. This regulatory ambiguity hinders innovation and delays product launches. It also reduces consumer confidence due to varying product claims and quality. Navigating these complexities demands significant investment in legal expertise and quality assurance.
Supply Chain Constraints and Raw Material Variability
The adaptogens market encounters supply chain challenges linked to the seasonal availability and geographic concentration of key herbs. It faces risks from inconsistent raw material quality and limited cultivation regions. Fluctuations in supply impact production schedules and increase costs. Dependence on wild-harvested plants raises sustainability concerns and exposes companies to environmental and ethical scrutiny. These factors complicate long-term planning and scalability for manufacturers. Securing reliable, high-quality raw materials requires strategic partnerships and investment in sustainable farming practices to mitigate risks and ensure consistent supply.
Market Opportunities
Expansion into Emerging Markets with Growing Health Awareness
The adaptogens market can capitalize on increasing health consciousness in emerging economies where consumers seek natural wellness solutions. Rising disposable incomes and urbanization drive demand for dietary supplements and functional products. It presents opportunities to introduce adaptogen-based formulations tailored to local preferences and health concerns. Collaborating with regional distributors and leveraging culturally relevant marketing strategies can accelerate market entry. Penetration into these markets also benefits from improving healthcare infrastructure and rising internet accessibility. Targeted efforts in these regions can unlock substantial growth potential for manufacturers and brands.
Innovation in Product Formats and Personalized Nutrition
The adaptogens market has significant scope for developing innovative product formats that enhance convenience and consumer appeal. It can leverage advancements in nutraceutical technologies to create powders, gummies, beverages, and ready-to-consume supplements. Personalized nutrition trends allow companies to offer customized adaptogen blends based on individual health profiles and lifestyle needs. Digital tools and data analytics support targeted product development and consumer engagement. Expanding product diversity and personalization strengthens brand differentiation and encourages customer loyalty. These strategies enable the market to capture evolving consumer demands and foster sustained expansion.
Market Segmentation Analysis:
By Nature
The adaptogens market divides into natural/organic and synthetic segments based on nature. The natural/organic category dominates due to rising consumer preference for clean-label and minimally processed products. It benefits from increased trust in plant-based ingredients and perceived health advantages. Synthetic adaptogens serve niche applications where cost-effectiveness and controlled formulation are critical. However, it faces challenges from regulatory scrutiny and lower consumer acceptance. Market players focus on expanding natural product lines to align with shifting consumer priorities and regulatory trends.
- For instance, KSM-66 Ashwagandha by Ixoreal Biomed is recognized for its high concentration and standardized quality, appealing to health-conscious consumers prioritizing natural efficacy.
By Source
The adaptogens market categorizes sources into key herbs such as ashwagandha, ginseng, astragalus, cordyceps, turmeric, holy basil, and others. Ashwagandha and ginseng lead the segment due to extensive clinical research and wide applications in stress relief and immunity. Cordyceps and turmeric gain traction for their antioxidant and anti-inflammatory properties. It drives innovation in blends and formulations that combine multiple adaptogens for synergistic effects. Companies invest in sustainable sourcing to ensure quality and meet growing demand.
- For instance, cordyceps is gaining use particularly among athletes for improving stamina and oxygen uptake, supporting fatigue reduction.
By End Use
The adaptogens market segments by end use into food and beverages, pharmaceuticals, nutraceuticals, cosmetics and personal care, and animal feed. Food and beverages capture significant share, driven by demand for functional products like teas and energy drinks. Pharmaceuticals leverage adaptogens for supportive therapies, while nutraceuticals target wellness-focused consumers. Cosmetics incorporate adaptogens for skin benefits, enhancing product appeal. Animal feed applications present emerging opportunities by promoting health and productivity in livestock. It encourages diverse product development to serve multiple industries effectively.
Segments:
Based on Nature
- Natural/Organic
- Synthetic
Based on Source
- Ashwagandha
- Ginseng
- Astragalus
- Cordyceps
- Turmeric
- Holy Basil
- Others
Based on End Use
- Food and Beverages
- Pharmaceuticals
- Nutraceuticals
- Cosmetics and Personal Care
- Animal Feed
Based on Sales Channel
- Direct/B2B
- Hypermarkets/Supermarkets
- Convenience Stores
- Specialty Stores
- Health and Wellness Stores
- Other Retailing Formats
- Online Retailing
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share in the adaptogens market, accounting for 35% of the global revenue. High consumer awareness of natural health products and strong demand for stress-relief supplements drive growth in this region. It benefits from well-established distribution networks, including specialty health stores and e-commerce platforms. Regulatory frameworks support product innovation and safety, encouraging manufacturers to introduce diverse adaptogen-based offerings. Rising adoption of functional foods and beverages fuels market expansion. The presence of leading market players and ongoing research further strengthen North America’s dominant position.
Europe
Europe commands 28% of the adaptogens market share, driven by increasing health-conscious consumers and rising adoption of holistic wellness products. It features strict regulatory standards that encourage high-quality product development and build consumer trust. The region’s mature nutraceutical and pharmaceutical industries facilitate the integration of adaptogens into various formulations. It also experiences growing demand for organic and sustainably sourced ingredients. Expanding retail channels and digital platforms enhance accessibility across countries. Collaborations between manufacturers and research institutions foster innovation and market growth.
Asia-Pacific
Asia-Pacific represents 25% of the adaptogens market, fueled by traditional use of herbal medicines and rising urbanization. It experiences growing consumer interest in preventive healthcare and natural remedies. The region’s abundant supply of raw materials like ashwagandha and ginseng supports cost-effective production. It benefits from expanding middle-class populations with increasing disposable incomes. Government initiatives to promote natural health products and improving healthcare infrastructure boost adoption. The rise of e-commerce platforms further facilitates market penetration in rural and urban areas.
Rest of the World
The Rest of the World holds 12% of the adaptogens market share, with emerging interest in natural wellness solutions across Latin America, the Middle East, and Africa. It faces challenges related to limited awareness and distribution infrastructure but offers untapped growth potential. It benefits from increasing health awareness campaigns and improving retail networks. Growing investments in sustainable sourcing and local cultivation can support market expansion. Regional collaborations and strategic partnerships help companies overcome entry barriers and capitalize on evolving consumer preferences in these markets.
Key Player Analysis
- NutraScience Labs
- Xi’an Greena Biotech Co. Ltd.
- UNO VETCHEM
- PLT Health Solutions
- Organic India
- Xian Yuensun Biological Technology Co. Ltd.
- Organika Health Products Inc
- REBBL
- Organic Herb Inc
- Nutracap Labs
Competitive Analysis
The adaptogens market features a competitive landscape with key players focusing on product innovation, strategic partnerships, and geographic expansion to strengthen their positions. Leading companies invest heavily in research and development to enhance the efficacy and bioavailability of adaptogenic formulations. It drives the introduction of diverse product offerings across supplements, functional foods, and beverages. Companies emphasize sustainable sourcing and quality assurance to meet stringent regulatory requirements and consumer expectations. Strategic collaborations with raw material suppliers and distributors enable wider market penetration. It faces competition from both established nutraceutical firms and emerging specialized brands that capitalize on niche consumer segments. Marketing efforts increasingly leverage digital platforms and influencer partnerships to build brand awareness and customer loyalty. Continuous adaptation to evolving consumer trends and regulatory landscapes determines the market leaders’ ability to maintain and grow their market shares. The presence of global and regional players intensifies competition, pushing innovation and efficiency in production and distribution. This competitive environment fosters steady growth and diversification within the adaptogens market.
Recent Developments
- In May 2024, Herbochem launched +91 ASHWAGANDHA, a full-spectrum extract targeting technology-related mental health issues by enhancing essential nutrients like potassium and magnesium for mental wellness.
- In February 2025, Constellation Brands invested in Hiyo, an organic non-alcoholic tonic with adaptogens and nootropics, expanding its non-alcoholic beverage portfolio.
- In August 2024, Emami Limited acquired The Man Company, a premium male grooming brand specializing in natural ingredient-based products, strengthening its presence in the adaptogens market.
- In September 2023, Gaia Herbs released a new line of adaptogenic gummies catering to the growing demand for accessible stress-relief supplements.
Market Concentration & Characteristics
The adaptogens market exhibits a moderately concentrated competitive landscape, with several key players holding significant market shares alongside numerous emerging companies. It features a mix of established nutraceutical firms and specialized brands focusing on natural and organic product offerings. Market participants prioritize innovation in formulation, sustainable sourcing, and quality assurance to differentiate themselves. It demands continuous investment in research to validate health benefits and comply with evolving regulatory standards. The market’s characteristics include diverse product applications across supplements, functional foods, beverages, and personal care, catering to growing consumer interest in holistic wellness. Regional variations in regulatory frameworks and raw material availability influence competitive dynamics. Companies leverage digital marketing and e-commerce channels to expand reach and engage consumers effectively. This environment fosters steady growth while encouraging efficiency and product diversification to meet evolving consumer preferences in the adaptogens market.
Report Coverage
The research report offers an in-depth analysis based on Nature, Source, End Use, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer demand for natural health products will drive continued growth and diversification in the adaptogens market.
- Companies will develop advanced formulations to improve absorption and effectiveness of adaptogenic supplements.
- Functional foods and beverages infused with adaptogens will expand rapidly, appealing to health-conscious consumers.
- Digital platforms and e-commerce will increase accessibility and brand visibility globally for adaptogen products.
- Sustainable sourcing practices will become a key focus to meet consumer expectations and regulatory requirements.
- Increased scientific research will support stronger health claims and foster greater consumer trust and adoption.
- Regulatory harmonization across regions will simplify market entry and accelerate product launches worldwide.
- Emerging economies will provide new growth opportunities due to rising disposable incomes and wellness trends.
- Personalized adaptogen blends tailored to individual health needs will attract a broader, niche consumer base.
- Collaborations between manufacturers and suppliers will improve supply chain stability and expand distribution channels.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Consumer Preference for Natural and Holistic Health Solutions
Consumers are shifting away from synthetic drugs due to concerns about side effects, seeking natural alternatives like adaptogens for stress management, immunity, and overall wellness. This trend is encouraging manufacturers to innovate and expand their adaptogen product lines to meet the demand for clean-label, plant-based solutions.
Expansion of Functional Food and Beverage Applications
Adaptogens are increasingly being incorporated into functional foods and beverages such as teas, energy drinks, and snacks, meeting consumer demand for convenient health products. This integration broadens the market’s reach and drives collaboration between supplement and food manufacturers.
Technological Advancements in Extraction and Formulation
Improvements in extraction and formulation technologies are enhancing the potency, purity, and bioavailability of adaptogenic ingredients. These advancements increase product efficacy and consumer appeal, supporting higher adoption rates and enabling companies to meet regulatory and quality standards.
Growing Distribution Channels and Market Accessibility
The rise of e-commerce platforms and specialty health stores has made adaptogen products more accessible to a global consumer base. Enhanced distribution networks, including direct-to-consumer and subscription models, are facilitating market penetration and supporting sustained growth.
Rising Investments in Research and Clinical Validation
Increased funding for scientific research and clinical trials is helping to substantiate the health claims of adaptogens, improving product credibility and consumer trust. This validation supports regulatory approval and differentiates products in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Adaptogens market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Adaptogens market projected to grow between 2025 and 2032?
Which Adaptogens market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Adaptogens market?
Who are the leading companies in the Adaptogens market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Nature
- 1.2.1 Natural/Organic
- 1.2.2 Synthetic
- 1.3 By Source
- 1.3.1 Ashwagandha
- 1.3.2 Ginseng
- 1.3.3 Astragalus
- 1.3.4 Cordyceps
- 1.3.5 Turmeric
- 1.3.6 Holy Basil
- 1.3.7 Others
- 1.4 By End Use
- 1.4.1 Food and Beverages
- 1.4.2 Pharmaceuticals
- 1.4.3 Nutraceuticals
- 1.4.4 Cosmetics and Personal Care
- 1.4.5 Animal Feed
- 1.5 By Sales Channel
- 1.5.1 Direct/B2B
- 1.5.2 Hypermarkets/Supermarkets
- 1.5.3 Specialty Stores
- 1.5.4 Health and Wellness Stores
- 1.5.5 Online Retailing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13,645 million → 2032: USD 22,752.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Adaptogens Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Adaptogens Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Adaptogens Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Adaptogens Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Adaptogens Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Adaptogens Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Adaptogens Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Adaptogens Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13,645 million → 2032: USD 22,752.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Adaptogens Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Nature - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Natural/Organic
- 12.3.7.2 Synthetic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ashwagandha
- 12.4.7.2 Ginseng
- 12.4.7.3 Astragalus
- 12.4.7.4 Cordyceps
- 12.4.7.5 Turmeric
- 12.4.7.6 Holy Basil
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverages
- 12.5.7.2 Pharmaceuticals
- 12.5.7.3 Nutraceuticals
- 12.5.7.4 Cosmetics and Personal Care
- 12.5.7.5 Animal Feed
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Direct/B2B
- 12.6.7.2 Hypermarkets/Supermarkets
- 12.6.7.3 Specialty Stores
- 12.6.7.4 Health and Wellness Stores
- 12.6.7.5 Online Retailing
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Adaptogens End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Adaptogens Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Adaptogens Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Adaptogens Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 REBBL
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Organic India
- 18.4 NutraScience Labs
- 18.5 Nutracap Labs
- 18.6 Organika Health Products Inc
- 18.7 PLT Health Solutions
- 18.8 Xi’an Greena Biotech Co. Ltd.
- 18.9 Organic Herb Inc
- 18.10 Xian Yuensun Biological Technology Co. Ltd.
- 18.11 UNO VETCHEM
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

