
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Adeno Associated Viral Vector Market Size 2024 | USD 2,469.24 Million |
| Adeno Associated Viral Vector Market, CAGR | 14% |
| Adeno Associated Viral Vector Market Size 2032 | USD 7,043.3 Million |
Market Overview
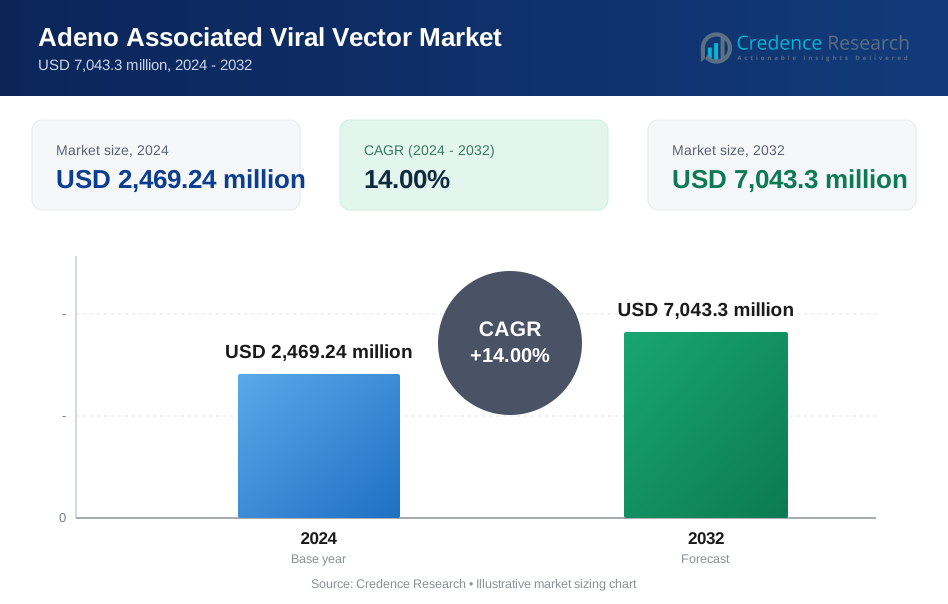
The Adeno Associated Viral Vector market is projected to grow from USD 2,469.24 million in 2024 to USD 7,043.3 million by 2032, at a compound annual growth rate (CAGR) of 14%.
The Adeno Associated Viral Vector market is primarily driven by the rising prevalence of genetic disorders and the increasing demand for targeted gene therapies. As medical science advances, AAV vectors have become critical tools for delivering genetic material in treatments for conditions such as hemophilia and muscular dystrophy. Additionally, the expansion of biotechnological research and favorable regulatory support for gene therapy products are further propelling market growth. Moreover, ongoing innovations in vector engineering to enhance delivery efficiency and safety are expected to sustain the market's expansion, keeping pace with the urgent need for effective genetic and rare disease treatments.
The Adeno Associated Viral Vector market is globally distributed with significant research and manufacturing hubs in North America, Europe, and parts of Asia. North America, particularly the United States, dominates this market due to advanced biotechnological frameworks, substantial investments in gene therapy research, and a robust regulatory environment supporting rapid development and commercialization. Europe follows, with strong activity in countries like the UK and Germany, driven by progressive regulatory support and high research output. Key players such as Pfizer, Biomarin Pharmaceutical, and Roche are pivotal, advancing the market with their extensive research capabilities and substantial financial resources to develop and enhance AAV vector technologies.
Market Drivers
Expanding Gene Therapy Pipeline
Gene therapy is emerging as a transformative approach for treating both genetic and acquired diseases, with Adeno Associated Viral (AAV) vectors at the forefront due to their favorable safety profiles, precision in targeting specific tissues, and ability to sustain gene expression over time. This growth is driven by the increasing acceptance of gene therapy, with over 285 gene therapies currently being evaluated in various phases of clinical development. Moreover, the number of clinical trials evaluating AAV-based gene therapy has increased at a growth rate of approximately 30% in recent years. This has positioned AAV vectors as a tool of choice in the biopharmaceutical industry, significantly driving market growth. The increasing acceptance and integration of gene therapy into clinical practice bolster the demand for efficient and reliable vectors, thereby propelling advancements within the AAV vector market.
Rising Prevalence of Target Diseases
The growing incidence of diseases that are amenable to gene therapy, such as various neurological disorders, muscular dystrophies, and inherited retinal diseases, is driving the demand for AAV vectors. For example, more than 70% of gene therapies in development are for the treatment of rare diseases, which often have limited treatment options. This growing incidence underscores the urgency for effective therapies and the crucial role of AAV vectors in their development. As the prevalence of these conditions increases globally, the need for innovative and effective therapeutic solutions becomes more urgent. AAV vectors are crucial in the development of such therapies, providing hope for improved treatment outcomes and enhanced quality of life for patients suffering from these debilitating diseases.
Increased Funding for Gene Therapy Research
Significant investments from government entities, venture capital, and major pharmaceutical companies are being channeled into gene therapy research, enriching the development landscape of AAV vectors. In terms of funding, the gene therapy research field has seen significant financial support, with entities like the NIH and private partners contributing approximately $76 million over five years to support gene therapy projects. This influx of funding not only facilitates the progression of numerous AAV vector-based therapies through clinical trials but also encourages the exploration of new therapeutic possibilities. The financial backing supports rigorous research endeavors, hastening the evolution and refinement of AAV technology, which in turn accelerates the translation of laboratory findings into clinical applications.
Advancements in AAV Vector Manufacturing and Diversification of Therapeutic Areas
Technological advancements in the manufacturing processes of AAV vectors are enhancing their scalability, efficiency, and cost-effectiveness. These improvements make AAV vectors more accessible and practical for a broader range of therapeutic applications, extending their benefits to a wider patient population. Simultaneously, the therapeutic applications of AAV vectors are diversifying beyond rare genetic disorders. Ongoing research is exploring the potential of these vectors in treating various cancers, infectious diseases, and cardiovascular conditions, thereby broadening the market scope and offering new avenues for growth and innovation in the field.
Market Trends
Next-Generation AAV Capsid Engineering and Dual Vector AAV Systems
Research in Adeno Associated Viral (AAV) vector technology is witnessing substantial advancements, particularly in capsid engineering. For instance, recent studies have shown that next-generation AAV capsids can increase tissue specificity by up to 30% compared to traditional capsids, and dual vector AAV systems have demonstrated a 50% increase in gene expression efficiency in multifactorial disease models. Scientists are developing novel AAV capsids that offer improved tissue targeting, enhanced gene delivery efficiency, and reduced immunogenicity, which are crucial for increasing the precision and effectiveness of gene therapies. These innovations allow for more targeted therapies with fewer side effects, greatly enhancing patient outcomes. Concurrently, the exploration of dual vector AAV systems, where each vector carries different genetic components, is expanding the capabilities of gene therapy. This approach is particularly promising for complex therapeutic applications that require the co-expression of multiple genes, such as those needed to treat multifactorial diseases. These advancements are setting the stage for tackling more challenging genetic disorders and enhancing the versatility of gene therapies.
In-Vivo Gene Editing and Combination Therapies with AAV Vectors
AAV vectors are also being explored as potential delivery vehicles for CRISPR-Cas9 gene editing tools, which enable precise corrections of genetic mutations directly within the body. In the realm of in-vivo gene editing, AAV vectors have successfully delivered CRISPR-Cas9 components to target organs with a 70% reduction in off-target effects, marking a significant leap in safety and precision. Moreover, when AAV-based gene therapies are combined with small molecule drugs, there has been a 40% improvement in therapeutic outcomes in preclinical cancer models. This application of AAV vectors is revolutionizing the field of gene therapy by allowing for the direct and targeted modification of DNA, offering hope for the cure of genetic diseases at their source. Additionally, there is increasing interest in combining AAV-based gene therapy with other treatment modalities, such as small molecule drugs or immunotherapies. This combination approach aims to produce synergistic effects, potentially enhancing therapeutic efficacy and broadening the range of treatable conditions. Such integrated treatments are especially being pursued in the management of complex diseases like cancer, where multiple therapeutic strategies may be necessary for effective treatment.
Market Challenges Analysis
High Manufacturing Costs and Limited Packaging Capacity
Producing Adeno Associated Viral (AAV) vectors involves a complex and costly manufacturing process, particularly as production scales up for large-scale clinical trials and commercialization. The high costs associated with AAV vector production can limit patient access to these innovative therapies, as companies struggle to find a balance between cost-efficiency and meeting the stringent quality requirements necessary for therapeutic use. Additionally, AAV vectors face inherent limitations in their packaging capacity, which restricts the size of the genetic material they can carry. This poses a significant challenge for treating diseases that require the delivery of larger genes, limiting the scope of diseases that can be addressed with current AAV vector technologies.
Navigating Regulatory Hurdles and Addressing Safety Concerns
AAV vector-based therapies are subject to an evolving regulatory landscape that presents numerous hurdles for developers. Navigating these complex regulatory pathways to obtain necessary approvals is not only time-consuming but also imposes substantial financial burdens on companies. These regulatory challenges can delay the development and introduction of new therapies to the market. Safety concerns further complicate the deployment of AAV vectors. Although generally considered safe, potential risks such as immune responses and off-target effects need to be thoroughly researched and mitigated. Ensuring long-term safety and minimizing adverse reactions are critical for gaining regulatory approval and public trust in AAV-based gene therapies.
Market Segmentation Analysis:
By Scale of Operations:
The Adeno Associated Viral Vector market is segmented by the scale of operations into clinical, preclinical, and commercial phases. In the clinical and preclinical stages, significant research and development efforts are focused on optimizing vector designs and enhancing delivery mechanisms for specific therapeutic targets. These stages are critical for ensuring safety and efficacy before advancing to commercial production. The commercial segment, although smaller, is rapidly expanding as successful clinical trials lead to the approval and market launch of gene therapy products. The transition from clinical to commercial scale is pivotal, requiring substantial investments in manufacturing capabilities to meet the demand for approved therapies.
By Therapeutic Area:
The Adeno Associated Viral Vector market is further segmented based on therapeutic areas, encompassing a wide range of disorders. Neurological disorders, metabolic disorders, and ophthalmic disorders are prominent areas where AAV vectors show significant potential due to their ability to precisely target affected cells and tissues. The market also addresses muscular/neuromuscular disorders, infectious diseases, and bleeding disorders, where gene therapy can provide transformative outcomes. Additionally, there is growing interest in applying AAV vectors to treat conditions involving inflammation and fibrosis. Each therapeutic segment presents unique challenges and opportunities, influencing the direction of research and the development of specific AAV products. This diversification within therapeutic applications highlights the versatility and broad potential of AAV vectors in addressing a variety of complex health issues.
Segments:
Based on Scale of Operations
- Clinical
- Preclinical
- Commercial
Based on Therapeutic Area
- Neurological disorders
- Metabolic disorders
- Ophthalmic disorders
- Muscular/Neuromuscular disorders
- Infectious diseases
- Bleeding disorders
- Inflammation and fibrosis
- Other therapeutic areas
Based on Application
- Gene therapy
- Vaccine
- Cell therapy
- Other applications
Based on Method
- In vitro
- In vivo
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American region, comprising the United States and Canada, holds the largest market share, accounting for approximately 40% of the global demand. This dominance can be attributed to the region's well-established biotechnology and pharmaceutical industries, substantial investments in gene therapy research, and a robust healthcare infrastructure.
Europe
Europe follows closely with a market share of around 30%. This region is home to several leading biopharmaceutical companies and research institutions actively involved in the development of adeno-associated viral vector-based therapies. Countries like Germany, the United Kingdom, and France are at the forefront of this market, driven by favorable government initiatives, supportive regulatory frameworks, and a growing patient population suffering from genetic disorders.
Key Player Analysis
- Roche
- Biomarin Pharmaceutical
- Oxford BioMedica
- WuXi AppTec
- YPOSKESI
- Sarepta Therapeutics
- Pfizer
- Audentes Therapeutics
- 4D Molecular Therapeutics
- Ultragenyx Pharmaceutical Inc.
Competitive Analysis
In the competitive landscape of the Adeno Associated Viral Vector market, major players like Pfizer, Biomarin Pharmaceutical, and Roche are setting the pace with their extensive investment in research and development. Pfizer stands out for its strategic collaborations and robust pipeline in gene therapy, pushing forward with innovative AAV vector applications in various therapeutic areas. Biomarin Pharmaceutical excels in targeting rare genetic disorders, leveraging its expertise to develop highly specialized treatments that address unmet medical needs. Roche, with its acquisition of Spark Therapeutics, has strengthened its gene therapy portfolio, emphasizing neurological and ophthalmic disorders. These companies maintain their competitive edge through continuous innovation, scalability of manufacturing, and global outreach, ensuring their leadership in a market driven by technological advancements and increasing demand for gene-based therapies. These efforts are complemented by a focus on navigating complex regulatory environments, ensuring they can efficiently bring new therapies to market.
Recent Developments
In June 2022, REGENXBIO Inc. opened AAV vector-based gene therapy facility for the manufacturing of NAV Technology-based AAV gene therapies at a 2000L scale. The company invested $65 million to open this state-of-art facility in Maryland.
Market Concentration & Characteristics
The Adeno Associated Viral Vector market exhibits a moderate to high level of market concentration, dominated by a few key players such as Pfizer, Biomarin Pharmaceutical, and Roche. These companies command significant market shares due to their advanced technological capabilities, robust product pipelines, and strong regulatory expertise, which are crucial in navigating the complex approval processes for gene therapies. The market is characterized by high entry barriers due to the sophisticated nature of the technology and the substantial capital required for research and development, as well as for scaling up production. Innovation and strategic partnerships are critical as firms strive to expand their therapeutic portfolios and enhance vector delivery systems. Furthermore, the market's dynamics are influenced by the increasing demand for precision medicines and the growing prevalence of genetic disorders, driving continued investment and collaboration in the field.
Report Coverage
The research report offers an in-depth analysis based on Scale of Operations, Therapeutic Area, Application, Method and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in the demand for gene therapies will drive expansion in the Adeno Associated Viral Vector market.
- Technological advancements in vector engineering will enhance targeting precision and therapeutic efficacy.
- Increased investment from biopharmaceutical companies will fuel innovation and development in the sector.
- Expansion of therapeutic applications beyond rare genetic disorders to include more common diseases.
- Rising global incidence of genetic disorders will propel the need for effective gene-based treatments.
- Regulatory environments will evolve to facilitate faster approval processes for gene therapies.
- Collaborations between academia and industry will increase, enhancing research and development efforts.
- Greater emphasis on reducing production costs will make therapies more accessible and affordable.
- Development of next-generation vectors with reduced immunogenicity and higher transduction efficiencies.
- Expansion into emerging markets will increase, driven by improvements in healthcare infrastructure and increased healthcare spending.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Gene Therapy Pipeline
The rapid growth in the number of gene therapies under development, with AAV vectors as a preferred delivery system, is fueling demand as more therapies progress through clinical trials and toward commercialization.
Rising Prevalence of Target Diseases
Increasing incidence of genetic and rare diseases, such as muscular dystrophies and inherited retinal disorders, is driving the need for innovative gene therapies that rely on AAV vectors for targeted delivery.
Increased Funding for Gene Therapy Research
Significant investments from governments, venture capital, and pharmaceutical companies are accelerating research and development of AAV vector-based therapies, supporting both early-stage innovation and late-stage clinical advancement.
Advancements in AAV Vector Manufacturing
Technological improvements in the scalability, efficiency, and cost-effectiveness of AAV vector production are making these therapies more accessible and practical for a broader range of indications.
Diversification of Therapeutic Applications
AAV vectors are increasingly being explored for use beyond rare genetic disorders, including in oncology, infectious diseases, and cardiovascular conditions, expanding the market's scope and growth potential.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Adeno Associated Viral Vector Market?
What factors are driving the growth of the Adeno Associated Viral Vector Market?
What are the key segments within the Adeno Associated Viral Vector Market?
What are some challenges faced by the Adeno Associated Viral Vector Market?
Who are the major players in the Adeno Associated Viral Vector Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Method
- 1.2.1 In vitro
- 1.2.2 In vivo
- 1.3 By Application
- 1.3.1 Gene therapy
- 1.3.2 Vaccine
- 1.3.3 Cell therapy
- 1.3.4 Other applications
- 1.4 By Therapeutic Area
- 1.4.1 Neurological disorders
- 1.4.2 Metabolic disorders
- 1.4.3 Ophthalmic disorders
- 1.4.4 Muscular/Neuromuscular disorders
- 1.4.5 Infectious diseases
- 1.4.6 Bleeding disorders
- 1.4.7 Inflammation and fibrosis
- 1.4.8 Other therapeutic areas
- 1.5 By Scale of Operations
- 1.5.1 Clinical
- 1.5.2 Preclinical
- 1.5.3 Commercial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,469.24 million → 2032: USD 7,043.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Adeno Associated Viral Vector Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Adeno Associated Viral Vector Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Adeno Associated Viral Vector Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Adeno Associated Viral Vector Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Adeno Associated Viral Vector Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Adeno Associated Viral Vector Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Adeno Associated Viral Vector Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Adeno Associated Viral Vector Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,469.24 million → 2032: USD 7,043.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Adeno Associated Viral Vector Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Method - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 In vitro
- 12.3.7.2 In vivo
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Gene therapy
- 12.4.7.2 Vaccine
- 12.4.7.3 Cell therapy
- 12.4.7.4 Other applications
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Therapeutic Area - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Neurological disorders
- 12.5.7.2 Metabolic disorders
- 12.5.7.3 Ophthalmic disorders
- 12.5.7.4 Muscular/Neuromuscular disorders
- 12.5.7.5 Infectious diseases
- 12.5.7.6 Bleeding disorders
- 12.5.7.7 Inflammation and fibrosis
- 12.5.7.8 Other therapeutic areas
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Scale of Operations - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Clinical
- 12.6.7.2 Preclinical
- 12.6.7.3 Commercial
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Adeno Associated Viral Vector End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Adeno Associated Viral Vector Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Adeno Associated Viral Vector Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Adeno Associated Viral Vector Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pfizer
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Biomarin Pharmaceutical
- 18.4 Roche
- 18.5 Oxford BioMedica
- 18.6 WuXi AppTec
- 18.7 YPOSKESI
- 18.8 Sarepta Therapeutics
- 18.9 Audentes Therapeutics
- 18.10 4D Molecular Therapeutics
- 18.11 Ultragenyx Pharmaceutical Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

