
Market Overview:
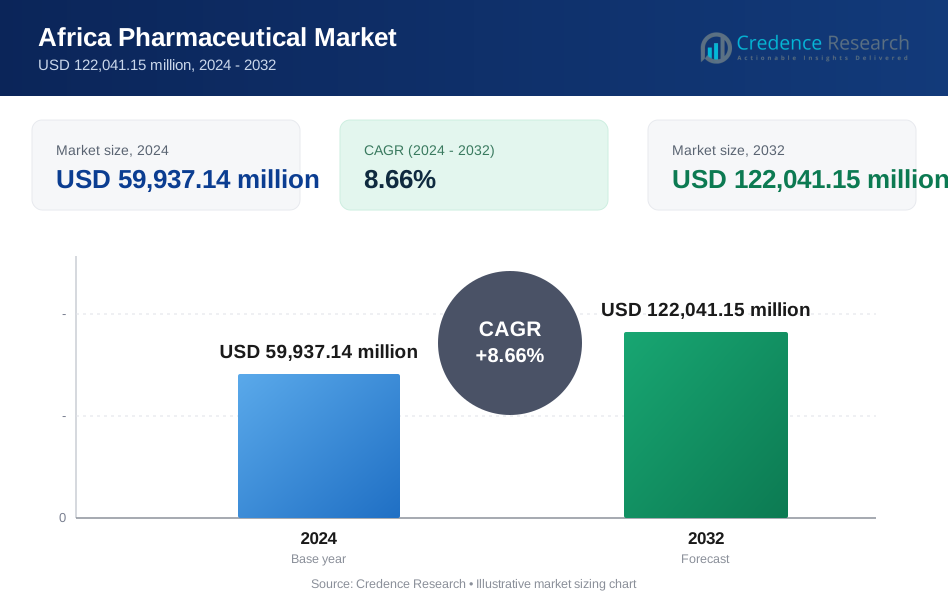
The Africa Pharmaceutical Market size was valued at USD 36,000.03 million in 2018, reaching USD 59,937.14 million in 2024, and is anticipated to attain USD 122,041.15 million by 2032, growing at a CAGR of 8.66% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Africa Pharmaceutical Market Size 2024 | USD 59,937.14 million |
| Africa Pharmaceutical Market, CAGR | 8.66% |
| Africa Pharmaceutical Market Size 2032 | USD 122,041.15 million |
Rising healthcare investments, expanding access to essential medicines, and growth in local drug manufacturing are driving market progress. Government initiatives encouraging universal healthcare coverage have improved affordability and accessibility. Additionally, increased prevalence of chronic diseases such as diabetes and cardiovascular disorders fuels demand for prescription drugs and vaccines. Rapid urbanization, population growth, and a young demographic base further enhance pharmaceutical consumption across both branded and generic categories.
Regionally, South Africa remains the largest pharmaceutical hub due to its strong healthcare infrastructure and regulatory framework. Nigeria and Kenya are emerging markets, supported by expanding private healthcare networks and improving logistics systems. Egypt serves as a major manufacturing and export base for North Africa. Meanwhile, smaller economies like Ghana and Ethiopia are witnessing rising investment in local production and pharmacy retail chains, signaling a broader regional shift toward self-reliance and healthcare modernization.
Market Insights:
- The Africa Pharmaceutical Market was valued at USD 36,000.03 million in 2018, reached USD 59,937.14 million in 2024, and is projected to hit USD 122,041.15 million by 2032, expanding at a CAGR of 8.66% during 2024–2032.
- Southern Africa (34%), North Africa (28%), and West Africa (22%) dominate the market due to strong manufacturing bases, policy support, and rising healthcare spending across South Africa, Egypt, and Nigeria.
- East Africa (10%) is the fastest-growing region, driven by Kenya’s expanding private healthcare infrastructure, rising digital adoption, and growing local pharmaceutical production.
- Prescription drugs account for around 46% of the total market share, supported by increasing demand for chronic and specialist treatments across major countries.
- Over-the-Counter (OTC) drugs hold approximately 24% share, driven by growing self-medication practices, affordability, and broader pharmacy retail penetration across urban and semi-urban Africa.
Market Drivers:
Expanding Healthcare Infrastructure and Access to Medicines
Public and private investments are transforming healthcare systems across Africa, improving access to essential drugs and treatment facilities. Governments are prioritizing universal healthcare coverage, increasing funding for public hospitals and primary care centers. International organizations, including WHO and GAVI, support vaccination and medicine accessibility programs. The Africa Pharmaceutical Market benefits from expanding retail pharmacies and medical distribution networks in rural areas. It encourages market growth through better drug delivery channels and rising consumer awareness. Local companies are investing in affordable generics to meet regional needs. Ongoing partnerships between foreign pharmaceutical firms and local players strengthen production capacity. This evolution supports sustained healthcare advancement across developing economies.
- For instance, Eva Pharma in Egypt produces low-cost generics for broader access. Ongoing partnerships between foreign pharmaceutical firms and local players strengthen production capacity.
Rising Burden of Chronic and Infectious Diseases
Chronic illnesses such as diabetes, hypertension, and cancer are increasing due to urban lifestyles and aging populations. Infectious diseases like malaria, tuberculosis, and HIV/AIDS continue to demand large-scale medical interventions. The Africa Pharmaceutical Market witnesses higher drug demand across therapeutic classes, including antivirals, antibiotics, and cardiovascular drugs. It motivates governments to enhance diagnostic and treatment facilities nationwide. Pharmaceutical manufacturers are expanding research pipelines targeting region-specific health conditions. Health awareness campaigns and early screening programs also elevate prescription volumes. Hospitals and clinics are integrating digital platforms for monitoring and prescription management. The surge in both acute and chronic cases reinforces consistent pharmaceutical consumption patterns.
- For example, local biotech initiatives in South Africa aim to improve oncology treatment options. Health awareness campaigns and early screening programs also elevate prescription volumes. Hospitals and clinics are integrating digital platforms for monitoring and prescription management.
Government Regulations Supporting Local Manufacturing
Several African nations are introducing policy frameworks to reduce dependency on imports. Incentives such as tax exemptions and subsidies promote domestic drug production. The Africa Pharmaceutical Market gains strength through industrial zones dedicated to healthcare manufacturing. It helps lower costs, improve supply chain efficiency, and ensure medicine availability. Countries like South Africa, Egypt, and Nigeria are expanding regulatory harmonization under regional trade agreements. Public-private collaborations support GMP-certified facilities, attracting foreign investment. Health ministries focus on product quality and safety compliance to align with international standards. Localized manufacturing strategies strengthen resilience and job creation in the sector.
Growing Foreign Direct Investments and Strategic Partnerships
Pharmaceutical multinationals view Africa as a high-growth investment destination. Companies are forming alliances with regional manufacturers to optimize supply chains and market access. The Africa Pharmaceutical Market gains momentum through technology transfer and co-production agreements. It enhances the continent’s pharmaceutical self-sufficiency and export potential. Joint ventures allow firms to diversify product portfolios and cater to varied therapeutic needs. Governments facilitate this growth through simplified regulatory procedures and improved intellectual property protection. International donors also support infrastructure and R&D initiatives. The combined impact of partnerships and funding drives market competitiveness and innovation.
Market Trends:
Rapid Expansion of E-Pharmacy and Digital Healthcare Platforms
The shift toward digital health solutions is reshaping medicine distribution and access. Online pharmacies are growing rapidly due to mobile penetration and improved internet infrastructure. The Africa Pharmaceutical Market is leveraging e-commerce platforms to reach underserved populations. It improves convenience, transparency, and product traceability for consumers. Digital payment systems further simplify the purchase process across urban and rural regions. Telemedicine integration strengthens prescription delivery and remote consultations. Companies are investing in AI-driven supply tracking to reduce counterfeiting. This digital shift is creating a more inclusive and efficient pharmaceutical ecosystem.
- For instance, startup mPedigree in Ghana allows consumers to send a unique code via SMS or mobile app to verify drug authenticity instantly, helping fight counterfeit medicines. The Africa Pharmaceutical Market is leveraging e-commerce platforms to reach underserved populations. Digital payment systems simplify purchases across urban and rural regions.
Emergence of Biotechnology and Vaccine Development Initiatives
Africa is positioning itself as an emerging hub for vaccine and biotech innovation. Governments and global organizations are establishing local biotech research centers and partnerships. The Africa Pharmaceutical Market experiences rising interest in biologics and biosimilars to address chronic diseases. It supports clinical research collaborations focusing on endemic and genetic conditions. Nations such as Senegal, South Africa, and Rwanda are developing vaccine manufacturing hubs. The growing presence of technology parks enables advanced pharmaceutical R&D capacity. Increased funding in life sciences fosters innovation in precision medicine. These developments mark a strategic shift from dependency to innovation-led healthcare.
- For instance, Biovac Institute in South Africa partnered with Pfizer in 2023 to produce mRNA vaccines locally. The Africa Pharmaceutical Market experiences rising interest in biologics and biosimilars to address chronic diseases. It supports clinical research collaborations focusing on endemic and genetic conditions. Nations such as Senegal, South Africa, and Rwanda are developing vaccine manufacturing hubs.
Growing Adoption of Generic and Over-the-Counter Medications
Affordability remains a top priority for most consumers, pushing the growth of generics. Pharmaceutical firms are expanding low-cost product portfolios to capture wider demographics. The Africa Pharmaceutical Market benefits from regulatory reforms that favor domestic generic production. It provides opportunities for small and mid-sized manufacturers to expand distribution networks. Pharmacies are diversifying shelves with branded generics and OTC drugs for common ailments. Consumers prefer self-medication for non-critical conditions, raising OTC sales. Increased health literacy and awareness campaigns promote safe medicine usage. Generic adoption ensures healthcare affordability without compromising product quality.
Strengthening Regional Trade Integration and Harmonized Regulation
African trade blocs are working to streamline regulatory standards across member states. Harmonization simplifies cross-border drug approvals and import processes. The Africa Pharmaceutical Market benefits from frameworks like the African Continental Free Trade Area (AfCFTA). It enables cost-efficient distribution and accelerates market entry for manufacturers. Regional collaboration ensures medicine quality and combats counterfeit drug trade. Governments are aligning national policies to improve supply chain transparency. Shared testing and certification facilities reduce duplication and regulatory delays. Such integration fosters competitiveness and enhances intra-African pharmaceutical trade.
Market Challenges Analysis:
Limited Infrastructure, Supply Chain Gaps, and Quality Control Barriers
Weak transportation infrastructure and inadequate cold-chain systems restrict medicine availability. Power shortages and underdeveloped logistics networks increase operational costs. The Africa Pharmaceutical Market faces recurring delays in distribution due to customs bottlenecks. It experiences uneven access to healthcare facilities between urban and rural regions. Counterfeit and substandard drugs remain major risks, affecting consumer confidence. Regulatory enforcement is inconsistent across countries, slowing quality assurance. Limited manufacturing capacity leads to high import dependency. These challenges collectively hinder scalability and efficiency in the pharmaceutical value chain.
Regulatory Complexity and Shortage of Skilled Workforce
Fragmented national regulations make it difficult for pharmaceutical firms to operate across regions. Each country maintains its own approval timelines, documentation, and compliance rules. The Africa Pharmaceutical Market must navigate overlapping legal frameworks and intellectual property concerns. It struggles with insufficient skilled personnel for research, quality control, and clinical development. Training programs remain limited, reducing innovation and production quality. High turnover among healthcare professionals worsens the talent gap. Foreign investors often face bureaucratic hurdles when establishing operations. Addressing regulatory and workforce deficiencies is essential for sustainable market expansion.
Market Opportunities:
Rising Demand for Local Manufacturing and Export Potential
Many African nations are focusing on strengthening domestic production to reduce import reliance. Governments are encouraging technology transfer and investment in pharmaceutical parks. The Africa Pharmaceutical Market holds untapped potential for regional medicine exports. It can serve neighboring countries with cost-effective and high-quality products. Growing middle-class populations create steady demand for branded and specialty drugs. Export-friendly policies under AfCFTA open pathways for intra-continental trade. Investment in manufacturing innovation will improve Africa’s competitiveness globally. This opportunity can position the continent as a rising pharmaceutical production hub.
Expansion of Healthcare Digitization and Research Collaborations
Africa is embracing digital transformation in healthcare delivery and pharmaceutical research. Governments and start-ups are investing in digital health infrastructure and AI analytics. The Africa Pharmaceutical Market benefits from electronic health records and predictive disease monitoring. It enables faster drug development and market insight generation. Collaborations with global R&D firms support clinical trials for regional diseases. Universities are partnering with biotech firms to advance vaccine and biosimilar research. Healthtech adoption will continue driving transparency, efficiency, and innovation. These developments open a new era of integrated healthcare solutions.
Market Segmentation Analysis:
By Product Type
Prescription drugs dominate the Africa Pharmaceutical Market, driven by rising demand for chronic disease treatments and specialist therapies. Over-the-counter (OTC) drugs are gaining share due to growing self-care awareness and affordability. Vaccines hold a strategic position in disease prevention programs, supported by public health funding and global partnerships. Dietary supplements are expanding through lifestyle-focused consumer behavior and rising nutrition awareness. It benefits from increasing demand across preventive healthcare applications and evolving pharmaceutical retail networks across the continent.
- For instance, Quality Chemical Industries Limited in Uganda reported a production capacity of around 1.2 billion pills per year for generic medicines, reflecting the scale of prescription drug output. Over-the-counter (OTC) drugs are gaining share due to growing self-care awareness and affordability.
By Drug Type
Generic drugs lead due to affordability and expanding local manufacturing. Branded drugs maintain a steady share, supported by strong brand loyalty in urban markets. Biosimilars are emerging rapidly with investment in biologics and local R&D centers. The Africa Pharmaceutical Market continues to attract investors focusing on expanding biopharmaceutical production. It reflects a shift toward innovation and value-driven healthcare solutions that meet rising patient expectations. Strengthened regulatory support enhances trust and accessibility across therapeutic categories.
- For example, the shift to generics in countries like South Africa and Egypt was noted in a 2014 McKinsey report, showing increasing generic share at the expense of branded products. Branded drugs maintain a steady share, supported by strong brand loyalty in urban markets. Biosimilars are emerging rapidly with investment in biologics and local R&D centers
By Application
Oncology, cardiology, and diabetes dominate application segments owing to growing chronic disease prevalence. Neurology and respiratory therapies are advancing due to early diagnosis and expanding hospital infrastructure. Other therapeutic areas include infectious and gastrointestinal disorders, contributing to market diversity. The Africa Pharmaceutical Market benefits from improved healthcare access and increasing awareness of long-term treatment compliance. It shows a clear transition toward specialized and preventive medicines across regions.
By Route of Administration and Distribution Channel
Oral drugs lead due to convenience and patient compliance, while parenteral routes serve critical care and hospital-based therapies. Topical products cater to dermatological and pain relief segments. Hospitals remain the largest distribution channel, followed by retail pharmacies with wide regional coverage. Online pharmacies are emerging strongly with e-commerce adoption and digital prescription platforms. It enables consumers to access authentic medicines conveniently, reinforcing overall market expansion across Africa.
Segmentation:
By Product Type
- Prescription Drugs
- Over-the-Counter (OTC) Drugs
- Vaccines
- Dietary Supplements
By Drug Type
- Generic Drugs
- Branded Drugs
- Biosimilars
By Application
- Oncology
- Cardiology
- Diabetes
- Neurology
- Respiratory
- Others
By Route of Administration
- Oral
- Topical
- Parenteral
- Others
By Distribution Channel
- Hospitals
- Retail Pharmacies
- Online Pharmacies
- Others
By Region / Country
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Southern Africa: Dominant Regional Market with Strong Pharmaceutical Infrastructure
Southern Africa holds the largest share of the Africa Pharmaceutical Market, accounting for nearly 34% of total regional revenue in 2024. South Africa leads due to its advanced healthcare infrastructure, established pharmaceutical manufacturing base, and strong regulatory framework. It attracts major global players through favorable investment policies and efficient distribution networks. The region’s mature hospital systems and insurance penetration also drive prescription and chronic disease drug sales. Multinational companies collaborate with domestic manufacturers to expand production and export capabilities. Rising healthcare spending supports innovation in oncology, cardiovascular, and diabetes therapeutics. Southern Africa remains the continent’s pharmaceutical hub, ensuring supply reliability and clinical quality.
North Africa: Expanding Market Supported by Manufacturing and Policy Initiatives
North Africa contributes around 28% market share, driven by Egypt, Algeria, and Morocco. Egypt leads production with a well-established pharmaceutical ecosystem and export-oriented policies. The Africa Pharmaceutical Market benefits from regulatory harmonization under regional trade agreements and growing biologics development. It supports large-scale drug manufacturing with strong R&D investments and skilled labor. Algeria focuses on generic production to meet local demand, while Morocco emphasizes distribution efficiency through modern logistics frameworks. Growing chronic disease prevalence and government-backed healthcare reforms stimulate medicine accessibility. North Africa is rapidly evolving into a center for pharmaceutical innovation and trade within the continent.
West, East, and Central Africa: Emerging Hubs with Rapid Growth Potential
West Africa accounts for roughly 22% market share, led by Nigeria, which is expanding local pharmaceutical production to reduce imports. Kenya dominates East Africa, supported by infrastructure development and a growing private healthcare sector, contributing about 10% of total share. The Africa Pharmaceutical Market in these subregions benefits from population growth, urbanization, and digital transformation in healthcare. It experiences rising investment in retail pharmacy networks and mobile health platforms. Local startups are collaborating with international partners to improve drug accessibility and affordability. Central Africa holds a smaller share of about 6%, yet it is witnessing gradual improvements in healthcare delivery and supply chains. Together, these emerging regions represent the next phase of market expansion and pharmaceutical self-reliance across Africa.
Key Player Analysis:
- Abbott Laboratories
- AbbVie Inc.
- Alfasigma
- Aspen Pharmacare Holdings Limited
- Aurobindo Pharma
- AstraZeneca PLC
- Bristol Myers Squibb
Competitive Analysis:
The Africa Pharmaceutical Market is highly competitive, with a mix of multinational corporations and emerging local manufacturers. It includes companies such as Abbott Laboratories, AstraZeneca, Aspen Pharmacare, AbbVie, Aurobindo Pharma, and Bristol Myers Squibb. These players focus on expanding production facilities, introducing cost-effective generics, and enhancing distribution networks. Regional firms are gaining momentum through government-backed incentives and public health programs. Competition centers on drug affordability, therapeutic innovation, and market reach across urban and rural areas. Strategic collaborations, mergers, and digital integration remain key tactics for market dominance. The market reflects a balance between innovation-driven global brands and affordability-focused local companies.
Recent Developments:
- In October 2025, Abbott Laboratories reported robust momentum in its emerging markets pharmaceutical business, which includes key African countries. Its established pharmaceuticals segment posted an 11.1% organic sales increase in these markets for Q3 2025, driven by high demand for branded generics and new product launches tailored for local health needs in Africa and other regions.
- In October 2025, AbbVie Inc. finalized the acquisition of Gilgamesh Pharmaceuticals' lead candidate bretisilocin, a next-generation psychedelic compound currently in Phase 2 trials for major depressive disorder. This acquisition is part of AbbVie’s strategic investment to enhance its neuroscience and psychiatric pipeline globally, including emerging markets such as Africa, as the company pursues wider access and regional expansion for innovative therapies.
- On October 6, 2025, AstraZeneca PLC entered a high-profile partnership with Algen Biotechnologies in a deal worth up to $555 million. The agreement grants AstraZeneca rights to develop and commercialize gene therapies for immune-related disorders using Algen’s AI-driven discovery platform. This global move aims to fast-track advanced therapeutics into several key markets, aligning with AstraZeneca’s stated commitment to policy initiatives and access programs-such as Healthy Heart Africa-across the continent.
- Aurobindo Pharma made headlines in August 2025 by acquiring the U.S.-based generic drugmaker Lannett Company for $250 million, enhancing its manufacturing capacity and access to niche generics. While Lannett’s core market is the U.S., Aurobindo’s aggressive expansion positions it to leverage global supply chains and route new products to African markets, supporting regional generics and specialty therapy availability.
- In July 2025, Bristol Myers Squibb (BMS) and Bain Capital formed a new independent company focused on developing innovative immunology drugs, with a $300 million investment backing. BMS maintains a significant equity share and grants rights to investigational therapies, some of which are being targeted for introduction into low- and middle-income countries including those across Africa. BMS has also advanced institutional agreements in East Africa to broaden oncology access through collaborative initiatives like the ATOM Coalition.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Drug Type, Application, Route of Administration, and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of local manufacturing will strengthen Africa’s pharmaceutical self-reliance.
- Increasing healthcare expenditure will support greater medicine accessibility.
- Strategic partnerships will drive technology transfer and innovation in production.
- E-pharmacy adoption will accelerate medicine distribution and consumer reach.
- Rising chronic disease prevalence will fuel sustained prescription drug demand.
- Government-led regulatory harmonization will improve product quality and trade efficiency.
- Growing investment in biologics and biosimilars will reshape therapeutic portfolios.
- Regional export capabilities will expand through AfCFTA integration.
- Digital transformation will enhance transparency and supply chain visibility.
- Continuous healthcare infrastructure upgrades will underpin long-term industry growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Africa Pharmaceutical Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Africa Pharmaceutical Market projected to grow between 2024 and 2032?
Which Africa Pharmaceutical Market segment held the largest share in 2024?
Who are the leading companies in the Africa Pharmaceutical Market?
What role do technological advancements, such as telemedicine and e-pharmacies, play in reshaping the pharmaceutical landscape in Africa?
How are international collaborations and investments influencing the African pharmaceutical market, and what impact do they have on research and development, product innovation, and market expansion?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Africa Pharmaceutical Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Africa Pharmaceutical Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 59,937.14 million → 2032: USD 122,041.15 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Africa Pharmaceutical Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Africa Pharmaceutical Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Africa Pharmaceutical Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Africa Pharmaceutical Market Drivers
- 3.3 Africa Pharmaceutical Market Restraints & Challenges
- 3.4 Africa Pharmaceutical Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Africa Pharmaceutical Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Africa Pharmaceutical Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Africa Pharmaceutical category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Africa Pharmaceutical Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Africa Pharmaceutical Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Africa Pharmaceutical market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Africa Pharmaceutical Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Africa Pharmaceutical Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Africa Pharmaceutical Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Africa Pharmaceutical (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Africa Pharmaceutical Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Africa Pharmaceutical Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Africa Pharmaceutical Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Africa Pharmaceutical Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Africa Pharmaceutical Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Africa Pharmaceutical Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Africa Pharmaceutical Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Africa Pharmaceutical Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Africa Pharmaceutical Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
