
Market Overview:
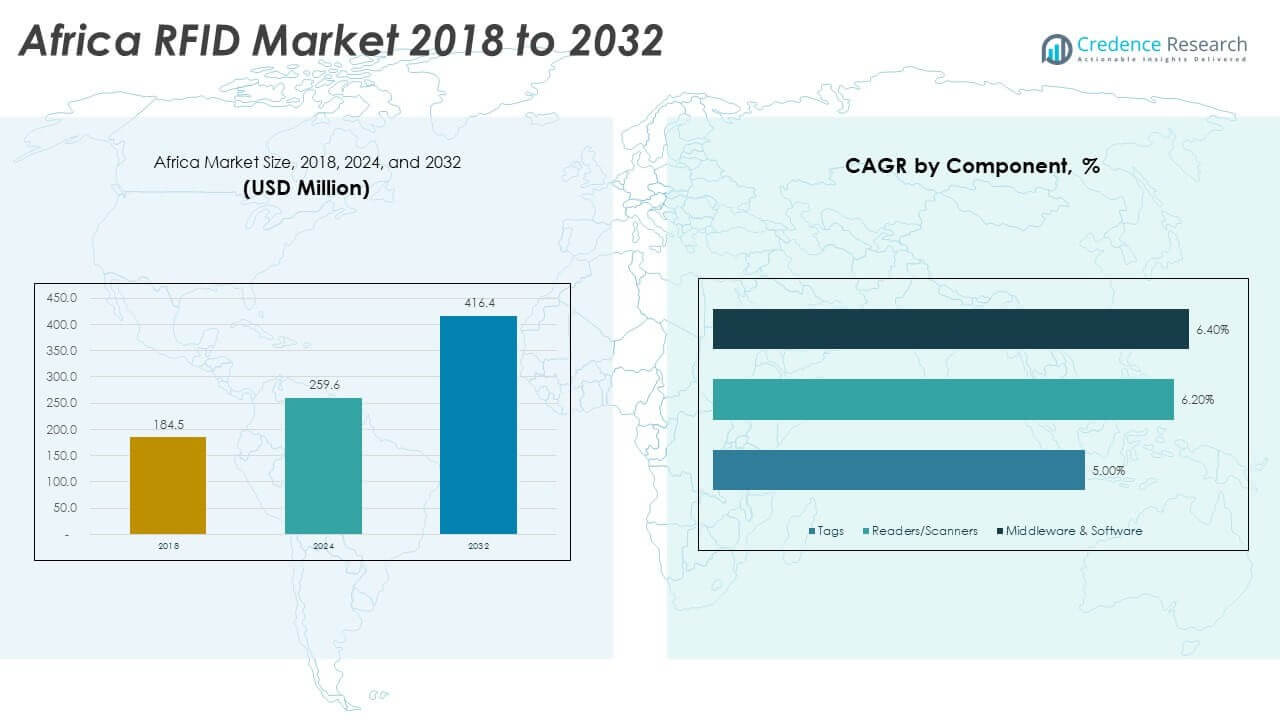
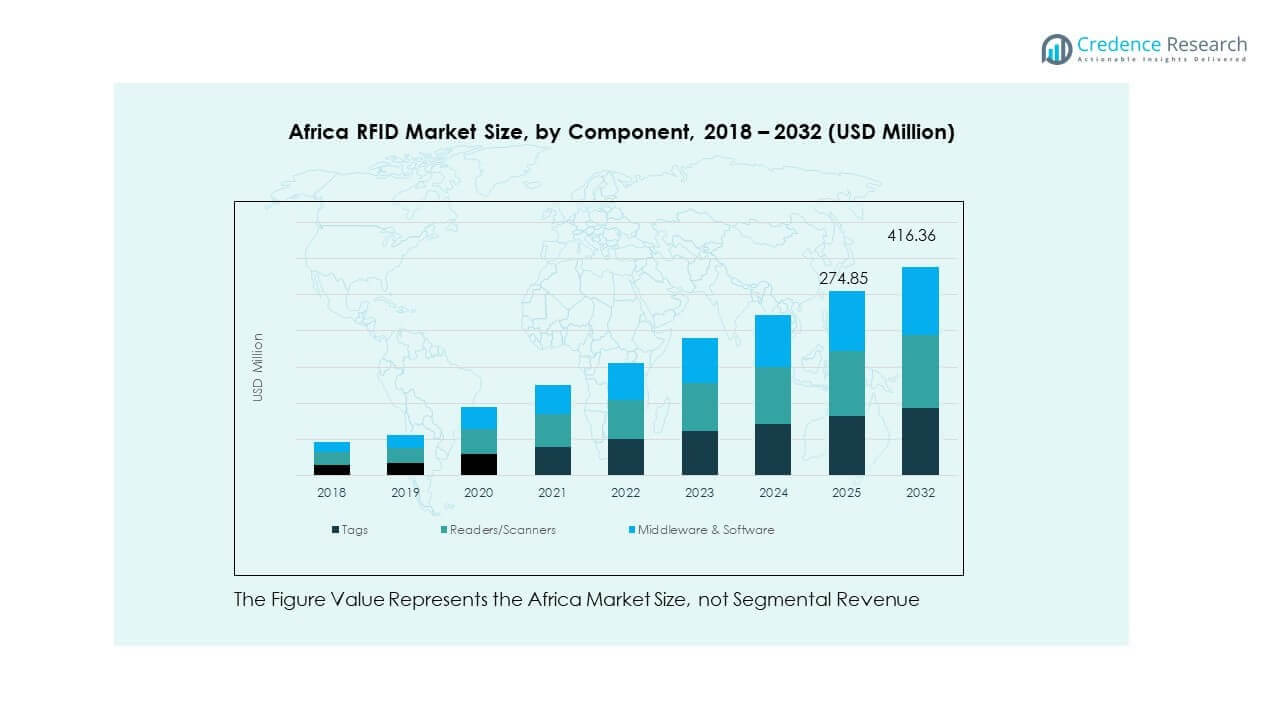
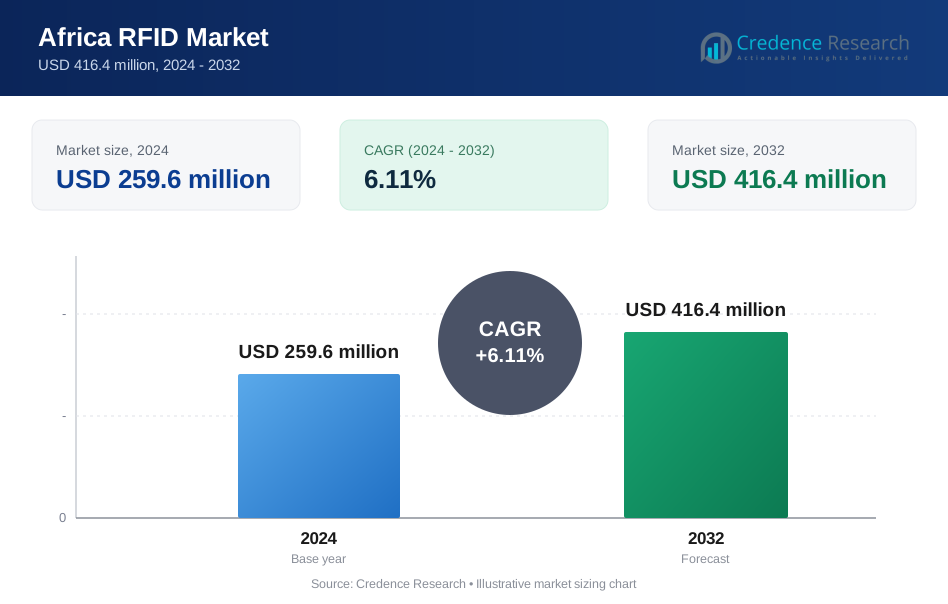
The Africa RFID Market size was valued at USD 184.5 million in 2018 to USD 259.6 million in 2024 and is anticipated to reach USD 416.4 million by 2032, at a CAGR of 6.11% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Africa RFID Market Size 2024 | USD 259.6 million |
| Africa RFID Market, CGR | 6.11% |
| Africa RFID Market Size 2032 | USD 416.4 million |
The market is expanding due to increasing demand for asset visibility, secure identification systems, and inventory automation across public and private sectors. Governments adopt RFID for identity verification, vehicle registration, and livestock tracking, while retailers and logistics firms use it to streamline inventory and reduce shrinkage. Healthcare institutions rely on RFID to track equipment and medication. Declining hardware costs and improved middleware integration support broader adoption across enterprises, educational institutions, and transport systems.
Southern Africa leads due to advanced infrastructure, retail penetration, and strong government digitization programs, particularly in South Africa. North Africa follows, driven by investments in logistics and identity systems in Egypt and Morocco. East Africa is emerging, led by Kenya and Ethiopia, where RFID supports public transport and agriculture. West Africa sees growing activity in Nigeria and Ghana for BFSI and supply chain use. Central Africa remains at an early stage due to infrastructure constraints, but countries like Cameroon and DRC are exploring pilot deployments.
Market Insights
- The Africa RFID Market was valued at USD 184.5 million in 2018, reached USD 259.6 million in 2024, and is projected to touch USD 416.4 million by 2032, expanding at a CAGR of 6.11% during the forecast period.
- Southern Africa leads with 36% share due to strong retail, logistics, and public digitization programs, followed by North Africa at 22% driven by ports and manufacturing, and East Africa at 18% supported by agriculture and public transport adoption.
- East Africa is the fastest-growing region with an 18% share, supported by RFID use in livestock traceability, government ID systems, and expanding logistics networks in Kenya and Ethiopia.
- By component growth distribution, middleware and software show the highest momentum with a CAGR of 6.40%, reflecting rising demand for data integration, analytics, and enterprise system connectivity.
- Readers and scanners follow with a CAGR of 6.20%, while tags grow at 5.00%, indicating sustained demand for large-scale tagging across retail, logistics, and government applications.
Market Drivers
Expansion of Retail, E-Commerce, and Inventory Management Across Urbanizing Regions
Retailers across major African economies deploy RFID to manage inventory with speed and precision. Supermarkets and malls in South Africa, Kenya, and Egypt adopt RFID-tagged goods to reduce shrinkage. It helps track movement from warehouse to shelf, improving supply chain accuracy. Omnichannel retail strategies require faster stock visibility and real-time inventory updates. E-commerce platforms integrate RFID to handle rising order volumes and reduce delivery errors. Return logistics benefit from RFID-based scanning for reverse inventory tracking. RFID improves restocking cycles and supports dynamic pricing models. These functions drive commercial demand across organized retail clusters.
- For instance, Decathlon has deployed item‑level RFID across its global store network, tagging over one billion products annually, enabling inventory accuracy rates above 95% across physical retail operations, including African outlets.
Increased Government Adoption for National Identity, Border, and Asset Programs
Government agencies use RFID to track national ID cards, driving licenses, and passport issuance. Border control agencies implement RFID-enabled e-gates to streamline immigration processes. The Africa RFID Market gains traction through smart ID and voter registration projects. Ministries deploy RFID for document authentication and tamper-proof asset tracking. RFID supports vehicle registrations and license renewals via secure tagging systems. Law enforcement integrates RFID for evidence management and property tracking. These public sector deployments build foundational demand. It strengthens trust in digital infrastructure and citizen services.
Deployment Across Livestock, Agriculture, and Traceability Systems in Rural Zones
Agriculture ministries invest in RFID to monitor livestock health and prevent cross-border disease outbreaks. Livestock RFID ear tags help track herds during transit and quarantine. Traceability requirements from export partners push adoption across abattoirs and cold chains. RFID improves livestock census accuracy and veterinary access. Governments tie subsidies and vaccination records to RFID-based animal IDs. Smallholder cooperatives begin using RFID for crop tagging and fertilizer distribution tracking. It enables remote areas to plug into formal value chains. This rural demand expands the market’s reach.
Smart Infrastructure, Logistics, and Industrial Asset Management Projects
Infrastructure operators deploy RFID to track tools, machinery, and maintenance parts. Toll plazas use RFID-enabled tags for cashless vehicle access and monitoring. Port authorities apply RFID to containers and cargo for end-to-end visibility. The Africa RFID Market benefits from logistics automation across rail, road, and port systems. It supports just-in-time inventory for manufacturers in export processing zones. Industrial parks adopt RFID for safety compliance and workforce monitoring. Mining operators track underground equipment and personnel using active RFID. Infrastructure growth pushes continuous use cases.
- For instance, Anglo American has implemented RFID‑based personnel and equipment tracking systems in underground mining operations, enabling real‑time location monitoring for thousands of workers to improve safety compliance and emergency response times.
Market Trends
Integration of RFID With IoT and Edge Platforms for Real-Time Decision Making
Firms pair RFID with IoT networks to create dynamic, automated systems. Edge computing processes RFID data instantly at the site of collection. The Africa RFID Market supports decision-making without relying on distant servers. Retailers use it for livestock updates and automatic reorder alerts. Logistics firms run RFID-linked dashboards for live asset visibility. Farms connect RFID ear tags to solar-powered readers for remote data sync. Hospitals integrate patient RFID bands into IoT-based alert systems. These converged deployments enhance operational intelligence.
Growth in Passive UHF RFID Solutions for Broader and Cost-Effective Use
Passive UHF tags see increased use due to their long-read ranges and low cost. Retailers adopt these for apparel tracking and theft prevention. The Africa RFID Market gains scale via passive solutions in public services and consumer goods. Healthcare providers use them for consumables and equipment. Government agencies rely on UHF tags for school and library asset tracking. Warehouses tag cartons and pallets to manage load plans and outbound logistics. Passive tags support multi-surface tagging across paper, plastic, and metal. Their affordability widens deployment scope.
- For instance, Murata ID Solutions reports that RFID typically boosts retail inventory accuracy to 98‑99% through passive UHF implementations, helping retailers minimize stockouts and shrinkage.
Adoption of RFID in Healthcare for Patient, Equipment, and Medication Safety
Hospitals implement RFID to track medication dosage, equipment sterilization, and patient movements. Patient ID wristbands reduce wrong-patient errors during treatment. The Africa RFID Market sees adoption in urban hospitals and diagnostic centers. RFID tagging helps locate surgical tools and ensure availability. It supports vaccine cold chains and expiry monitoring in rural clinics. RFID-enabled cabinets restrict access to controlled drugs. Electronic medical record systems link to RFID for time-stamped activity logs. These medical-grade solutions improve accountability.
Use of RFID in Educational Institutions and Examination Integrity Measures
Universities deploy RFID for access control, attendance monitoring, and library asset tracking. RFID-based ID cards authenticate students and staff entry. The Africa RFID Market expands into exam centers for anti-cheating measures. RFID readers monitor tagged answer booklets and distribution routes. Digital lockers with RFID logs track exam material handling. RFID enables safe storage and quick retrieval in academic archives. Labs use RFID to manage chemicals and sensitive tools. These deployments improve institutional security and efficiency.
- For instance, East Kent Hospitals NHS Trust deployed RFID to manage mattress and equipment tracking, demonstrating how RFID enhances item visibility and operational control in large institutions.
Market Challenges Analysis
Cost of Hardware, Systems Integration, and Maintenance in Low-Income Regions
High upfront costs for readers, antennas, and servers limit adoption among smaller businesses. Systems integration requires trained specialists, which remain scarce in several African markets. The Africa RFID Market faces gaps in distributor networks and local support services. Maintenance delays impact reliability and reduce user confidence. Low-cost tags often degrade in outdoor or high-temperature settings, increasing re-tagging costs. Power outages disrupt system uptime in rural and peri-urban zones. Public tenders for RFID projects often delay due to budgeting cycles. It needs stronger local ecosystems to scale.
Concerns Around Data Privacy, Misuse of Tracking, and User Awareness
Privacy concerns deter use in ID and workforce tracking programs. Citizens question continuous location tracking and unauthorized data access. The Africa RFID Market must address fears around surveillance and misuse. Data protection regulations vary across countries, creating compliance uncertainty. Public awareness about RFID functions remains low, affecting adoption willingness. Enterprises need policies to prevent internal misuse of access logs. Standardized encryption across systems is still evolving. These gaps slow RFID maturity across critical use cases.
Market Opportunities
Rising Need for Digital Identity, e-Government, and Secure Mobility Systems
Governments expand programs to issue digital IDs and secure vehicle registrations. RFID plays a key role in these national digitization strategies. The Africa RFID Market can scale through integration into e-governance frameworks. RFID enhances transparency and asset accountability in public projects. Transportation authorities implement RFID in tolling and fleet management. These use cases support multi-sector penetration.
Potential for Agricultural Cooperatives and Export-Oriented Supply Chain Upgrades
Exporters demand verified traceability in meat, coffee, cocoa, and horticulture. RFID enables product verification and quality assurance at source. It gives cooperatives tools to meet trade partner certifications. The Africa RFID Market benefits from donor-funded pilots and NGO-led digital inclusion programs. Successful models in traceability can expand into commercial agribusinesses.
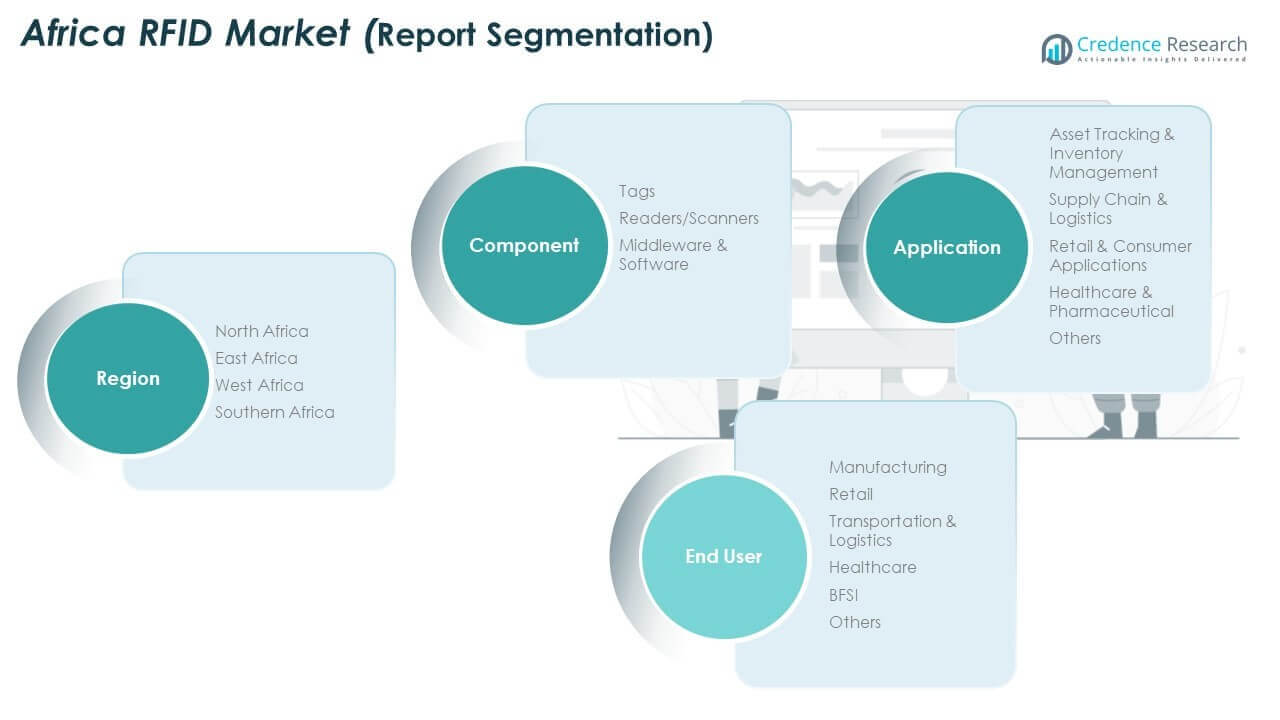
Market Segmentation Analysis
By component segment of the Africa RFID Market includes tags, readers/scanners, and middleware/software. Tags lead this segment due to their cost efficiency and broad adoption in retail, logistics, and livestock tracking. Passive tags dominate large deployments, while active tags support specialized use cases. Readers and scanners enable real-time data capture in warehouses, toll booths, and border control systems. Both fixed and handheld variants meet enterprise and field requirements. Middleware and software provide backend support, enabling data integration, automation, and analytics across industries through cloud or on-premise platforms.
- For instance, Tageos, a major RFID inlay and tag manufacturer, produces over 10 billion RFID inlays annually, supporting global retail and logistics tagging projects that improve inventory visibility and asset tracking.
By application, asset tracking and inventory management hold the largest share, with organizations using RFID to reduce losses, improve utilization, and monitor assets across logistics hubs and industrial zones. Supply chain and logistics follow closely, driven by the need for end-to-end cargo tracking, especially in ports and bonded warehouses. Retail and consumer applications include smart shelves, theft prevention systems, and contactless checkout, primarily in apparel and supermarket formats. Healthcare and pharmaceutical deployments focus on patient ID, medicine storage, and surgical tool tracking. Other niche applications span event management, education, and access control in public services.
- For instance, Walmart implemented widespread RFID tagging to achieve around a 98% inventory accuracy rate, significantly reducing stockout events and streamlining supply chain operations.
By end-user industries, manufacturing companies use RFID to track tools, materials, and work-in-progress items for process visibility. Retail remains a major user, applying RFID to enhance customer experience and prevent inventory shrinkage. The transportation and logistics sector adopts RFID to streamline fleet tracking and customs operations. Healthcare facilities use RFID to manage patients, assets, and workflows safely. The BFSI sector integrates RFID for secure access, document control, and internal audits. Other users include government agencies, educational institutions, and extractive industries, each applying RFID to improve efficiency and control.
Segmentation
By Component
- Tags
- Readers / Scanners
- Middleware & Software
By Application
- Asset Tracking & Inventory Management
- Supply Chain & Logistics
- Retail & Consumer Applications
- Healthcare & Pharmaceutical
- Others
By End User
- Manufacturing
- Retail
- Transportation & Logistics
- Healthcare
- BFSI
- Others
By Region
- Southern Africa
- East Africa
- West Africa
- North Africa
Regional Analysis
Southern Africa Leads Adoption with 36% Share Due to Strong Infrastructure and Retail Penetration
Southern Africa holds the largest market share in the Africa RFID Market at 36%. It benefits from mature logistics systems, developed retail chains, and active government projects. South Africa drives regional dominance with large-scale deployments in retail, transportation, and public services. RFID is embedded in warehouse automation, asset tracking, and tolling systems. Healthcare and pharmaceuticals use RFID to improve safety and compliance. Urban regions in Namibia and Botswana also show growing adoption in supply chains. The market in this subregion remains innovation-driven and infrastructure-ready.
North and East Africa Account for 22% and 18% Share Respectively Due to Public Sector Investments
North Africa captures 22% of the market, led by Egypt, Morocco, and Tunisia. These countries integrate RFID into identity systems, manufacturing, and government logistics. Egypt uses RFID in ports and industrial zones to improve throughput and tracking. East Africa, with 18% share, sees Kenya and Ethiopia deploying RFID in public transport, agriculture, and telecom equipment monitoring. Uganda pilots RFID in livestock traceability and national ID cards. These regions benefit from policy support and rising tech partnerships. The Africa RFID Market gains momentum from cross-border programs and donor-driven initiatives in these zones.
West and Central Africa Hold 14% and 10% Share Respectively Amid Emerging Digital Infrastructure
West Africa holds 14% of market share, with Nigeria spearheading adoption in banking, retail, and security systems. RFID is being adopted in warehouse logistics and fuel tracking. Ghana and Côte d'Ivoire invest in airport baggage handling and exam security systems. Central Africa holds a 10% share, with slower growth due to limited connectivity and high system costs. Cameroon and DRC show early-stage projects in telecom and customs automation. The Africa RFID Market in these subregions remains opportunity-rich but constrained by resource and skill gaps.
Key Player Analysis
- Zebra Technologies
- Honeywell International
- Avery Dennison
- Impinj Inc.
- Alien Technology
- Alien Technology LLC
- Nedap
- ID Solutions Africa
- NextGEN
Competitive Analysis
The Africa RFID Market features a blend of global leaders and regional specialists competing across varied application domains. Zebra Technologies and Honeywell International lead with established product portfolios in tags, readers, and integrated solutions. Avery Dennison and Impinj Inc. bring strength in UHF tags and item-level tracking solutions. These companies dominate large enterprise deployments in retail, logistics, and healthcare. Alien Technology and Nedap provide cost-optimized tags and scalable middleware for emerging use cases. Local players such as ID Solutions Africa and NextGEN focus on public sector contracts and customization for local regulatory needs. It offers competitive space for regional integrators who tailor RFID applications for government tenders, e-passport rollouts, and livestock management programs. Global firms leverage distributor networks and channel partnerships to maintain market access across fragmented geographies. Competition centers around price-performance balance, deployment scale, and software integration capabilities. RFID middleware and analytics platforms also influence vendor selection in asset-intensive industries. The Africa RFID Market remains dynamic, with players investing in product localization, low-power hardware, and maintenance support to build long-term market presence.
Recent Developments
- In October 2024, Nedap, a global leader in RFID solutions, formed a strategic partnership with Zambiti, a prominent retail technology provider in South Africa. This collaboration aims to accelerate the deployment of the iD Cloud platform across the Southern African retail market.
- In April 2024, Nexgen Packaging inaugurated its African headquarters and RFID tag production facility in Nairobi, Kenya. The new site produces RFID tags, labels, and related identification products close to regional manufacturing hubs.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for RFID will accelerate with expanding digital identity programs, smart mobility systems, and e-governance infrastructure across key African economies.
- Retail adoption will rise due to growing need for inventory accuracy, theft prevention, and contactless checkout across organized retail formats.
- Public health systems will integrate RFID into patient tracking, medicine management, and cold chain logistics to improve safety and compliance.
- Livestock and agriculture sectors will expand RFID usage to support traceability, disease control, and international trade certification.
- Logistics and port authorities will deploy RFID to optimize cargo movement, customs clearance, and bonded warehouse visibility.
- Integration of RFID with cloud, IoT, and edge platforms will enable real-time asset intelligence across rural and urban deployments.
- Local manufacturing of RFID tags and low-cost readers may gain momentum to address affordability challenges in small enterprises.
- BFSI and government institutions will scale RFID adoption for secure file tracking, access control, and high-value asset monitoring.
- Market competition will intensify with global and regional vendors focusing on localization, software integration, and lifecycle support.
- Growth in donor-backed pilot programs and regulatory support will unlock new use cases in education, mining, and energy sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Retail, E-Commerce, and Inventory Management
Organized retail, supermarkets, and e-commerce platforms in Africa are deploying RFID to improve inventory accuracy, reduce shrinkage, and enable real-time stock visibility, driving adoption across urbanizing regions.
Increased Government Adoption for Identity and Asset Programs
African governments are implementing RFID for national ID cards, vehicle registration, border control, and livestock tracking, creating foundational demand and supporting digital infrastructure initiatives.
Deployment in Livestock, Agriculture, and Traceability
RFID is being used to monitor livestock health, track herds, and ensure traceability for agricultural exports, helping meet international standards and expanding the market into rural and export-oriented sectors.
Smart Infrastructure and Logistics Automation
RFID is increasingly integrated into logistics, ports, tolling, and industrial asset management projects, enabling real-time tracking and automation that improve operational efficiency and compliance.
Declining Hardware Costs and Improved Middleware Integration
Falling prices for RFID tags and readers, along with better middleware and software integration, are making RFID solutions more accessible to enterprises, educational institutions, and public sector projects across Africa.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Africa RFID Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Africa RFID Market projected to grow between 2024 and 2032?
Which Africa RFID Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Africa RFID Market?
Who are the leading companies in the Africa RFID Market?
Which region commanded the largest share of the Africa RFID Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Manufacturing
- 1.2.2 Retail
- 1.2.3 Transportation & Logistics
- 1.2.4 Healthcare
- 1.2.5 BFSI
- 1.2.6 Others
- 1.3 By Component
- 1.3.1 Tags
- 1.3.2 Readers / Scanners
- 1.3.3 Middleware & Software
- 1.4 By Application
- 1.4.1 Asset Tracking & Inventory Management
- 1.4.2 Supply Chain & Logistics
- 1.4.3 Retail & Consumer Applications
- 1.4.4 Healthcare & Pharmaceutical
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 259.6 million → 2032: USD 416.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Africa RFID Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Africa RFID Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Africa RFID Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Africa RFID Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Africa RFID Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Africa RFID Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Africa RFID Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Africa RFID Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 259.6 million → 2032: USD 416.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Africa RFID Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Manufacturing
- 12.3.7.2 Retail
- 12.3.7.3 Transportation & Logistics
- 12.3.7.4 Healthcare
- 12.3.7.5 BFSI
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Tags
- 12.4.7.2 Readers / Scanners
- 12.4.7.3 Middleware & Software
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Asset Tracking & Inventory Management
- 12.5.7.2 Supply Chain & Logistics
- 12.5.7.3 Retail & Consumer Applications
- 12.5.7.4 Healthcare & Pharmaceutical
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Africa RFID End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Africa RFID Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Africa RFID Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Africa RFID Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Zebra Technologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International
- 18.4 Avery Dennison
- 18.5 Impinj Inc.
- 18.6 Alien Technology
- 18.7 Nedap
- 18.8 ID Solutions Africa
- 18.9 NextGEN
- 18.10 Nexgen Packaging
- 18.11 Tageos
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

