
Market Overview
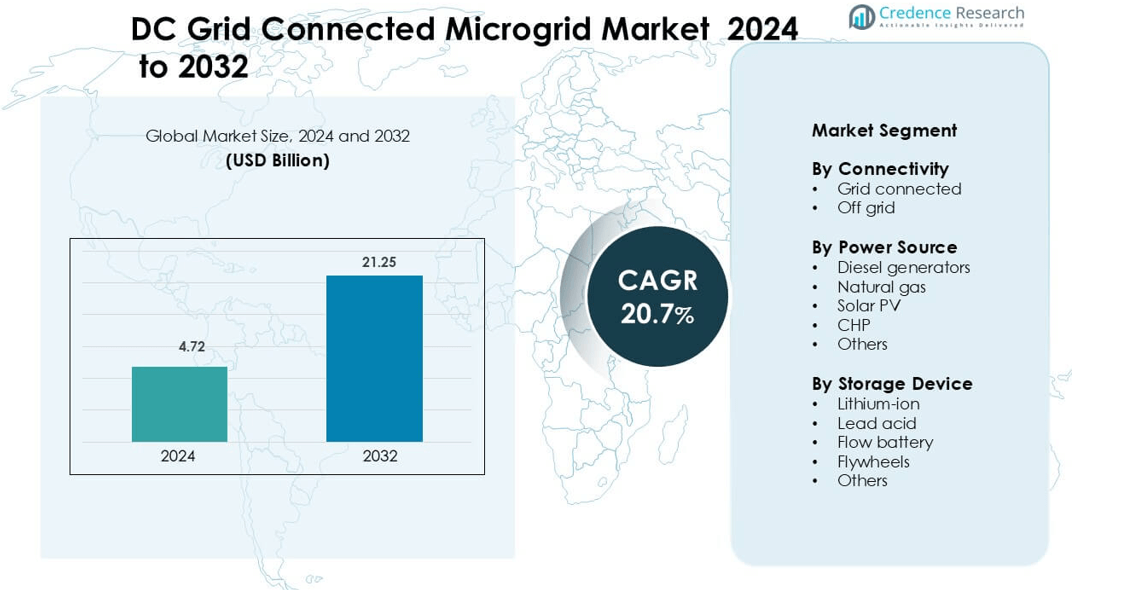
DC Grid Connected Microgrid Market was valued at USD 4.72 billion in 2024 and is anticipated to reach USD 21.25 billion by 2032, growing at a CAGR of 20.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| DC Grid Connected Microgrid Market Size 2024 | USD 4.72 billion |
| DC Grid Connected Microgrid Market, CAGR | 20.7% |
| DC Grid Connected Microgrid Market Size 2032 | USD 21.25 billion |
Key players in the DC Grid Connected Microgrid Market include Schneider Electric, ABB, Eaton Corporation, Hitachi Energy, Enel X, PowerSecure, ARDA Power, EnSync Energy Systems, AEG International, and SolarWorX. These companies compete through advanced DC converters, smart controllers, modular microgrid packages, and storage-integrated systems. Many vendors focus on hybrid renewable deployments for commercial, industrial, utility, and remote applications. North America remains the leading region with 34% market share, supported by strong investment in smart grid modernization, energy storage adoption, and EV charging infrastructure. Technology partnerships, microgrid-as-a-service models, and remote monitoring platforms strengthen competitive positioning across key markets.
Market Insights
- The DC Grid Connected Microgrid Market was valued at USD 4.72 billion in 2024 and is projected to reach USD 21.25 billion by 2032, registering a CAGR of 20.7% during the forecast period.
- Rising demand for efficient renewable integration and peak load management drives adoption, with solar PV holding the largest power source share of 41% due to falling module costs and high system efficiency.
- A key trend is the shift toward hybrid microgrids that combine solar, storage, and grid backup, along with rapid deployment across EV charging hubs, data centers, and commercial complexes.
- Competition remains strong, with companies offering modular DC solutions, microgrid-as-a-service models, advanced control software, and lithium-ion-based storage, which holds the largest segment share of 62% in storage devices.
- Regionally, North America leads with 34% market share, followed by Europe at 29% and Asia Pacific at 28%, supported by investment in smart grids, renewable targets, and expansion of commercial microgrid projects.
Market Segmentation Analysis:
By Connectivity
Grid-connected systems lead this segment with a market share of 68%. Utilities, campuses, and industrial sites prefer these systems because they support peak shaving, improve power quality, and enable energy trading. Grid-tied platforms allow operators to feed surplus power back to distribution networks, reducing operational cost. Demand rises in regions with advanced smart grid upgrades and renewable integration targets. Off-grid systems hold a smaller share and serve remote locations, island electrification, and defense facilities. This category gains traction where grid expansion is costly or unreliable, but adoption remains limited due to high deployment cost and storage dependence.
- For instance, a smaller 8.4 MW BESS system (initially announced as 6 MW+) was deployed in Wunsiedel, which became operational around February 2018. A later, much larger 100 MW / 200 MWh BESS project was inaugurated in November 2024.
By Power Source
Solar PV dominates this segment with a market share of 41%. Falling module prices, short installation timelines, and zero fuel cost make solar the preferred source in DC microgrid architecture. Commercial buildings, data centers, and community grids use DC-coupled inverters to improve efficiency and reduce conversion losses. Hybrid configurations pair solar with diesel generators or gas turbines to improve reliability during low-irradiance periods. CHP and gas-based systems follow due to stable output and suitability for industrial loads. Diesel retains use in mission-critical applications but faces regulatory pressure over emissions.
- For instance, Schneider Electric was involved in a microgrid project in Montgomery County, Maryland, that uses solar power. The project integrated a 2 MW AC solar project.
By Storage Device
Lithium-ion batteries lead this category with a market share of 62%, driven by high round-trip efficiency, long cycle life, and fast charging capability. Utilities and commercial clients deploy Li-ion banks for peak shaving, load shifting, and renewable smoothing. Cost reduction and growing manufacturing capacity further strengthen adoption. Lead-acid remains in backup and low-duty applications but shows declining preference due to shorter life. Flow batteries gain interest in long-duration storage, while flywheels offer short-burst support for frequency regulation. Emerging chemistries attract investment, yet Li-ion continues to dominate due to proven field performance and scalability.
Key Growth Drivers
Rising Integration of Renewable Energy in Power Networks
The DC grid connected microgrid market gains strong momentum from large-scale renewable integration programs. Solar, wind, and small hydro plants connect more efficiently to DC-based architectures because they avoid multiple conversion steps and reduce transmission losses. Utilities, metro stations, industrial zones, and commercial complexes prefer DC microgrids to stabilize intermittent renewable output and support peak load management. Governments launch incentive schemes for green electrification, including net-metering, feed-in tariffs, and equipment subsidies. With demand for low-emission power growing across data centers, EV charging hubs, and smart buildings, DC microgrids provide improved efficiency, faster response time, and safer load control. This advantage fuels higher adoption and long-term investment.
- For instance, Hitachi Energy has commissioned various microgrid projects globally, which incorporate solar arrays and battery storage systems to support peak load control and reduce conversion losses, and has a presence and collaborations in North Carolina
Increasing Deployment of Smart Grids and Advanced Control Systems
Smart grid modernization acts as a major catalyst for DC microgrid deployment. Real-time monitoring, energy analytics, and remotecontrol platforms help operators maintain power quality and optimize distributed generation assets. DC systems deliver faster fault isolation, improved reliability, and lower conversion losses. Industrial campuses and commercial parks use supervisory control and data acquisition (SCADA) platforms to schedule loads, store surplus energy, and trade power with distribution networks. AI-based controllers handle renewable fluctuations and support automated load balancing. These technologies improve operational stability, reduce downtime, and enhance grid resilience during storms or voltage disturbances. Investments in digital substations and smart meters further accelerate demand.
- For instance, Schneider Electric deployed its EcoStruxure Microgrid controller at a California-based logistics facility integrating a 1,000 kW solar system and a 500 kW battery bank.
Growth of Energy Storage and Demand for Peak Load Management
Energy storage expansion supports rapid growth in the DC grid connected microgrid market. Lithium-ion, flow batteries, and hybrid storage banks help operators manage peak demand, support renewable smoothing, and ensure uninterrupted power supply during outages. Businesses adopt DC microgrids to reduce dependence on diesel generators and lower operational expenses through peak shaving. The rise of EV charging, fast-charging stations, and commercial battery installations strengthens demand for scalable DC storage. Data centers and critical facilities rely on storage-backed DC grids to ensure power continuity and voltage stability. This capability makes DC microgrids a preferred solution in regions with rising power demand and high electricity tariffs.
Key Trend & Opportunity
Development of Hybrid Renewable Microgrids for Commercial and Industrial Use
A major trend is the shift toward hybrid renewable microgrids that integrate solar PV, wind turbines, battery storage, and grid backup. Commercial buildings, healthcare facilities, logistics hubs, and manufacturing units use hybrid DC microgrids to cut power cost, manage peak tariffs, and reduce emissions. Rapid adoption of AI-enabled forecasting tools improves load scheduling and renewable utilization. Vendors offer modular plug-and-play systems that support scalable expansion across campuses and utility-owned microgrid projects. The trend creates new opportunities for EPC firms, inverter manufacturers, and energy management software suppliers. With emphasis on carbon reduction and energy resilience, hybrid microgrids gain strong policy support worldwide.
- For instance, ABB delivered a hybrid microgrid in South Africa combining a 750kW solar plant, a 500 kVA diesel backup, and a lithium-ion storage system of 380 kWh.
Expansion of DC Microgrids in EV Charging and Data Center Infrastructure
Rising EV adoption creates demand for fast-charging infrastructure that benefits from DC architecture. Direct DC coupling between charging stations, solar panels, and battery storage avoids conversion losses and reduces peak load burden on the grid. Data centers also adopt DC microgrids to improve power conversion efficiency and reduce heat loss. Telecom towers, metro rail systems, and port facilities deploy DC microgrids for stable power, faster backup response, and high energy efficiency. Vendors invest in high-voltage DC switchgear, solid-state transformers, and advanced protection systems to support this expansion. These developments provide long-term growth prospects for technology suppliers and integrators.
- For instance, ABB deployed its Terra HP chargers supporting up to 350 kW at Ionity stations across Europe.
Key Challenge
High Upfront Cost and Complex Integration with Existing Grid Infrastructure
Despite strong growth drivers, high capital cost poses a major challenge for several projects. DC microgrids require advanced power electronics, protection equipment, energy management software, and storage systems, increasing initial investment. Retrofitting existing AC infrastructure with DC circuits adds complexity and requires skilled engineering support. Utilities hesitate to adopt large-scale transition strategies without proven long-term return on investment. Financing becomes difficult for smaller commercial users without government subsidy or power purchase agreements. The lack of standardization in DC voltage levels also complicates system design and component interoperability, slowing market penetration.
Scarcity of Standards, Skilled Workforce, and Protection Mechanisms
Protection and safety remain key technical challenges in the DC grid connected microgrid market. Traditional AC breakers and relays do not function effectively in DC environments, requiring specialized fast-response protection devices. Only a limited number of manufacturers supply such components, making procurement costly. The market also suffers from a shortage of engineers trained in DC system design and troubleshooting. Many regions lack regulatory frameworks covering interconnection rules, energy trading policies, and grid synchronization standards. Absence of unified guidelines slows large-scale deployment and adds risk for investors and utilities planning long-term DC infrastructure projects.
Regional Analysis
North America
North America holds a market share of 34%, driven by strong investment in renewable integration, smart grid upgrades, and commercial microgrid projects. Utilities deploy DC-connected systems for peak shaving, energy trading, and improving grid reliability during extreme weather events. Data centers, university campuses, and defense bases adopt DC microgrids to cut conversion losses and maintain uninterrupted power. Supportive regulations, tax incentives, and rising EV charging infrastructure accelerate demand. The United States leads installations, while Canada expands projects in remote and island communities. Growing industrial electrification and energy storage deployment reinforces the region’s long-term growth outlook.
Europe
Europe accounts for a market share of 29%, supported by decarbonization targets and rising dependence on distributed renewable power. Countries invest in DC microgrids for commercial buildings, transportation hubs, industrial parks, and community energy systems. The region leads in regulatory frameworks, smart meters, and grid modernization. Germany, the U.K., and the Netherlands deploy hybrid microgrids integrating solar, wind, and storage to improve energy efficiency. Expansion of EV charging networks creates additional demand for DC architecture. Opportunities also rise in ports, airports, and rail networks that seek low-loss energy distribution and faster backup response.
Asia Pacific
Asia Pacific dominates growth momentum with a market share of 28%, fueled by rising electricity demand, large-scale renewable deployment, and urban electrification. China, Japan, South Korea, and India lead adoption across commercial buildings, industrial clusters, and transportation infrastructure. Remote island and rural electrification programs accelerate microgrid projects in Southeast Asia. Governments promote battery storage, hybrid renewable systems, and green building codes, strengthening long-term adoption. Telecom, data centers, and fast-charging networks also shift toward DC platforms to improve efficiency and cut operational costs. Rapid industrialization and smart city development further expand the market.
Latin America
Latin America holds a market share of 5%, driven by demand for stable power in industrial zones, mining sites, and remote communities. Brazil, Chile, and Mexico invest in renewable-backed microgrids to reduce diesel dependence and enhance grid reliability. Solar-energy abundance makes DC configurations attractive for commercial and agricultural applications. Financial support from multilateral banks strengthens project development, while hybrid systems expand in island territories. Slow regulatory progress limits faster deployment, yet the region shows strong long-term potential with rising clean energy targets and storage adoption.
Middle East & Africa
The Middle East & Africa capture a market share of 4%. Microgrid interest grows in utility, oil and gas, and industrial facilities that demand reliable power and lower fuel costs. GCC countries deploy solar-plus-storage DC systems for commercial sites and data centers, while Africa focuses on rural electrification. Telecom towers, mining operations, and health facilities adopt microgrids to reduce generator usage. The region benefits from strong solar resources and falling storage prices. However, limited financing, technical expertise gaps, and regulatory delays slow broader adoption, though long-term prospects remain positive.
Market Segmentations
By Connectivity
- Grid connected
- Off grid
By Power Source
- Diesel generators
- Natural gas
- Solar PV
- CHP
- Others
By Storage Device
- Lithium-ion
- Lead acid
- Flow battery
- Flywheels
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the DC grid connected microgrid market features global power electronics companies, energy management specialists, and renewable integration solution providers. Firms compete on system efficiency, advanced control software, and scalable architecture for commercial, industrial, and utility projects. Major players focus on DC-optimized inverters, solid-state transformers, fast-response protection systems, and high-voltage DC distribution components. Strategic partnerships drive growth as utilities and EPC contractors collaborate on hybrid renewable microgrids backed by lithium-ion storage. Vendors also expand portfolios with modular plug-and-play systems and AI-based energy management platforms. Companies invest in microgrid-as-a-service models to reduce capital barriers and support remote deployments. Continuous product upgrades, cybersecurity features, and compatibility with EV charging networks strengthen their competitiveness. The market remains highly technology-driven, and firms that deliver higher safety, faster response, and lower operating cost secure stronger positioning across commercial, defense, data center, and smart city applications
Key Player Analysis
- EnSync Energy Systems
- PowerSecure
- ARDA Power
- SolarWorX
- Enel X
- AEG International
- ABB
- Schneider Electric
- Eaton Corporation
- Hitachi Energy
Recent Developments
- In June 2025, PowerSecure Partnered with Edged to supply resilient power systems for U.S. data centers.
- In April 2023, ARDA Power Named a finalist in the ABB Electrification Startup Challenge (Smart Power)
Report Coverage
The research report offers an in-depth analysis based on Connectivity, Power Source, Storage Device and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption will rise in commercial buildings, campuses, and data centers seeking higher efficiency.
- Hybrid renewable microgrids will expand as solar and storage deployments continue to scale.
- Utilities will deploy more DC systems for peak shaving and faster grid response.
- EV fast-charging networks will increase demand for direct DC coupling and storage.
- Lithium-ion and long-duration batteries will gain deeper integration in microgrid design.
- AI-based control platforms will improve forecasting, load management, and fault isolation.
- Developing regions will use DC microgrids for community electrification and remote sites.
- Modular plug-and-play solutions will shorten project timelines and reduce engineering costs.
- Industrial users will adopt DC microgrids to cut diesel dependence and improve resilience.
- Policy support, energy efficiency rules, and carbon targets will strengthen long-term growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for DC Grid Connected Microgrid Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is DC Grid Connected Microgrid Market projected to grow between 2025 and 2032?
Which DC Grid Connected Microgrid Market segment held the largest share in 2024?
What are the primary factors fueling the growth of DC Grid Connected Microgrid Market?
Who are the leading companies in DC Grid Connected Microgrid Market?
Which region commanded the largest share of DC Grid Connected Microgrid Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4.72 billion → 2032: USD 21.25 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global DC Grid Connected Microgrid Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global DC Grid Connected Microgrid Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global DC Grid Connected Microgrid Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global DC Grid Connected Microgrid Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global DC Grid Connected Microgrid Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global DC Grid Connected Microgrid Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global DC Grid Connected Microgrid Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global DC Grid Connected Microgrid Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4.72 billion → 2032: USD 21.25 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global DC Grid Connected Microgrid Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global DC Grid Connected Microgrid Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global DC Grid Connected Microgrid Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global DC Grid Connected Microgrid Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

