
Market Overview
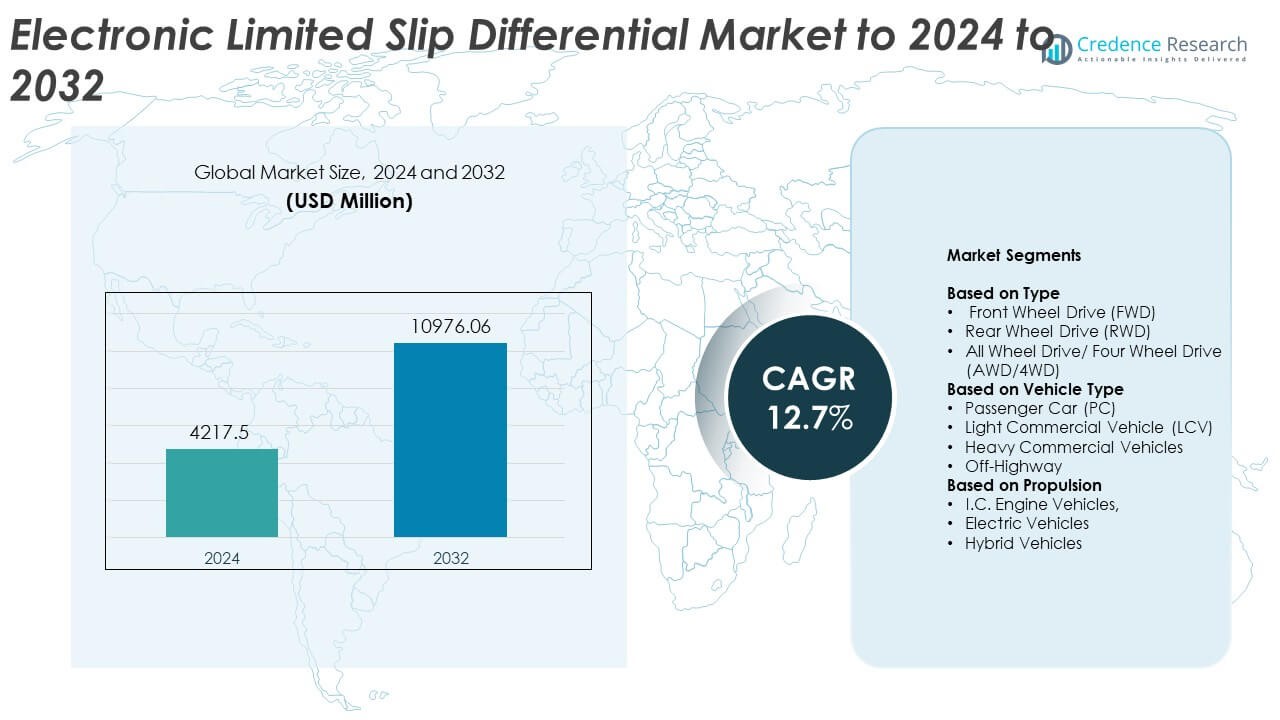
Electronic Limited Slip Differential Market size was valued at USD 4217.5 million in 2024 and is anticipated to reach USD 10976.06 million by 2032, at a CAGR of 12.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Limited Slip Differential Market Size 2024 | USD 4217.5 Million |
| Electronic Limited Slip Differential Market, CAGR | 12.7% |
| Electronic Limited Slip Differential Market Size 2032 | USD 10976.06 Million |
The Electronic Limited Slip Differential Market is shaped by major companies such as ZF Friedrichshafen AG, Linamar, JTEKT Corporation, Continental AG, American Axle & Manufacturing, GKN Automotive, BorgWarner Inc., Schaeffler India Limited, Eaton, and Dana Limited. These players compete through advancements in electronic control units, compact actuator systems, and software-driven torque management. North America leads the global market with about 37% share in 2024, supported by strong production of SUVs, pickups, and performance vehicles. Europe follows with nearly 32% share due to high adoption in premium sedans and sports cars, while Asia Pacific accounts for about 26%, driven by rising vehicle manufacturing and expanding AWD usage.
Market Insights
- Electronic Limited Slip Differential Market was valued at USD 4217.5 million in 2024 and is projected to reach USD 10976.06 million by 2032, growing at a CAGR of 12.7%. • Growth is driven by rising production of performance vehicles, expanding SUV demand, and increasing adoption of AWD systems, with AWD holding about 49% share and passenger cars leading with roughly 58% share in 2024. • Key trends include deeper integration of software-controlled driveline systems, rising EV and hybrid adoption, and growing use of lightweight differential designs in next-generation platforms. • Competition strengthens as major suppliers expand electronics, actuators, and torque-vectoring technologies to support premium and high-torque vehicle programs across global OEMs. • North America leads with around 37% share in 2024, followed by Europe at 32% and Asia Pacific at 26%, while Latin America and Middle East & Africa hold smaller shares but show steady adoption in SUV and LCV segments.
Market Segmentation Analysis:
By Type
All Wheel Drive and Four Wheel Drive systems lead this segment with about 49% share in 2024. Carmakers prefer these drivetrains because they improve traction, cornering stability, and torque distribution in challenging road conditions. Growth strengthens as premium SUVs and performance cars adopt electronic limited slip systems to support dynamic driving modes. Rising launch of AWD crossovers in Asia and Europe also pushes wider use of active differentials, especially in models that require quick electronic control for safety and handling.
- For instance, Schaeffler Group reports its electronic limited-slip differential (eLSD) units have a drive torque capacity of up to 7,000 Nm and a clutch torque capacity of a minimum of 2,500 Nm.
By Vehicle Type
Passenger Cars hold the dominant position with nearly 58% share in 2024. Demand rises as automakers integrate performance-oriented drivetrains into compact, mid-size, and luxury cars. Buyers value smoother acceleration, reduced wheel slip, and improved ride control. Adoption increases in sports sedans and premium hatchbacks launched with intelligent driveline control. Growth in SUV-based passenger vehicles further boosts the segment because many models rely on electronic limited slip systems to enhance grip and stability on mixed terrains.
- For instance, American Axle & Manufacturing (AAM) partnered to produce the TracRite electro-mechanical eLSD, aimed at high-volume passenger cars by the year 2018.
By Propulsion
I.C. Engine Vehicles dominate this segment with about 63% share in 2024. These vehicles maintain strong market presence because mechanical-electronic hybrid differential systems pair well with traditional powertrains. Carmakers install electronic limited slip mechanisms to manage rising engine outputs and to improve traction under high-torque loads. Hybrid and electric vehicles grow at a faster pace as manufacturers develop software-controlled torque vectoring systems, yet internal combustion platforms still lead due to their larger production volumes and wider global availability.
Key Growth Drivers
Rising Demand for Performance and Stability
Growing consumer interest in safer and more stable driving supports strong adoption. Automakers add electronic limited slip systems to enhance traction, cornering control, and real-time torque management. Expansion of SUVs, sports cars, and premium sedans further accelerates usage because these vehicles need advanced driveline control to handle higher power outputs. As global buyers expect better on-road stability in diverse conditions, manufacturers continue to integrate electronic differentials to meet performance expectations and strengthen vehicle handling quality.
- For instance, ZF Friedrichshafen AG unveiled a next-generation networked eLSD rear axle transmission with increased control and capability. The exact numerical lock-torque value (“up to 3 000 Nm”) is referenced.
Acceleration of AWD and Premium Vehicle Production
The surge in all-wheel-drive and premium vehicle sales drives broad adoption of electronic limited slip differentials. Carmakers install these systems to boost acceleration, improve grip, and support dynamic driving modes in high-value vehicle segments. Growth in luxury SUVs and crossovers adds further momentum as these models rely on active torque distribution to maintain stability. Increasing preference for advanced drivetrains in China, Europe, and North America widens the integration of electronically controlled differential systems.
- For instance, GKN Automotive offers modular all-wheel drive systems (ActiveConnect, torque-vectoring) that engage rear axle in less than 300 ms for performance vehicles.
Integration of Advanced Vehicle Electronics
Rapid progress in automotive electronics and software improves the appeal of electronic limited slip systems. Automakers link these differentials with traction control, ABS, and stability programs to optimize torque flow and reduce wheel slip. Enhanced sensor technology and faster control units allow smoother transitions between driving conditions. This integration raises system efficiency and offers predictable handling, motivating more OEMs to select electronic solutions over traditional mechanical units for future vehicle platforms.
Key Trends and Opportunities
Expansion of EV and Hybrid Drivetrains
Electric and hybrid vehicles create new opportunities for electronic limited slip systems. These drivetrains require advanced torque vectoring and precise traction management, making electronically controlled differentials ideal for smooth power distribution. As global EV sales rise, manufacturers invest in compact, software-driven differential units that fit integrated e-axle designs. Increasing demand for stable acceleration and improved cornering in electric SUVs and performance EVs opens strong growth potential for electronic differential technologies.
- For instance, GKN Automotive’s modular eDrive system for electric vehicles can generate up to 5 300 Nm of torque in large EV applications.
Shift Toward Software-Defined Vehicle Dynamics
Carmakers increasingly adopt software-controlled driveline systems to deliver customizable driving modes and refined handling. Electronic limited slip differentials benefit from this shift because they can adjust torque flow through real-time software updates. Advanced control algorithms help manufacturers fine-tune traction for different terrains, boosting system value in off-road and high-performance vehicles. Growing interest in adaptive, driver-selectable performance features builds new opportunities for electronically managed differential platforms.
- For instance, Schaeffler’s eLSD uses transmission oil instead of separate clutch-oil circuit and offers modular actuator arrangements (parallel and 90°) for packaging and efficiency.
Lightweight and Energy-Efficient Designs
Growing focus on efficiency encourages development of lightweight electronic differential units. Automakers explore optimized materials, compact actuators, and reduced-friction designs to improve fuel economy and extend EV driving range. These innovations offer better integration flexibility for next-generation vehicle architectures. As regulatory pressure for cleaner transport strengthens, suppliers gain opportunities to expand efficient electronic limited slip systems that support lower emissions and better driveline performance.
Key Challenges
High Cost of Integration and Components
Electronic limited slip differentials remain costlier than mechanical options due to advanced sensors, actuators, and control systems. Automakers face higher production and calibration expenses, which limit adoption in small or economy vehicles. The added cost of software development and vehicle system tuning increases total integration effort. Price sensitivity in developing markets further restricts penetration, creating barriers for firms aiming to scale electronic solutions across broader model ranges.
Complexity in Calibration and System Compatibility
These systems require precise tuning with traction control, stability programs, and powertrain electronics, adding engineering complexity. Ensuring consistent performance across varied driving conditions demands extensive testing and software refinement. Compatibility with emerging electric and hybrid platforms also raises integration challenges as manufacturers balance space constraints and thermal demands. This complexity can slow development cycles and increase technical risks, making some automakers cautious about adopting electronic limited slip technologies.
Regional Analysis
North America
North America holds about 37% share in 2024, supported by strong production of SUVs, pickup trucks, and performance-oriented passenger cars. Automakers in the United States and Canada integrate electronic limited slip systems to improve stability, traction, and torque control in high-power drivetrains. Rising demand for premium vehicles and expansion of AWD platforms strengthen market adoption. Growth also benefits from advanced automotive electronics, strong consumer preference for safety features, and steady upgrades in driveline technology across new model launches.
Europe
Europe accounts for nearly 32% share in 2024, driven by high adoption of premium sedans, sports cars, and luxury SUVs produced across Germany, the United Kingdom, and Italy. Carmakers in this region use electronic limited slip systems to meet strict safety expectations and enhance performance in both combustion and hybrid platforms. Strong engineering capabilities, rising electric vehicle output, and expansion of AWD configurations in compact crossovers increase demand. The region also benefits from advanced traction control innovations and growing interest in dynamic handling technologies.
Asia Pacific
Asia Pacific captures about 26% share in 2024, supported by rising production of passenger cars and SUVs in China, Japan, India, and South Korea. Expanding adoption of AWD and performance-oriented drivetrains in mid-range vehicles boosts demand for electronic limited slip systems. Increasing sales of electric and hybrid vehicles further contribute to growth, as these platforms require advanced torque distribution and traction support. The region’s rapid urbanization, growing disposable income, and strong investments in automotive electronics enhance overall market expansion.
Latin America
Latin America holds around 3% share in 2024, with gradual growth driven by rising interest in SUVs and light commercial vehicles in Brazil, Mexico, and Argentina. Automakers introduce electronic limited slip systems in mid- to high-end models to improve stability on variable road surfaces. Market expansion remains steady as regional consumers adopt advanced safety and driveline features. Economic recovery and increasing assembly of global vehicle platforms help reinforce demand for electronically controlled torque distribution technologies.
Middle East and Africa
Middle East and Africa represent nearly 2% share in 2024, supported by rising sales of off-road vehicles, SUVs, and pickups suited for desert and rugged terrains. Electronic limited slip systems gain traction due to their ability to enhance torque control and vehicle stability on uneven surfaces. Adoption progresses as premium and imported models integrate advanced driveline technologies. Growing interest in safety upgrades and expansion of regional dealerships offering AWD vehicles contribute to steady but moderate market development.
Market Segmentations:
By Type
- Front Wheel Drive (FWD)
- Rear Wheel Drive (RWD)
- All Wheel Drive/ Four Wheel Drive (AWD/4WD)
By Vehicle Type
- Passenger Car (PC)
- Light Commercial Vehicle (LCV)
- Heavy Commercial Vehicles
- Off-Highway
By Propulsion
- C. Engine Vehicles,
- Electric Vehicles
- Hybrid Vehicles
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Electronic Limited Slip Differential Market is shaped by leading suppliers such as ZF Friedrichshafen AG, Linamar, JTEKT Corporation, Continental AG, American Axle & Manufacturing, GKN Automotive, BorgWarner Inc., Schaeffler India Limited, Eaton, and Dana Limited. Companies focus on advanced driveline engineering, integrating faster electronic control units, improved actuator response, and refined torque management software. Many manufacturers invest in lightweight architectures to support efficiency goals in hybrid and electric platforms. Strategic partnerships with global automakers help expand technology adoption across premium SUVs, performance cars, and AWD vehicles. Suppliers also strengthen regional production capabilities to meet rising demand in Asia Pacific and North America. Continuous innovation in traction control integration, durability improvements, and system calibration tools remains central to maintaining competitiveness.
Key Player Analysis
- ZF Friedrichshafen AG (Germany)
- Linamar (Canada)
- JTEKT Corporation (Japan)
- Continental AG (Germany)
- American Axle & Manufacturing, Inc. (U.S.)
- GKN Automotive (U.K.)
- BorgWarner Inc. (U.S.)
- Schaeffler India Limited (India)
- Eaton (U.S.)
- Dana Limited (U.S.)
Recent Developments
- In 2025, ZF disclosed advancements in their next-generation electronic limited slip differential system, focusing on integration with vehicle networks for enhanced connectivity and real-time torque vectoring control.
- In 2025, GKN Automotive showcased advancements in drivetrain electrification and e-drive technologies at automotive events, emphasizing their ongoing development in electronic traction control and limited slip differential systems for electric vehicles.
- In 2024, BorgWarner secured multiple contracts to supply its electric cross differential (eXD) technology to major OEMs, including GAC Motor and other global manufacturers.
Report Coverage
The research report offers an in-depth analysis based on Type, Vehicle Type, Propulsion and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as automakers increase adoption of advanced driveline control systems.
- AWD and performance vehicle production will continue to drive strong demand.
- EV and hybrid platforms will integrate more software-based torque vectoring solutions.
- Premium SUVs will remain major adopters of electronic limited slip technologies.
- Advancements in automotive electronics will improve system response and durability.
- Lightweight differential designs will gain traction to support efficiency goals.
- More OEMs will shift from mechanical to electronic units for better stability control.
- Asia Pacific will show faster growth due to rising vehicle production.
- Collaboration between differential suppliers and EV manufacturers will increase.
- Long-term demand will rise as safety and traction standards become more stringent.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of AWD and Premium Vehicle Production
The surge in all-wheel-drive and premium vehicle sales is driving broad adoption of electronic limited slip differentials, as these systems are essential for improving acceleration, grip, and dynamic driving modes in high-value vehicle segments such as luxury SUVs and crossovers.
Integration of Advanced Vehicle Electronics
Rapid advancements in automotive electronics and software are making electronic limited slip differentials more attractive, as they can be seamlessly integrated with traction control, ABS, and stability programs to optimize torque flow and enhance vehicle handling.
Growth in Performance and Stability Requirements
Increasing consumer demand for safer, more stable driving experiences is pushing automakers to adopt electronic limited slip systems, which provide superior traction, cornering control, and real-time torque management, especially in SUVs, sports cars, and premium sedans.
Rising Adoption in EV and Hybrid Platforms
The shift toward electric and hybrid vehicles is creating new opportunities for electronic limited slip differentials, as these drivetrains require precise torque vectoring and traction management, making electronically controlled systems ideal for smooth power distribution and improved cornering in next-generation vehicles.
Focus on Lightweight and Energy-Efficient Designs
Automakers are prioritizing lightweight and energy-efficient electronic differential units to improve fuel economy and extend EV driving range, which is encouraging the adoption of optimized materials, compact actuators, and reduced-friction designs in electronic limited slip differential systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electronic Limited Slip Differential Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electronic Limited Slip Differential Market projected to grow between 2025 and 2032?
Which Electronic Limited Slip Differential Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electronic Limited Slip Differential Market?
Who are the leading companies in the Electronic Limited Slip Differential Market?
Which region commanded the largest share of the Electronic Limited Slip Differential Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Front Wheel Drive (FWD)
- 1.2.2 Rear Wheel Drive (RWD)
- 1.2.3 All Wheel Drive/Four Wheel Drive (AWD/4WD)
- 1.3 By Propulsion
- 1.3.1 I.C. Engine Vehicles
- 1.3.2 Electric Vehicles
- 1.3.3 Hybrid Vehicles
- 1.4 By Vehicle Type
- 1.4.1 Passenger Car (PC)
- 1.4.2 Light Commercial Vehicle (LCV)
- 1.4.3 Heavy Commercial Vehicles
- 1.4.4 Off-Highway
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4217.5 million → 2032: USD 10976.06 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Limited Slip Differential Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Limited Slip Differential Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Limited Slip Differential Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Limited Slip Differential Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Limited Slip Differential Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Limited Slip Differential Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Limited Slip Differential Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Limited Slip Differential Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4217.5 million → 2032: USD 10976.06 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Limited Slip Differential Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Front Wheel Drive (FWD)
- 12.3.7.2 Rear Wheel Drive (RWD)
- 12.3.7.3 All Wheel Drive/Four Wheel Drive (AWD/4WD)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Propulsion - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 I.C. Engine Vehicles
- 12.4.7.2 Electric Vehicles
- 12.4.7.3 Hybrid Vehicles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Car (PC)
- 12.5.7.2 Light Commercial Vehicle (LCV)
- 12.5.7.3 Heavy Commercial Vehicles
- 12.5.7.4 Off-Highway
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Limited Slip Differential Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electronic Limited Slip Differential Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electronic Limited Slip Differential Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 ZF Friedrichshafen AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Linamar
- 17.4 JTEKT Corporation
- 17.5 Continental AG
- 17.6 American Axle & Manufacturing
- 17.7 GKN Automotive
- 17.8 BorgWarner Inc.
- 17.9 Schaeffler India Limited
- 17.10 Eaton
- 17.11 Dana Limited
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

