
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Algae-Based Supplement Market Size 2024 | USD 2,340.3 million |
| Algae-Based Supplement Market, CAGR | 7.10% |
| Algae-Based Supplement Market Size 2032 | USD 4,051.7 million |
Market Overview
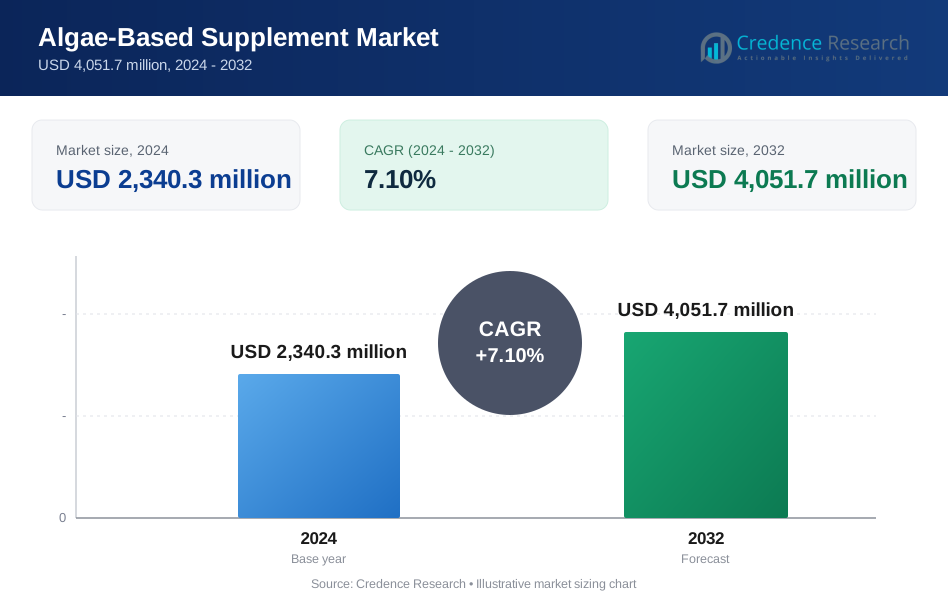
The algae-based supplement market is projected to grow from USD 2,340.3 million in 2024 to USD 4,051.7 million by 2032, registering a CAGR of 7.10% during the forecast period.
The algae-based supplement market is gaining momentum due to rising consumer awareness about plant-based and sustainable nutrition. Growing demand for natural health products rich in proteins, omega-3 fatty acids, vitamins, and antioxidants is driving adoption across dietary, sports, and functional nutrition segments. Algae-based sources like spirulina and chlorella are increasingly preferred as alternatives to fish oil, aligning with vegan and vegetarian lifestyles. The market benefits from advancements in algae cultivation technologies, including photobioreactors and open-pond systems, which enhance yield and reduce production costs. Regulatory approvals for algae-derived ingredients in food and nutraceutical applications are also supporting market expansion. Additionally, growing environmental concerns and preference for eco-friendly products are pushing manufacturers to invest in algae as a renewable resource. Strategic partnerships and investments in R&D by key players are accelerating innovation in product formulations and delivery formats, such as tablets, powders, and capsules. These trends collectively reinforce the market’s long-term growth and global expansion potential.
The algae based supplement market spans North America, Europe, Asia-Pacific, and the Rest of the World, with North America holding the largest share due to strong consumer awareness and established distribution. Europe follows, driven by clean-label trends and regulatory support. Asia-Pacific emerges as the fastest-growing region, supported by rising health consciousness and traditional use of algae in diets. The Rest of the World, including Latin America, the Middle East, and Africa, shows growing potential with expanding urban demand. Key players operating across these regions include Cyanotech Corporation, DIC Corporation, Koninklijke DSM N.V., Fuqing King Dnarmsa Spirulina Co. Ltd., TerraVia Holdings Inc., Nutress B.V., Doctor’s Best, Pharmavite LLC, and Chlorella Supply Co. Ltd. These companies compete through innovation, sustainable sourcing, regional partnerships, and product diversification to strengthen their global presence and address varied consumer needs.
Market Insights
- The algae based supplement market is projected to grow from USD 2,340.3 million in 2024 to USD 4,051.7 million by 2032, at a CAGR of 7.10%.
- Rising demand for plant-based, sustainable nutrition is driving the market, with algae offering a natural source of proteins, omega-3s, and antioxidants.
- Technological advancements in cultivation systems and extraction processes are improving production efficiency and reducing costs.
- Health applications of algae supplements are expanding into cardiovascular, immune, cognitive, and sports nutrition segments.
- Regulatory approvals and public-private investments are accelerating product development, commercialization, and global market entry.
- High production costs, scalability issues, and inconsistent regulations remain key challenges, especially in emerging markets.
- North America leads with 35% market share, followed by Europe (28%), Asia-Pacific (22%), and Rest of the World (15%), with rapid growth seen in Asia-Pacific.
Market Drivers
Rising Demand for Plant-Based and Sustainable Nutrition
The algae based supplement market is being driven by the global shift toward plant-based diets and environmentally conscious consumer behavior. Consumers are actively seeking alternatives to animal-derived supplements, especially for omega-3 and protein intake. Algae provide a sustainable and renewable source of essential nutrients without contributing to overfishing or environmental degradation. This aligns with rising ethical and ecological concerns. The growing vegan and vegetarian population is accelerating this transition. Brands are leveraging this demand to introduce cleaner-label products. It is reinforcing algae’s position as a preferred ingredient in the health and wellness sector.
Advancements in Cultivation and Processing Technologies
Technological progress in algae cultivation, including closed-loop photobioreactors and open-pond systems, is boosting supply efficiency and quality control. These innovations allow year-round production with reduced land and water use, enhancing sustainability and cost-effectiveness. The algae based supplement market benefits significantly from such advancements, enabling scalability and consistent nutrient profiles. Enhanced extraction techniques now ensure higher purity and bioavailability of key compounds like astaxanthin and chlorophyll. It supports innovation in product formulation. This progress is making algae supplements more commercially viable and nutritionally competitive.
- For instance, Cyanotech Corporation in Hawaii, which operates large-scale open-pond systems for natural astaxanthin production, employing advanced extraction techniques to achieve high purity and bioavailability in its BioAstin® supplement.
Health Benefits and Expanding Nutritional Applications
Algae are rich in essential nutrients such as omega-3 fatty acids, proteins, antioxidants, vitamins, and minerals. These health benefits are attracting both consumers and medical professionals across age groups. The algae based supplement market is seeing increased application in areas like cardiovascular health, immune support, cognitive performance, and sports nutrition. Scientific studies validating algae’s efficacy are influencing purchasing decisions. It is creating trust and credibility among users. Consumer interest in preventive health and clean-label supplements is fueling ongoing demand.
- For instance, Spirulina, a blue-green algae produced by companies like Earthrise Nutritionals, has been clinically shown to improve blood lipid profiles and reduce inflammation in multiple randomized controlled trials, with daily supplementation of 2–4 grams leading to significant reductions in total cholesterol, LDL, and triglycerides in at-risk populations.
Regulatory Support and Industry Investment
Governments and regulatory bodies are approving algae-derived ingredients for use in food and dietary supplements, creating a favorable framework for market growth. This is encouraging startups and established companies to expand production and product development efforts. The algae based supplement market is witnessing increased investment in R&D and infrastructure by key players. Public-private collaborations are also emerging to support algae cultivation at scale. It strengthens the supply chain and product innovation. Regulatory clarity is reducing entry barriers and accelerating commercialization.
Market Trends
Increasing Integration of Algae in Functional and Sports Nutrition
The algae based supplement market is experiencing strong growth from its integration into functional and sports nutrition products. Brands are incorporating algae-derived ingredients like spirulina, chlorella, and astaxanthin into protein powders, recovery formulas, and endurance boosters. These ingredients offer high bioavailability of nutrients essential for muscle recovery, stamina, and immune support. It supports consumer demand for clean-label, plant-based performance products. Athletes and health-conscious users are adopting algae-based supplements for their antioxidant and anti-inflammatory properties. This trend is expanding product formats and widening the consumer base.
- For instance, Algenuity, a UK-based company specializing in microalgae, which has developed Chlorella and Spirulina strains specifically tailored for high-protein sports drinks and nutricosmetic products, leveraging their rich content of omega-3s, vitamins, and trace elements.
Rising Demand for Algae-Based Omega-3 Alternatives
Consumers are increasingly choosing algae-based omega-3 supplements over traditional fish oil due to concerns about sustainability, ocean pollution, and dietary preferences. The algae based supplement market is responding with innovative formulations offering DHA and EPA directly from microalgae sources. These supplements meet the nutritional needs of vegans and vegetarians without compromising quality. It also eliminates the risk of heavy metal contamination often associated with fish-based products. Companies are launching algae oil capsules and liquids in various dosage forms. This demand shift is helping algae gain a competitive edge in the omega-3 category.
- For instance, Truvani’s Plant-Based Omega capsules provide 500 mg of DHA per serving sourced exclusively from algal oil, are certified vegan and gluten-free, and undergo third-party testing for heavy metals and contaminants to ensure purity and safety.
Expansion of Algae-Derived Products Across Delivery Formats
The algae based supplement market is diversifying rapidly across multiple delivery formats, including powders, capsules, soft gels, functional beverages, and gummies. Consumers prefer convenient, tasty, and easy-to-consume supplements that fit into their daily routines. Algae’s adaptability makes it suitable for various applications, including ready-to-drink formulations and fortified foods. It offers formulators flexibility to meet different demographic needs. Innovations in flavor masking and encapsulation are improving product palatability. This broad format availability is supporting market penetration across diverse consumer segments and global regions.
R&D-Driven Innovation and Premium Positioning of Algae Supplements
Research and development are driving the premium positioning of algae supplements with clinically validated benefits and higher potency. The algae based supplement market is seeing significant investments in developing high-purity extracts, bioactive compounds, and personalized nutrition solutions. It is allowing companies to market algae-based products as science-backed, high-value offerings. The rise in health diagnostics and wearable tech is also encouraging demand for targeted algae-based nutrition. Brands are aligning their R&D pipelines to meet these evolving needs. This innovation-focused trend is setting new benchmarks in supplement quality and effectiveness.
Market Challenges Analysis
High Production Costs and Scalability Constraints
The algae based supplement market faces significant cost-related challenges due to the capital-intensive nature of algae cultivation and processing. Setting up photobioreactors or maintaining controlled open-pond systems requires substantial investment in infrastructure, energy, and monitoring. This raises the price of end products, making them less competitive compared to synthetic or plant-based alternatives. It also limits accessibility in price-sensitive markets. Scalability remains a hurdle, especially for smaller manufacturers aiming to meet rising demand while maintaining quality and yield. These challenges slow down mass adoption and global distribution.
Limited Consumer Awareness and Regulatory Complexity
Despite its nutritional benefits, algae-based supplementation still suffers from limited consumer awareness in several developing markets. The algae based supplement market also encounters hurdles related to inconsistent regulatory frameworks across regions. Approval processes, labeling requirements, and health claims vary widely, complicating product launches and market entry. It delays commercialization and increases compliance costs. Misconceptions about algae being only for niche health users further restrict consumer uptake. This knowledge gap impacts demand and undermines efforts to position algae as a mainstream supplement option.
Market Opportunities
Rising Demand for Sustainable and Clean-Label Products
The algae based supplement market holds strong potential amid growing demand for sustainable and clean-label nutrition. Consumers are actively seeking natural, minimally processed supplements that align with ethical and environmental values. Algae, being renewable and resource-efficient, fits well into this shift. It enables brands to highlight eco-conscious sourcing and plant-based formulations. The rise of flexitarian and vegan diets globally is creating new spaces for algae integration in mainstream health products. Companies that emphasize transparency and traceability can gain a competitive edge in this evolving market.
Untapped Potential in Emerging and Functional Nutrition Markets
Expanding health consciousness in emerging economies presents significant growth opportunities for the algae based supplement market. Rising disposable income and better access to wellness products are shifting consumption patterns in Asia-Pacific, Latin America, and the Middle East. It opens doors for algae-based products across functional beverages, fortified foods, and children’s nutrition. Personalized nutrition and gut health are also fast-growing niches that algae can serve with its bioactive compounds. Targeted marketing and localized product development can help brands establish a strong presence in these untapped segments.
Market Segmentation Analysis:
By Algae Type
The algae based supplement market is segmented into spirulina, chlorella, dunaliella, and other types. Spirulina holds the largest share due to its high protein content, antioxidant properties, and widespread availability. Chlorella is gaining traction for its detoxification benefits and rich chlorophyll content. Dunaliella, known for its beta-carotene levels, is increasingly used in vision and skin health supplements. Other algae types, including blue-green algae and red algae, are emerging for specialized health functions. It reflects growing diversification in product formulations.
- For instance, Chlorella is increasingly popular for detoxification and its chlorophyll content, with companies like Nutrex Hawaii launching flavored chlorella powder to appeal to health-conscious consumers.
By Consumer Orientation
Based on consumer orientation, the algae based supplement market is segmented into men, women, kids, and unisex categories. Unisex supplements dominate the market due to their broad appeal and ease of marketing. Targeted formulations for men focus on energy, muscle support, and heart health, while those for women emphasize skin health, hormonal balance, and bone strength. Kid-specific supplements use algae for immune support and cognitive development. It enables brands to cater to distinct nutritional needs across age and gender groups.
By Nature
The market is divided into organic and conventional algae supplements. Organic products are gaining popularity due to clean-label trends and rising awareness about pesticide-free cultivation. Consumers prefer certified organic supplements for perceived safety and environmental benefits. Conventional products remain relevant due to cost efficiency and broader availability. The algae based supplement market sees rising demand for organic offerings, especially in developed regions, pushing brands to expand their certified organic product lines.
- For instance, By Nature offers a USDA-certified organic spirulina powder, marketed as a source of plant-based protein and essential nutrients, appealing to health-conscious consumers seeking transparent sourcing.
Segments:
Based on Composition
- Microalgae
- β-carotene
- Vitamins C, A, E, H, B1, B2, B6, & B12
- Astaxanthin
- Polysaccharides
- Polyunsaturated Fatty Acids
- Macroalgae
- Proteins
- Furanone
- Polyunsaturated Fatty Acids
- L-α kainic Acid
- Phenotics
- Pigments
- Phlorotannins
- Phycocolloids (Carrageenan and Agar)
- Minerals
Based on Algae Type
- Spirulina
- Chlorella
- Dunaliella
- Other Types
Based on Consumer Orientation
- Men
- Kids
- Women
- Unisex
Based on Nature
- Organic
- Conventional
Based on Sales Channel
- Drug Stores
- Health & Beauty Stores
- Modern Trade Channels
- Direct Selling
- Online Retailers
- Other Retail Formats
Based on Form
- Soft Gel
- Capsules
- Liquid
- Tablets
- Powder & Granules
Based on Function
- General Well-Being
- Weight Management
- Immune & Digestive Health
- Bone & Joint Health
- Heart Health
- Eye Health
- Other Indications
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America leads the algae based supplement market with a market share of 35%. The region benefits from high consumer awareness of plant-based nutrition, strong demand for dietary supplements, and well-established distribution networks. Regulatory clarity and a growing vegan population have accelerated the adoption of algae-derived omega-3 and protein supplements. It supports innovation in delivery formats such as capsules, powders, and gummies. The United States remains the largest contributor, driven by product diversification and aggressive marketing by leading brands. Canada is also witnessing rising adoption, particularly in the organic supplement segment.
Europe
Europe accounts for 28% of the algae based supplement market, supported by growing preference for clean-label, sustainable, and plant-based nutrition. The region’s strict environmental regulations and proactive labeling standards have encouraged the adoption of algae-sourced products. Countries like Germany, the UK, and France show high demand, particularly in sports nutrition and preventive health applications. It is also influenced by strong R&D and innovation capabilities within the European nutraceutical industry. The organic segment performs strongly due to widespread awareness of sustainable agriculture. Retail and online platforms have played a key role in expanding access to algae supplements.
Asia-Pacific
Asia-Pacific holds 22% of the algae based supplement market and is the fastest-growing region. Rising disposable income, urbanization, and growing health consciousness are driving demand in countries like China, India, Japan, and South Korea. Traditional dietary practices in the region already include algae, supporting easy market integration. It creates opportunities for localized product innovation and functional beverage applications. Government initiatives promoting plant-based alternatives also contribute to market growth. Expansion of e-commerce and functional food trends further accelerates regional penetration.
Rest of the World
The Rest of the World region, which includes Latin America, the Middle East, and Africa, accounts for 15% of the algae based supplement market. Consumer awareness is gradually increasing, and urban middle-class populations are becoming key targets. It offers growth potential for affordable, nutrient-dense algae products.
Key Player Analysis
- Doctor's Best
- Taau Australia Pty Ltd.
- Chlorella Supply Co. Ltd.
- Algae Health Science
- Fuqing King Dnarmsa Spirulina Co. Ltd.
- Nutress B.V.
- TerraVia Holdings Inc.
- Holistic Herbal Solutions LLC
- Vitamin Discount Center
- Pharmavite LLC
- DIC Corporation
- Herbal Terra LLC
- Now Foods
- Kent BioEnergy Corporation
- Cyanotech Corporation
- Koninklijke DSM N.V.
Competitive Analysis
The algae based supplement market features a mix of established nutraceutical companies and specialized algae producers competing on innovation, quality, and sustainability. Key players such as Cyanotech Corporation, DIC Corporation, Koninklijke DSM N.V., and TerraVia Holdings Inc. focus on product differentiation through advanced cultivation techniques, high nutrient density, and clean-label formulations. It remains highly dynamic, with companies expanding their product lines across multiple delivery formats and targeting diverse consumer groups. Strategic partnerships, certifications, and geographic expansion play a vital role in competitive positioning. Players like Fuqing King Dnarmsa Spirulina Co. Ltd. and Nutress B.V. emphasize large-scale production capacity, while brands such as Doctor’s Best and Pharmavite LLC leverage strong retail and online presence. Innovation in omega-3 extraction and personalized nutrition is intensifying competition. Companies that invest in R&D, sustainable sourcing, and consumer education maintain a competitive edge in this fast-evolving market environment.
Recent Developments
- In May 2025, Aker BioMarine unveiled Revervia, a plant-based DHA ingredient from algae, along with its PL+ bioavailability platform, at the Vitafoods Europe event.
- In December 2024, Nature’s Bounty launched a vegetarian omega-3 supplement using algae oil, enhancing its sustainable nutrition range.
- In May 2024, Algine Plus introduced its algae-based dietary supplements on Walmart, including Ocean Greens, Astaxanthin, and Phosphatidylserine, to broaden consumer access.
- In April 2023, MiAlgae launched NaturAlgae, an omega-3 algae-based product designed for use in pet and aquaculture feed.
- In January 2023, Kemin Industries rolled out BetaVia Complete, an algae-based beta-glucan product formulated for immune health, applicable in supplements and functional foods.
Market Concentration & Characteristics
The algae based supplement market exhibits moderate to high market concentration, with a mix of global nutraceutical leaders and specialized algae producers shaping the competitive landscape. It is characterized by strong emphasis on sustainability, clean-label formulations, and nutritional innovation. Key players maintain competitive advantage through proprietary cultivation technologies, organic certifications, and extensive distribution networks. The market favors companies that invest in R&D and scale-efficient production models. Demand patterns are influenced by evolving consumer preferences for plant-based alternatives and transparent sourcing. It shows high product differentiation across formats such as powders, capsules, tablets, and functional beverages. Consumer trust, branding, and regulatory compliance play a central role in market positioning. Partnerships, mergers, and strategic alliances are frequent, aimed at expanding product portfolios and regional presence. The algae based supplement market is evolving rapidly, driven by health trends, environmental awareness, and ongoing advancements in algae processing and bioavailability enhancement.
Report Coverage
The research report offers an in-depth analysis based on Composition, Algae Type, Consumer Orientation, Naure, Sales Channel, Form, Function and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for algae-based supplements will grow as consumers continue to shift toward plant-based and sustainable nutrition.
- Algae will gain wider use in personalized health products targeting immunity, cognition, and cardiovascular wellness.
- Advancements in algae cultivation and processing will improve product quality and reduce manufacturing costs.
- Organic and clean-label algae supplements will see increased preference in both developed and emerging markets.
- Algae-based omega-3 products will replace traditional fish oil in many consumer segments.
- Regulatory support across more regions will encourage product approvals and market expansion.
- Companies will invest more in research to unlock new algae strains with enhanced nutritional benefits.
- E-commerce and direct-to-consumer channels will play a key role in expanding global product reach.
- Functional foods and beverages fortified with algae extracts will diversify supplement applications.
- Strategic collaborations and acquisitions will shape competitive dynamics and drive innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Algae based supplement market?
What are the key segments within the Algae based supplement market?
What are some challenges faced by the Algae based supplement market?
Who are the major players in the Algae based supplement market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Algae-Based Supplement Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Algae-Based Supplement Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,340.3 million → 2032: USD 4,051.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Algae-Based Supplement Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Algae-Based Supplement Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Algae-Based Supplement Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Algae-Based Supplement Market Drivers
- 3.3 Algae-Based Supplement Market Restraints & Challenges
- 3.4 Algae-Based Supplement Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Algae-Based Supplement Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Algae-Based Supplement Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Algae-Based Supplement category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Algae-Based Supplement Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Algae-Based Supplement Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Algae-Based Supplement market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Algae-Based Supplement Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Algae-Based Supplement Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Algae-Based Supplement Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Algae-Based Supplement (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Algae-Based Supplement Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Algae-Based Supplement Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Algae-Based Supplement Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Algae-Based Supplement Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Algae-Based Supplement Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Algae-Based Supplement Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Algae-Based Supplement Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Algae-Based Supplement Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Algae-Based Supplement Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
