
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Amphoteric Surfactants Market Size 2024 | USD 5,805.81 million |
| Amphoteric Surfactants Market, CAGR | 3.94% |
| Amphoteric Surfactants Market Size 2032 | USD 7,909.1 million |
Market Overview
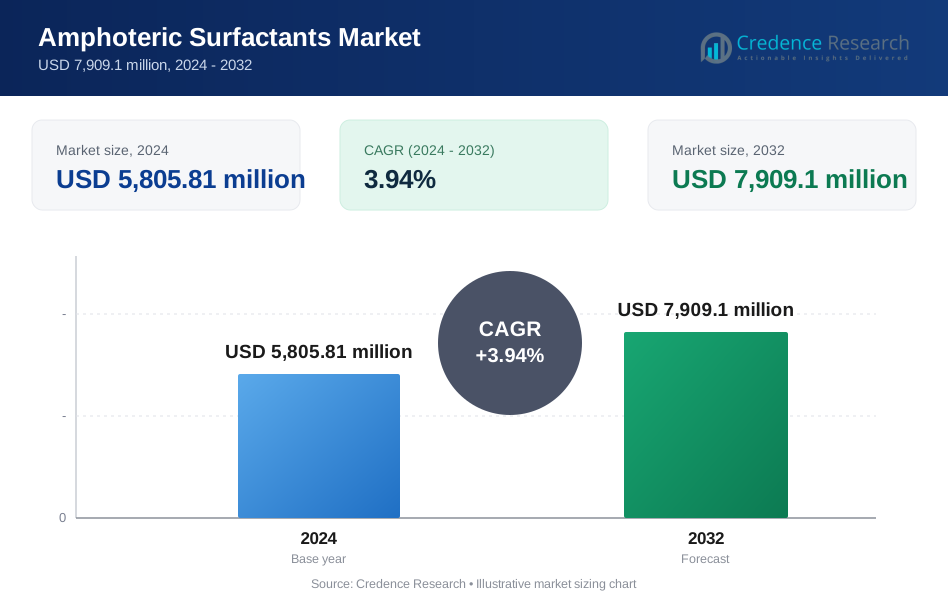
The Amphoteric Surfactants Market is projected to grow from USD 5,805.81 million in 2024 to USD 7,909.1 million by 2032, registering a compound annual growth rate (CAGR) of 3.94% during the forecast period.
The Amphoteric Surfactants Market is witnessing steady growth driven by increasing demand for mild and skin-friendly ingredients in personal care and household cleaning products. As consumers become more conscious of product safety and skin compatibility, amphoteric surfactants-known for their low irritation potential and excellent foaming properties-are gaining preference. The rising popularity of sulfate-free and pH-balanced formulations is further boosting adoption across shampoos, facial cleansers, and baby care items. In addition, the growing awareness of environmental sustainability is encouraging manufacturers to develop biodegradable and plant-based surfactant alternatives. Expanding applications in industrial cleaning, agrochemicals, and oilfield chemicals also contribute to market expansion. Key industry players are investing in R&D to enhance performance attributes while aligning with regulatory standards and eco-certifications. The shift toward multifunctional ingredients that offer both cleansing and conditioning benefits is another notable trend shaping product innovation. Rapid urbanization and improved living standards, especially in emerging economies, are also supporting long-term demand growth.
The Amphoteric Surfactants Market shows strong geographical diversity, with Asia-Pacific leading at 34% market share due to rising demand from India, China, and Southeast Asia. North America holds 28%, driven by consumer preference for mild and eco-friendly products. Europe accounts for 26%, supported by strict environmental regulations and a focus on sustainable formulations. The Rest of the World, including Latin America, the Middle East, and Africa, contributes 12%, with growing adoption in personal and institutional care. Key players shaping the competitive landscape include BASF, Croda International, Clariant, Evonik Industries AG, DuPont, Dow, Akzo Nobel, Nouryon, The Lubrizol, Stepan, ADEKA CORPORATION, and Galaxy Surfactants. These companies invest in R&D, sustainability, and regional expansion to meet evolving market needs. The market continues to grow through innovation and strategic positioning across diverse global regions.
Market Insights
- The Amphoteric Surfactants Market is expected to grow from USD 5,805.81 million in 2024 to USD 7,909.1 million by 2032, at a CAGR of 3.94%.
- Demand for mild, skin-compatible ingredients in personal care and home care is driving the market, with a shift toward sulfate-free and pH-balanced formulations.
- Expanding use in industrial and institutional cleaning due to foaming, emulsifying, and dispersing capabilities is strengthening market reach.
- Sustainability pressures and regulatory standards are pushing the adoption of biodegradable, plant-based surfactants and eco-labeled formulations.
- Asia-Pacific leads with 34% market share, followed by North America (28%), Europe (26%), and the Rest of the World (12%), reflecting strong regional diversification.
- Key players such as BASF, Croda, Clariant, Evonik, Dow, and Galaxy Surfactants are focusing on R&D, sustainable innovation, and regional expansion.
- Market faces challenges from fluctuating raw material costs and complex regulatory compliance, which impact pricing strategies and profit margins.
Market Drivers
Rising Demand for Mild and Skin-Compatible Formulations
The Amphoteric Surfactants Market is benefiting from increasing consumer awareness about product safety and dermatological compatibility. Amphoteric surfactants offer mild cleansing properties, making them ideal for sensitive skin and baby care products. This characteristic is driving their inclusion in a wide range of personal care items such as shampoos, facial cleansers, and body washes. Consumers now prioritize sulfate-free and low-irritant solutions, creating sustained demand. The shift toward health-conscious lifestyles further reinforces this trend. It supports innovation in skin-friendly product development and formulation customization.
- For instance, Stepan Company produces the AMPHOSOL® line of amphoteric surfactants, recognized for their mildness, biodegradability, and suitability for personal care products like baby shampoos and gentle cleansers.
Expansion of Home and Industrial Cleaning Applications
The Amphoteric Surfactants Market is expanding with the rising demand for effective and eco-friendly cleaning agents across residential and industrial sectors. Amphoteric surfactants exhibit excellent foaming, emulsifying, and dispersing properties, making them suitable for a broad spectrum of cleaning formulations. Their compatibility with hard water and ability to maintain performance in various pH conditions enhance their utility in industrial applications. Growth in hygiene awareness and stricter cleaning standards are increasing product usage. It also finds growing use in disinfectants and sanitizing agents. These surfactants support efficient and safe cleaning practices.
- For instance, Ampholak 7TX/C from Amphoterics International Limited is widely used in hard surface cleaners and liquid detergents, often formulated at up to 40% active amphoteric surfactant, providing improved detergency and antimicrobial action without irritation to skin or eyes.
Sustainability and Regulatory Compliance Driving Adoption
The Amphoteric Surfactants Market is increasingly shaped by environmental and regulatory pressures favoring sustainable ingredients. Amphoteric surfactants derived from renewable sources offer a lower environmental footprint and comply with global safety standards. Regulatory bodies are urging manufacturers to eliminate harmful substances and adopt biodegradable alternatives. This shift boosts the adoption of naturally sourced surfactants in various end-use sectors. It encourages investment in green chemistry and cleaner production technologies. Companies are responding by reformulating products to meet eco-label certifications and consumer expectations.
Emerging Markets and Urbanization Fueling Consumption
The Amphoteric Surfactants Market is gaining traction in emerging economies due to urbanization, rising disposable income, and improved hygiene awareness. Expanding middle-class populations are fueling demand for personal care and home hygiene products. Increased penetration of organized retail and e-commerce channels is further enhancing product accessibility. It benefits from the growing presence of multinational brands and localized manufacturing. Government initiatives promoting health and sanitation contribute to rising consumption. Market players are targeting these regions with tailored products and pricing strategies.
Market Trends
Shift Toward Sulfate-Free and Clean Label Products
The Amphoteric Surfactants Market is aligning with the global shift toward sulfate-free, paraben-free, and clean-label formulations. Consumers are increasingly seeking transparency in ingredients and favoring products that are gentle, biodegradable, and ethically sourced. Amphoteric surfactants, known for their mildness and skin compatibility, are widely used in natural and organic personal care items. Brands are promoting these ingredients in marketing to appeal to health-conscious buyers. It plays a key role in replacing harsher surfactants while maintaining cleansing efficiency. Demand is expected to rise as wellness-centric consumption patterns intensify.
- For instance, Colonial Chemical has optimized sulfate-free surfactant blends using ingredients like sodium lauroyl sarcosinate and sodium cocoyl glutamate, specifically chosen for their low irritation and high biobased content, supporting the shift toward gentler, more sustainable personal care solutions.
Rise of Multifunctional and Hybrid Formulations
The Amphoteric Surfactants Market is experiencing strong demand for multifunctional ingredients that simplify formulations while enhancing performance. Amphoteric surfactants deliver both cleansing and conditioning effects, reducing the need for multiple additives. This trend is especially prominent in personal care products like 2-in-1 shampoos, facial cleansers, and liquid soaps. It allows manufacturers to optimize production costs and reduce environmental impact. Consumer preferences are leaning toward simpler, more effective solutions. This encourages innovation in hybrid product development across home care and cosmetics.
- For instance, Myristamine Oxide (AMMONYX® MCO), also from Stepan, functions as a surfactant, emulsifier, conditioner, and viscosity modifier in 2-in-1 shampoos and automatic dishwashing detergents.
Integration into Industrial and Institutional Cleaners
The Amphoteric Surfactants Market is witnessing growing use in industrial and institutional cleaning applications. Their high compatibility with other surfactant types and excellent performance in both acidic and alkaline environments make them ideal for formulations used in hospitals, food processing, and manufacturing. It helps achieve effective cleaning while meeting safety and compliance requirements. Demand for surface sanitizers and disinfectants has surged across public spaces. The ability of these surfactants to minimize residue and reduce toxicity supports their growing market footprint. Their adoption aligns with industry-wide emphasis on health and hygiene.
Focus on Sustainable and Bio-Based Product Development
The Amphoteric Surfactants Market is seeing strong momentum in the development of bio-based and sustainable surfactants. Leading manufacturers are investing in renewable raw materials, such as coconut oil and plant-based feedstocks, to meet regulatory and consumer expectations. It supports cleaner formulations and reduced carbon footprints across product life cycles. Certifications such as COSMOS, ECOCERT, and USDA Organic are shaping new product development. Brands are incorporating these surfactants into premium and eco-friendly product lines. This trend is reinforcing environmental responsibility across the value chain.
Market Challenges Analysis
Fluctuating Raw Material Prices and Supply Chain Disruptions
The Amphoteric Surfactants Market faces challenges from fluctuating raw material prices, particularly those derived from petrochemical and plant-based sources. Variability in crude oil prices and agricultural output impacts production costs and profit margins. It must also navigate global supply chain disruptions, which affect the availability of essential ingredients and delay manufacturing cycles. Geopolitical tensions, trade restrictions, and logistical constraints continue to complicate sourcing strategies. These issues make long-term planning and inventory management more complex. Manufacturers must build resilient supply networks to mitigate these risks.
- For instance, Dow, in collaboration with LanzaTech, launched a novel biodegradable surfactant for the home care sector, leveraging innovative biotechnology to reduce dependency on traditional petrochemical feedstocks.
High Production Costs and Regulatory Pressures
The Amphoteric Surfactants Market must contend with high production and formulation costs, especially for bio-based and specialty-grade surfactants. Meeting stringent regulatory standards on safety, environmental impact, and biodegradability adds to operational complexity. It also faces challenges from the increasing demand for certifications such as REACH, ECOCERT, and COSMOS, which require costly testing and compliance processes. Smaller manufacturers often struggle to keep pace with these requirements. Competitive pricing pressures further limit the ability to pass increased costs to end users. Sustaining profitability while maintaining compliance remains a key hurdle.
Market Opportunities
Expansion in Emerging Economies and Rising Hygiene Awareness
The Amphoteric Surfactants Market holds significant growth potential in emerging economies driven by urbanization, rising disposable incomes, and improving hygiene standards. Consumers in Asia-Pacific, Latin America, and Africa are increasingly investing in personal care and home hygiene products. It can capitalize on this trend by expanding localized production and distribution networks. Government-led sanitation and health awareness campaigns are further increasing product penetration. Growing demand for affordable, mild, and safe formulations provides a strategic opportunity for new product launches. Companies that tailor offerings to regional preferences will gain a competitive edge.
Innovation in Green Chemistry and Sustainable Formulations
The Amphoteric Surfactants Market can seize growth opportunities by advancing bio-based and sustainable product development. Consumers and regulators are demanding eco-friendly alternatives that deliver performance without compromising safety. It benefits from ongoing R&D in renewable raw materials and low-impact manufacturing processes. There is rising interest in multifunctional surfactants that reduce additive load and support cleaner labels. Collaborations with biotech firms and raw material suppliers can accelerate innovation. Brands that align with green chemistry principles will enhance market relevance and brand loyalty.
Market Segmentation Analysis:
By Type
The Amphoteric Surfactants Market features diverse product types, each tailored to specific performance needs. Betaine leads the segment due to its excellent mildness and compatibility in personal care and home care formulations. Amine oxide and sultaines follow, driven by their strong foaming and cleaning properties in hard surface cleaners and dishwashing liquids. Amphoacetates and amphopropionates offer low irritation potential, supporting their use in sensitive-skin applications. Substituted imidazolines find niche applications in industrial and oilfield formulations. It benefits from this wide product mix that enables customization across industries.
- For instance, Procter & Gamble utilizes cocamidopropyl betaine in its Head & Shoulders shampoo line, leveraging its gentle cleansing and foam-boosting properties for sensitive scalps.
By Function
In terms of function, the Amphoteric Surfactants Market is dominated by detergency and foaming agent segments. These functions are critical for cleaning performance in both home care and industrial applications. Emulsifiers are gaining traction in personal care products that demand stability and a smooth texture. Wetting agents support niche uses in agriculture and textile processing. It sees continued demand for multifunctional surfactants that can fulfill multiple performance roles within a single formulation. This trend helps optimize costs and simplifies product development.
- For instance, Sanyo Chemical’s BEAULIGHT™ LCA-30D is formulated to deliver moderate detergency and produce a large amount of foam even under acidic conditions, making it suitable for use in shampoos and body washes that require gentle cleansing and robust lather.
By Application
The Amphoteric Surfactants Market finds its primary application in personal care, followed by home care and industrial cleaning. Their mildness and conditioning effects make amphoteric surfactants ideal for use in shampoos, body washes, and skincare products. Industrial and institutional cleaning applications are also expanding due to growing hygiene requirements and regulatory compliance. In oil and gas, these surfactants are used for enhanced oil recovery and drilling fluids. It is diversifying further into sectors such as agriculture and textile processing, broadening the scope of demand.
Segments:
Based on Type:
- Amine Oxide
- Amphoacetates
- Amphopropionates
- Betaine
- Substituted Imidazoline
- Sultaines
Based on Function
- Detergency
- Emulsifiers
- Foaming Agents
- Wetting Agents
Based on Application
- Home Care
- Industrial & Institutional Cleaning
- Oil & Gas
- Personal Care
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant 28% share of the Amphoteric Surfactants Market, supported by strong demand from the personal care and home cleaning sectors. Consumers increasingly prefer sulfate-free, eco-labeled, and dermatologically tested formulations, boosting adoption of amphoteric surfactants. The presence of leading manufacturers and well-established R&D infrastructure encourages continuous product innovation. Regulatory support for green chemistry and safer ingredients further accelerates market growth. It benefits from rising demand for institutional and industrial cleaning products across healthcare and food processing industries. E-commerce expansion and premium product consumption also drive steady regional performance.
Europe
Europe accounts for 26% of the Amphoteric Surfactants Market and continues to lead in sustainability and regulatory compliance. Strict environmental and consumer safety standards drive the adoption of bio-based and biodegradable surfactants across home care and cosmetics applications. Demand is strong in countries like Germany, France, and the UK, where green consumerism is well established. It sees growing integration of amphoteric surfactants in hybrid formulations combining efficacy with reduced environmental impact. Key market players actively invest in clean-label innovations and certifications. Industrial cleaning applications also contribute significantly to regional growth.
Asia-Pacific
Asia-Pacific dominates the Amphoteric Surfactants Market with a 34% share, driven by rapid urbanization, expanding middle-class population, and rising hygiene awareness. Demand for personal care and home cleaning products is increasing across India, China, and Southeast Asia. It gains momentum from local manufacturing growth, cost-effective production, and expanding retail networks. Multinational brands are strengthening their regional presence through strategic investments and localized product offerings. Government initiatives supporting sanitation and health awareness further expand market reach. The region remains a critical growth engine due to volume-driven consumption and evolving lifestyle trends.
Rest of the World
The Rest of the World, including Latin America, the Middle East, and Africa, contributes 12% to the Amphoteric Surfactants Market. Growing urban populations, rising disposable income, and expanding access to personal care products are key drivers. It sees increasing demand in institutional cleaning and agrochemical formulations. Regional players are exploring partnerships and distribution agreements to strengthen market presence. Awareness of sustainable products is gradually improving, creating opportunities for long-term market development.
Key Player Analysis
- Clariant
- Croda International
- Galaxy Surfactants
- Evonik Industries AG
- DuPont
- Stepan
- ADEKA CORPORATION
- BASF
- The Lubrizol
- Dow
- Nouryon
- Akzo Nobel
Competitive Analysis
The Amphoteric Surfactants Market is highly competitive, with key players focusing on innovation, sustainability, and strategic expansion to strengthen their market position. Companies such as BASF, Croda International, Clariant, and Evonik Industries AG are investing in R&D to develop mild, bio-based, and multifunctional surfactants. It witnesses active collaboration among manufacturers and raw material suppliers to improve performance and reduce environmental impact. Firms like Galaxy Surfactants and ADEKA CORPORATION are expanding regionally through capacity additions and customized formulations. Dow, DuPont, and The Lubrizol emphasize product diversification to serve personal care, home care, and industrial segments. Competitive pricing, technological advancements, and regulatory compliance remain critical factors shaping market dynamics. Market participants are also enhancing their global distribution networks to meet rising demand in emerging markets. The Amphoteric Surfactants Market continues to evolve through innovation, quality differentiation, and customer-centric solutions that address shifting consumer preferences and sustainability benchmarks.
Recent Developments
- In August 2024, Galaxy Surfactants, a leading producer of performance surfactants and specialty care ingredients for the Home and Personal Care industry, will introduce its latest innovations and new product offerings aimed at meeting rising consumer demand for effective, safe, and sustainable solutions in these sectors.
- In 2025, BASF launched a new line of biodegradable amphoteric surfactants made from renewable resources. This development contributed to an 8% increase in market share within the eco-friendly segment.
- In October 2024, LanzaTech and Dow entered a strategic partnership to develop amphoteric surfactants and sustainable solutions for carbon capture and utilization, aiming to convert waste carbon into valuable products.
- On April 8, 2025, Nouryon unveiled Armocare® Aqua 12-an ISCC PLUS-certified, biodegradable, non-quat amphoteric conditioner-during the in-cosmetics Global event in Amsterdam.
Market Concentration & Characteristics
The Amphoteric Surfactants Market is moderately concentrated, with a mix of global giants and regional specialists shaping the competitive landscape. Large players such as BASF, Clariant, Croda International, and Evonik Industries dominate through extensive portfolios, global distribution networks, and sustained investments in R&D and sustainability. It also features regional and niche manufacturers like Galaxy Surfactants and ADEKA CORPORATION, which cater to localized needs and customized formulations. The market is characterized by high product differentiation, driven by application-specific performance, environmental compatibility, and regulatory compliance. Demand for bio-based, mild, and multifunctional surfactants continues to influence formulation trends across end-use sectors. Strategic partnerships, product innovation, and eco-certifications are central to competitive advantage. Price sensitivity, especially in emerging markets, shapes procurement and sourcing strategies. The Amphoteric Surfactants Market requires a balance between cost efficiency, quality standards, and regulatory adherence to maintain relevance in an evolving consumer and industrial landscape.
Report Coverage
The research report offers an in-depth analysis based on Type, Function, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for sulfate-free and skin-friendly formulations will continue to drive the use of amphoteric surfactants in personal care products.
- Manufacturers will focus on developing biodegradable and plant-based surfactants to meet environmental regulations and consumer expectations.
- The market will witness increased adoption in industrial and institutional cleaning due to growing hygiene and safety standards.
- Regional players will expand their product lines to cater to localized needs and cost-sensitive markets.
- Technological advancements will enhance the performance efficiency of amphoteric surfactants in multifunctional formulations.
- Partnerships between raw material suppliers and surfactant producers will support innovation in green chemistry.
- Digital platforms and e-commerce growth will boost accessibility and sales of surfactant-based products globally.
- Regulatory compliance and clean-label certifications will influence new product development strategies.
- Urbanization and rising disposable income in emerging markets will increase consumption across all application segments.
- Leading companies will invest in capacity expansion and regional diversification to maintain competitive advantage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Preference for Mild and Skin-Compatible Formulations
Consumers are increasingly seeking gentle, low-irritation ingredients for personal care and baby products, driving the adoption of amphoteric surfactants known for their mildness and compatibility with sensitive skin.
Growth of Sulfate-Free and pH-Balanced Products
The shift toward sulfate-free and pH-balanced formulations in shampoos, cleansers, and home care products is boosting demand for amphoteric surfactants, which provide effective cleansing without harshness.
Sustainability and Regulatory Compliance
Rising environmental awareness and stricter regulations are encouraging manufacturers to develop biodegradable, plant-based amphoteric surfactants, supporting market growth as companies seek eco-label certifications and cleaner formulations.
Expansion in Industrial and Institutional Cleaning
Amphoteric surfactants' excellent foaming, emulsifying, and compatibility properties are increasing their use in industrial and institutional cleaning applications, where performance and safety are critical.
Urbanization and Rising Hygiene Standards in Emerging Markets
Rapid urbanization, growing disposable incomes, and heightened hygiene awareness in Asia-Pacific, Latin America, and Africa are fueling demand for personal and home care products containing amphoteric surfactants.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Amphoteric Surfactants Market?
What factors are driving the growth of the Amphoteric Surfactants Market?
What are some challenges faced by the Amphoteric Surfactants Market?
Who are the major players in the Amphoteric Surfactants Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Amine Oxide
- 1.2.2 Amphoacetates
- 1.2.3 Amphopropionates
- 1.2.4 Betaine
- 1.2.5 Substituted Imidazoline
- 1.2.6 Sultaines
- 1.3 By Function
- 1.3.1 Detergency
- 1.3.2 Emulsifiers
- 1.3.3 Foaming Agents
- 1.3.4 Wetting Agents
- 1.4 By Application
- 1.4.1 Personal Care
- 1.4.2 Home Care
- 1.4.3 Industrial & Institutional Cleaning
- 1.4.4 Oil & Gas
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,805.81 million → 2032: USD 7,909.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Amphoteric Surfactants Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Amphoteric Surfactants Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Amphoteric Surfactants Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Amphoteric Surfactants Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Amphoteric Surfactants Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Amphoteric Surfactants Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Amphoteric Surfactants Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Amphoteric Surfactants Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,805.81 million → 2032: USD 7,909.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Amphoteric Surfactants Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Amine Oxide
- 12.3.7.2 Amphoacetates
- 12.3.7.3 Amphopropionates
- 12.3.7.4 Betaine
- 12.3.7.5 Substituted Imidazoline
- 12.3.7.6 Sultaines
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Function - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Detergency
- 12.4.7.2 Emulsifiers
- 12.4.7.3 Foaming Agents
- 12.4.7.4 Wetting Agents
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Personal Care
- 12.5.7.2 Home Care
- 12.5.7.3 Industrial & Institutional Cleaning
- 12.5.7.4 Oil & Gas
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Amphoteric Surfactants End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Amphoteric Surfactants Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Amphoteric Surfactants Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Amphoteric Surfactants Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Clariant
- 18.4 Croda International
- 18.5 Evonik Industries AG
- 18.6 Dow
- 18.7 DuPont
- 18.8 Galaxy Surfactants
- 18.9 Stepan
- 18.10 ADEKA CORPORATION
- 18.11 The Lubrizol
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

