
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Antistatic Brush Market Size 2024 | USD 240.6 Million |
| Antistatic Brush Market, CAGR | 4.9% |
| Antistatic Brush Market Size 2032 | USD 352.77 Million |
Market Overview:
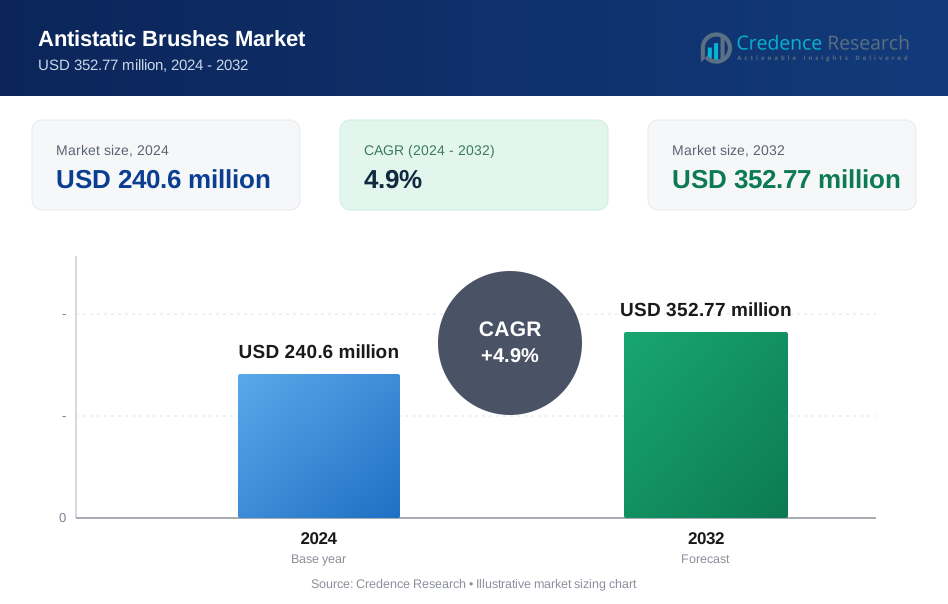
The Antistatic Brush Market is projected to grow from USD 240.6 million in 2024 to an estimated USD 352.77 million by 2032, with a compound annual growth rate (CAGR) of 4.9% from 2024 to 2032.
The antistatic brush market is propelled by the growing need for static charge management solutions in industries undergoing rapid technological transformation. In the electronics sector, these brushes are critical for ensuring the reliability of sensitive components, especially as miniaturization and higher circuit densities increase susceptibility to electrostatic damage. The automotive industry, integrating sophisticated electronic systems, also drives the demand for effective ESD solutions. Additionally, the rise of flexible packaging, driven by e-commerce and consumer demand for sustainable solutions, has heightened the need for static control in production lines. Advances in eco-friendly and customizable brushes further cater to niche industrial needs, while innovations in conductive materials enhance performance efficiency. Combined with increasing awareness of workplace safety and compliance with stringent regulations, these factors significantly boost market growth.
North America and Europe remain dominant players in the antistatic brush market due to established industrial bases, advanced manufacturing ecosystems, and rigorous regulatory frameworks emphasizing ESD safety. These regions benefit from consistent innovation and high adoption rates of advanced technologies. Meanwhile, Asia-Pacific emerges as a rapidly growing region, fueled by accelerated industrialization, the expanding electronics and automotive sectors, and significant investments in high-tech manufacturing in countries such as China, Japan, and South Korea. Additionally, nations in this region are adopting static control solutions to enhance efficiency and product quality. Latin America, the Middle East, and Africa exhibit steady growth potential as industries modernize, infrastructure development gains momentum, and awareness of ESD management increases. The global market is thus characterized by diverse regional dynamics, offering opportunities for both established and emerging players.
Market Drivers:
Increasing Adoption in Electronics and Semiconductor Industries:
The electronics and semiconductor industries are primary drivers of the antistatic brush market, as static electricity poses a significant risk to sensitive electronic components. With the proliferation of smaller, more complex devices, such as smartphones, tablets, and wearable technologies, the demand for effective static charge management has risen. Antistatic brushes are essential tools for ensuring that delicate components remain free from damage during manufacturing, assembly, and testing processes. As manufacturers adopt advanced production technologies to meet higher precision requirements, the role of antistatic brushes in maintaining product integrity and enhancing operational efficiency has become indispensable.
Rising Demand in Automotive Manufacturing and Advanced Technologies:
The automotive sector is increasingly integrating electronic systems, such as advanced driver-assistance systems (ADAS), infotainment systems, and electric vehicle (EV) components. These systems are highly susceptible to electrostatic discharge (ESD), making static control critical in automotive production environments. Antistatic brushes provide a reliable solution for cleaning surfaces and minimizing static buildup, ensuring the safety and performance of electronic components. For instance, Tesla uses antistatic brushes in the assembly of its electric vehicles to prevent ESD damage to sensitive components. Furthermore, the rapid shift toward electric and autonomous vehicles has amplified the need for effective static management. As automotive manufacturers prioritize the adoption of ESD-compliant tools, the antistatic brush market is poised for substantial growth in this sector.
Expanding Applications in Printing, Packaging, and Industrial Manufacturing:
The growing demand for flexible packaging and high-quality printing solutions has contributed significantly to the expansion of the antistatic brush market. Static electricity can disrupt printing processes, leading to defects and inefficiencies. In packaging, especially in high-speed production lines, static buildup can cause materials to stick together, reducing productivity and quality. Antistatic brushes address these challenges by ensuring smooth operations and improved output quality. For instance, companies like HP use antistatic brushes in their printing processes to maintain high-quality output. Similarly, in industrial manufacturing, where precision and cleanliness are paramount, antistatic brushes play a crucial role in maintaining equipment performance and reducing operational downtime. The rise of automation and advanced manufacturing systems further underscores the importance of static control solutions.
Regulatory Compliance and Technological Advancements Driving Adoption:
Stringent regulations and standards related to workplace safety and ESD compliance have become key factors driving the adoption of antistatic brushes. Industries worldwide are increasingly adhering to protocols aimed at mitigating risks associated with static electricity, boosting demand for reliable and efficient static control tools. Additionally, advancements in conductive materials and brush designs have resulted in more durable, eco-friendly, and customizable solutions. These innovations cater to the specific needs of diverse industries, enhancing the utility and efficiency of antistatic brushes. As manufacturers continue to invest in research and development to create next-generation products, the market is expected to witness sustained growth and technological evolution.
Market Trends:
Growing Demand for Miniaturized and Precision Equipment:
A key trend in the antistatic brush market is the rising demand for brushes designed for miniaturized and precision equipment. As industries such as electronics and healthcare focus on smaller and more intricate devices, the need for precision static control tools has grown. Antistatic brushes tailored for delicate operations, such as cleaning microelectronic components or handling sensitive optical equipment, are gaining prominence. This trend is further fueled by advancements in manufacturing technologies, such as 3D printing and nano-technology, which require stringent static management solutions to ensure process efficiency and product reliability.
Increased Focus on Sustainability and Eco-Friendly Solutions:
Sustainability has emerged as a prominent trend in the antistatic brush market. Companies are increasingly focusing on the development of eco-friendly products by using recyclable and biodegradable materials in brush manufacturing. This shift is driven by growing environmental awareness among industries and consumers alike, as well as regulatory pressures aimed at reducing industrial waste. Manufacturers are also exploring innovative designs that extend the lifespan of antistatic brushes, reducing the frequency of replacement and overall environmental impact. This trend aligns with broader sustainability goals across sectors and enhances the market appeal of environmentally conscious solutions. For example, Beauty by Earth offers an eco-friendly boar bristle hair brush that can be used on wet or dry hair.
Integration of Smart Technologies:
The integration of smart technologies into static control solutions is revolutionizing the antistatic brush market. The development of IoT-enabled brushes and advanced sensors allows real-time monitoring of static levels and brush performance, providing actionable insights to operators. This trend is particularly evident in high-tech industries such as electronics, automotive, and aerospace, where precision and reliability are paramount. By incorporating smart features, manufacturers not only enhance the functionality of antistatic brushes but also cater to the growing demand for automation and connectivity in industrial processes. The adoption of such technologies is expected to open new opportunities for innovation and market growth. For instance, Dyson has announced the launch of its 360 Vis Nav robotic vacuum cleaner in 2024, which features 26 sensors for dust detection, obstacle avoidance, and wall detection.
Regional Diversification and Emerging Markets:
The antistatic brush market is witnessing significant regional diversification, with emerging markets in Asia-Pacific, Latin America, and the Middle East playing an increasingly important role. Rapid industrialization, coupled with the expansion of sectors such as electronics, automotive, and consumer goods in these regions, is driving demand for effective static control solutions. Additionally, local manufacturers in these markets are investing in advanced production technologies, creating a competitive landscape and boosting regional market dynamics. As global players seek to expand their footprint, partnerships, and collaborations with regional manufacturers are becoming a common strategy to tap into these high-growth areas. This trend underscores the importance of localized solutions and global connectivity in shaping the future of the antistatic brush market.
Market Restraints and Challenges:
High Initial Costs and Limited Awareness:
One of the primary restraints in the antistatic brush market is the high initial costs associated with advanced brushes, particularly those designed for specialized industrial applications. These brushes often require high-quality conductive materials and precise manufacturing processes, increasing their price compared to conventional cleaning tools. Small and medium-sized enterprises (SMEs) may find it challenging to justify the investment, especially if their operations do not immediately highlight the risks of static electricity. Additionally, limited awareness of the long-term benefits of antistatic solutions, particularly in emerging markets, hampers widespread adoption. Many businesses remain unaware of the potential damages and inefficiencies caused by static electricity, further slowing market penetration.
Competition from Alternative Technologies:
The market faces challenges from alternative static control technologies such as ionizing bars, air ionizers, and antistatic sprays. These alternatives, while serving different operational needs, often compete with antistatic brushes by offering potentially lower upfront costs or ease of integration into automated systems. For instance, ionizing equipment can be particularly effective in high-speed production lines where manual or brush-based solutions may not be practical. This competition can limit the adoption of antistatic brushes in specific industrial settings, particularly where technological alternatives offer similar results.
Material Durability and Maintenance Concerns:
While antistatic brushes are designed to be durable, frequent use in harsh industrial environments can lead to wear and tear, reducing their effectiveness over time. Ensuring consistent performance requires regular maintenance or replacement, which adds to the operational costs for businesses. Furthermore, in industries handling aggressive chemicals or abrasive materials, the lifespan of antistatic brushes can be further reduced, creating concerns about their cost-effectiveness. These challenges highlight the need for continued innovation to improve the durability and performance of antistatic brushes under diverse working conditions.
Market Segmentation Analysis:
The antistatic brush market is segmented based on filament material, brush type, and application, allowing for a detailed understanding of market dynamics and consumer preferences.
By Filament Material, nylon, stainless steel, brass, aluminum, and carbon fiber dominate the market. Nylon filaments are widely preferred for their versatility and cost-effectiveness, making them suitable for diverse applications. Stainless steel and brass filaments cater to industries requiring durability and conductivity, particularly in harsh environments. Carbon fiber, known for its superior static dissipation properties, is increasingly used in high-precision applications, such as electronics and aerospace, where static control is critical.
By Brush Type, tufted strip and plate brushes, disk brushes, and cylindrical brushes are key segments. Tufted strip and plate brushes are extensively used for cleaning and static charge removal on flat surfaces, while disk brushes are favored for precision cleaning in small, intricate areas. Cylindrical brushes, offering broad coverage, are primarily utilized in conveyor systems and automated industrial processes.
By Application, industrial equipment, automotive applications, home applications, power supply, micro motors, and others define the market. The industrial equipment segment leads due to the widespread use of antistatic brushes in manufacturing and assembly lines. Automotive applications are growing rapidly, driven by the increased use of electronic components in vehicles. Home applications and micro motors represent niche but emerging segments, benefiting from heightened consumer awareness of static charge management.
Segmentation:
By Filament Material
- Nylon
- Stainless Steel
- Brass
- Aluminum
- Carbon Fiber
By Brush Type
- Tufted Strip and Plate Brushes
- Disk Brushes
- Cylindrical Brushes
By Application
- Industrial Equipment
- Automotive Application
- Home Application
- Power Supply
- Micro Motors
- Other
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The antistatic brush market exhibits diverse regional dynamics, with significant contributions from North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Each region's market share and growth potential are shaped by industrial developments, technological advancements, and regulatory frameworks.
North America holds a significant market share, accounting for approximately 30% of the global market. The region's dominance is attributed to its well-established industries, particularly in electronics, automotive, and aerospace, which have a high demand for static control solutions. Stringent safety regulations and strong R&D investments further drive market growth. The presence of leading manufacturers and early adoption of advanced technologies position North America as a key player in the market.
Europe follows closely, contributing about 25% to the global market. The region benefits from a robust industrial base, particularly in automotive and high-tech manufacturing. Countries like Germany, the UK, and France are leading markets due to their advanced manufacturing processes and compliance with strict ESD regulations. Additionally, Europe's focus on sustainability has spurred the adoption of eco-friendly and durable antistatic solutions.
Asia-Pacific is the fastest-growing region, accounting for approximately 28% of the market share. Rapid industrialization, particularly in China, Japan, and South Korea, has created substantial demand for antistatic brushes. The region’s burgeoning electronics and semiconductor industries, coupled with the expansion of automotive manufacturing, drive growth. Increasing awareness of ESD risks and rising investments in high-tech production facilities further boost the market in this region.
Latin America represents around 10% of the global market. The region's growth is fueled by the modernization of manufacturing sectors and the rising adoption of advanced industrial equipment. Countries such as Brazil and Mexico are key contributors, benefiting from the expansion of automotive and electronics industries.
The Middle East & Africa holds the remaining 7% market share. While still emerging, the region shows potential due to increasing industrialization and infrastructural developments. The adoption of static control solutions in sectors such as packaging, petrochemicals, and manufacturing is gradually gaining traction.
Key Player Analysis:
- 3M Company
- Desco Industries Inc.
- Electro Static Technology Inc.
- Gordon Brush Mfg. Co., Inc.
- Kinetronics Corporation
- Kleentek
- Mencom Corporation
- Menda Tools
- Panasonic Corporation
- Precision Brush Company
- RS Components Ltd.
- Saint-Gobain Performance Plastics
- Schunk GmbH
- Sealeze, A Jason Company
- Simco-Ion
- Staples World
- Static Solutions Inc.
- Statico Inc.
- Techspray
- Transforming Technologies
Competitive Analysis:
The antistatic brush market is highly competitive, characterized by the presence of established players and emerging manufacturers catering to diverse industrial needs. Key market participants focus on innovation, leveraging advancements in materials and design to offer more efficient, durable, and customizable solutions. Prominent companies compete on factors such as product quality, performance, pricing, and the ability to meet industry-specific requirements. Leading players are investing in research and development to enhance the static control capabilities of their brushes, targeting high-growth sectors like electronics, automotive, and advanced manufacturing. Additionally, strategic partnerships, mergers, and acquisitions are common strategies to expand market share and geographical reach. Emerging players, particularly in Asia-Pacific, are intensifying competition by offering cost-effective solutions to meet growing regional demand. The market’s competitive landscape is further influenced by the rising emphasis on sustainability, pushing companies to develop eco-friendly and recyclable products to differentiate themselves in the global marketplace.
Recent Developments:
- GIMME Beauty launched a new detangling brush in April 2022. The brush features flexible nylon bristles that are heat-resistant, anti-static, and frizz-free, designed for thick, medium, and fine hair textures.
- Kent announced the launch of a new salon-quality collection for home hair styling in 2022. The collection includes a range of colorful nylon-quilled hairbrushes suitable for all hair types.
Market Concentration & Characteristics:
The antistatic brush market exhibits a moderately fragmented structure, with a mix of established global players and smaller regional manufacturers. Market concentration varies by region; North America and Europe are dominated by leading companies with advanced R&D capabilities, while Asia-Pacific sees a higher presence of emerging local manufacturers competing on cost efficiency. The market is characterized by a strong focus on product customization, driven by diverse applications across industries such as electronics, automotive, and packaging. Innovations in filament materials, eco-friendly designs, and IoT-enabled solutions are key differentiators among competitors. Additionally, the market demonstrates high responsiveness to regulatory frameworks, particularly in regions with stringent safety standards for static control. Customer demand for durable, high-performance, and cost-effective solutions shapes the competitive dynamics. Despite competition from alternative technologies, the antistatic brush market remains resilient due to its versatility, ease of use, and effectiveness in static charge mitigation.
Report Coverage:
The research report offers an in-depth analysis based on By Filament Material, By Brush Type and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The antistatic brush market is expected to grow significantly, driven by increased adoption across electronics, automotive, and packaging industries.
- Advancements in conductive materials and innovative brush designs will enhance product efficiency and durability.
- Asia-Pacific is projected to lead market expansion due to rapid industrialization and growth in the electronics and automotive sectors.
- Rising awareness of electrostatic discharge (ESD) risks will drive demand for static control solutions in emerging markets.
- Integration of smart technologies, such as IoT-enabled brushes, will create new opportunities for innovation and adoption.
- Sustainability trends will push manufacturers toward eco-friendly and recyclable brush materials.
- Increasing applications in precision manufacturing and miniaturized equipment will boost demand for customized brushes.
- Regulatory compliance and safety standards will remain critical in driving market growth across industrial sectors.
- Growing investments in research and development will foster the development of advanced, high-performance brushes.
- Strategic collaborations and regional expansion will shape the competitive landscape, offering growth opportunities for both global and local players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption in Electronics and Semiconductor Industries
The proliferation of sensitive electronic devices and miniaturized components has made static charge management critical, driving demand for antistatic brushes to prevent electrostatic discharge (ESD) damage during manufacturing and assembly.
Growth in Automotive Manufacturing and Advanced Technologies
The integration of advanced electronic systems in vehicles, including electric and autonomous vehicles, increases the need for ESD protection, making antistatic brushes essential for safe and efficient automotive production lines.
Expansion in Printing, Packaging, and Industrial Manufacturing
High-speed production lines in packaging and precision requirements in printing and industrial manufacturing require effective static control to prevent defects and inefficiencies, fueling the use of antistatic brushes.
Regulatory Compliance and Safety Standards
Stringent workplace safety regulations and ESD compliance standards across industries are compelling manufacturers to adopt reliable static control solutions, boosting the market for antistatic brushes.
Technological Advancements and Customization
Innovations in conductive materials, eco-friendly designs, and the development of IoT-enabled brushes are enhancing performance, durability, and customization, expanding the market’s appeal across diverse industrial applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the antistatic brush market by 2032?
What drives the growth of the antistatic brush market?
What regions dominate the antistatic brush market?
What are the challenges faced by the antistatic brush market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Brush Type
- 1.2.1 Tufted Strip and Plate Brushes
- 1.2.2 Disk Brushes
- 1.2.3 Cylindrical Brushes
- 1.3 By Application
- 1.3.1 Industrial Equipment
- 1.3.2 Automotive Application
- 1.3.3 Home Application
- 1.3.4 Power Supply
- 1.3.5 Micro Motors
- 1.3.6 Other
- 1.4 By Filament Material
- 1.4.1 Nylon
- 1.4.2 Stainless Steel
- 1.4.3 Brass
- 1.4.4 Aluminum
- 1.4.5 Carbon Fiber
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 240.6 million → 2032: USD 352.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Antistatic Brushes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Antistatic Brushes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Antistatic Brushes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Antistatic Brushes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Antistatic Brushes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Antistatic Brushes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Antistatic Brushes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Antistatic Brushes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 240.6 million → 2032: USD 352.77 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Antistatic Brushes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Brush Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Tufted Strip and Plate Brushes
- 12.3.7.2 Disk Brushes
- 12.3.7.3 Cylindrical Brushes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial Equipment
- 12.4.7.2 Automotive Application
- 12.4.7.3 Home Application
- 12.4.7.4 Power Supply
- 12.4.7.5 Micro Motors
- 12.4.7.6 Other
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Filament Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Nylon
- 12.5.7.2 Stainless Steel
- 12.5.7.3 Brass
- 12.5.7.4 Aluminum
- 12.5.7.5 Carbon Fiber
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Antistatic Brushes End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Antistatic Brushes Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Antistatic Brushes Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Antistatic Brushes Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Desco Industries Inc.
- 18.4 Gordon Brush Mfg. Co., Inc.
- 18.5 Kinetronics Corporation
- 18.6 Panasonic Corporation
- 18.7 Precision Brush Company
- 18.8 RS Components Ltd.
- 18.9 Saint-Gobain Performance Plastics
- 18.10 Simco-Ion
- 18.11 Techspray
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
