
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Artificial Intelligence (AI) in Chemical Market Size 2024 | USD 1,365 Million |
| Artificial Intelligence (AI) in Chemical Market, CAGR | 36.3% |
| Artificial Intelligence (AI) in Chemical Market Size 2032 | USD 16,259.21 Million |
Market Overview
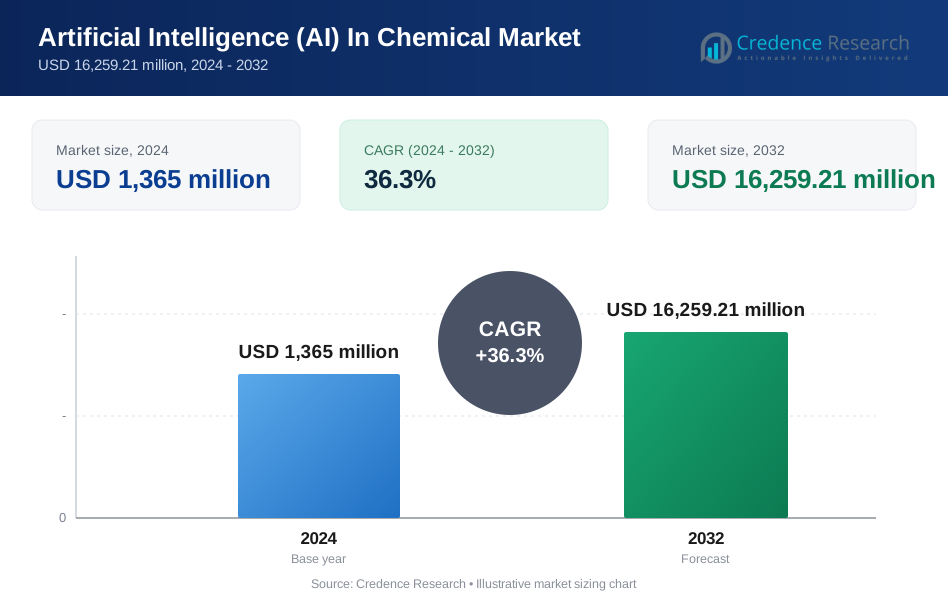
The Artificial Intelligence (AI) in Chemical Market is projected to grow from USD 1,365 million in 2024 to USD 16,259.21 million by 2032, reflecting a compound annual growth rate (CAGR) of 36.3%.
The Artificial Intelligence (AI) in Chemical Market is driven by increasing demand for process optimization, enhanced product quality, and reduced operational costs. AI technologies, such as machine learning and predictive analytics, are being utilized to streamline chemical manufacturing processes, enabling real-time monitoring and data-driven decision-making. The rise of digitalization across the chemical industry and the need for sustainable practices further accelerate AI adoption. Additionally, AI-driven innovations in material discovery, supply chain optimization, and predictive maintenance are key trends shaping the market, contributing to enhanced efficiency and competitiveness within the chemical sector.
The Artificial Intelligence (AI) in Chemical Market is experiencing significant growth, with North America holding the largest market share, driven by advanced technological infrastructure and the presence of key players such as Univar Solutions Inc. and IMCD N.V. Europe follows closely, driven by increasing investments in AI for process optimization in the chemical sector and strong regulatory support for innovation. Additionally, Asia Pacific is emerging as a rapidly growing region, fueled by industrial expansion and the adoption of AI technologies by chemical companies in countries like China and India. Leading global players include Brenntag S.E. and Azelis Group NV.
Market Drivers
Enhanced Efficiency and Productivity
Artificial intelligence (AI) is revolutionizing efficiency and productivity in the chemical industry by optimizing production processes and predicting maintenance needs. AI can analyze large datasets to identify inefficiencies, streamline workflows, and enhance output, leading to cost reduction. For example, AI-powered systems can optimize raw material usage and energy consumption, improving operational efficiency. For instance, a chemical company reported that AI models analyzing real-time data optimized process parameters, enhancing efficiency and product quality. Additionally, AI-driven predictive maintenance systems anticipate equipment failures before they occur, minimizing costly downtimes and reducing maintenance expenses. These capabilities allow companies to maximize productivity while maintaining operational continuity, ensuring smoother, more cost-effective production.
Improved Safety
AI is also playing a critical role in improving safety within chemical operations. Through advanced algorithms, AI can analyze historical data to detect potential safety hazards, enabling proactive measures to avoid accidents. AI-powered real-time monitoring systems continuously track production processes, quickly identifying anomalies that could lead to dangerous situations, ensuring a safer working environment. For instance, AI systems analyzing real-time data from sensors provided early warnings of equipment malfunctions, identifying potential safety risks and recommending corrective actions. This predictive approach to safety not only prevents accidents but also reduces the likelihood of equipment malfunctions and other operational risks. As AI becomes more integrated into safety protocols, the overall risk of chemical operations is significantly mitigated.
Accelerated Research and Development
In research and development (R&D), AI is accelerating the discovery of new materials and compounds by simulating molecular interactions and conducting virtual screenings. AI-driven molecular modeling allows chemists to predict how different molecules will interact, speeding up the design of innovative materials. Virtual screening technologies use AI to rapidly assess large databases of molecules, identifying promising candidates for drug development or chemical synthesis. This accelerated R&D process leads to faster innovation and significantly reduces the time and cost associated with traditional experimentation methods, giving companies an edge in product development.
Increased Sustainability and Competitive Advantage
Sustainability is another key driver for AI adoption in the chemical industry. AI optimizes the use of resources, such as energy and raw materials, reducing waste and environmental impact. By leveraging AI, companies can also develop green chemistry solutions, creating more sustainable products and processes. In doing so, businesses not only reduce their environmental footprint but also gain a competitive advantage. AI-driven innovation and cost reductions enable chemical companies to enhance profitability while addressing sustainability challenges. Additionally, AI helps companies comply with complex regulations by improving data management and conducting risk assessments, ensuring that operations remain safe and compliant.
Market Trends
Integration with IoT and Growing Importance of AI in Research and Development
The integration of AI with Internet of Things (IoT) devices is transforming the chemical industry by providing real-time monitoring and control over production processes. For instance, an innovative chemical company uses IoT-enabled sensors combined with AI to facilitate the continuous collection and analysis of operational data, enabling immediate adjustments to optimize efficiency and ensure safety. This real-time data allows companies to run remote operations, where AI-powered platforms manage and oversee distributed manufacturing facilities, improving overall process visibility and control. In addition to these operational benefits, AI's role in research and development (R&D) is becoming increasingly vital. AI is accelerating breakthroughs in drug discovery by simulating molecular interactions and identifying potential drug candidates more quickly than traditional methods. In materials science, AI is helping researchers design new materials with improved properties, such as greater strength or enhanced conductivity, pushing the boundaries of innovation. This growing reliance on AI for both operational and R&D purposes highlights the expanding role of AI in transforming chemical manufacturing practices, making companies more competitive and innovative in their approach.
Increasing Adoption of AI-Powered Solutions and Focus on Predictive Analytics
The chemical industry is witnessing a significant rise in the adoption of AI-powered solutions, primarily driven by the need to automate various production processes and enhance operational efficiency. Companies are leveraging AI to streamline tasks such as quality control, inventory management, and supply chain optimization, resulting in better cost management and improved product consistency. AI's ability to enable data-driven decision-making has become critical, allowing manufacturers to optimize processes based on real-time data insights. This results in increased efficiency, reduced waste, and enhanced product quality, making AI an essential tool in modern chemical production. Additionally, the focus on predictive analytics is reshaping maintenance strategies within the sector. AI-driven predictive maintenance tools are helping manufacturers anticipate equipment failures, allowing for timely interventions that reduce unplanned downtimes and maintenance costs. Moreover, AI-powered demand forecasting tools enable chemical companies to better predict market trends and adjust production schedules accordingly, ensuring that supply meets demand while avoiding overproduction and stockouts.
Market Challenges Analysis
Organizational Resistance, Ethical Concerns, and System Integration
Resistance to change within organizations presents another challenge to the adoption of AI in the chemical sector. Organizational culture can be slow to adapt to new technologies, with employees and management often hesitant to implement systems that they may not fully understand. For instance, more than 80% of executives in the chemical industry surveyed by IBM admit that artificial intelligence (AI) will have an immense impact on their business within the next three years, yet only 4 out of 10 chemical companies widely implement AI in their operations. Fear of job displacement due to automation also contributes to resistance, with employees concerned about the potential impact on their roles. On top of organizational resistance, ethical considerations come into play when adopting AI. Bias in AI models, often stemming from biased training data, can lead to discriminatory outcomes in decision-making processes. Additionally, the use of AI raises concerns about data privacy, especially when handling sensitive operational or personal data, as compliance with data privacy regulations such as GDPR and CCPA becomes more critical. Integrating AI with existing systems also poses challenges. Many chemical companies rely on legacy systems that are not easily compatible with modern AI solutions, making integration complex and time-consuming. Migrating data into AI-compatible formats further adds to these difficulties, requiring careful planning and technical expertise.
Data Quality, Availability, and Complexity of Implementation
One of the major challenges in the adoption of AI in the chemical industry is the issue of data quality and availability. Many chemical companies operate with data stored in silos, which hinders the ability to integrate and analyze data effectively. Without comprehensive and connected data systems, the potential of AI to deliver meaningful insights is significantly reduced. Moreover, inconsistent or inaccurate data can further undermine AI models, leading to unreliable results. This requires companies to invest time and resources into cleaning and harmonizing their data to ensure it meets the quality standards necessary for AI to function optimally. Alongside data issues, the complexity and cost of implementing AI solutions are significant barriers. The process of developing and integrating AI requires specialized technical expertise that is often difficult to acquire. In addition, the upfront investment for AI infrastructure and model development can be substantial, deterring smaller companies or those with limited resources from fully embracing these technologies.
Market Segmentation Analysis:
By Product Type:
The Artificial Intelligence (AI) in Chemical market is segmented by type into hardware, software, and services. The software segment is expected to hold the largest market share due to the growing adoption of AI-powered solutions for process optimization, predictive analytics, and data management across chemical manufacturing operations. Hardware plays a critical role in supporting AI applications, including sensors and processing units for real-time data collection and analysis. Meanwhile, the demand for services is rising as companies seek consulting, integration, and maintenance services to implement and optimize AI-driven solutions in their production lines and supply chains, ensuring long-term efficiency.
By Application:
In terms of application, AI is being utilized in various areas of the chemical industry. Discovery of new materials and production optimization are two key areas where AI is transforming operations by accelerating research and improving manufacturing efficiency. AI-powered pricing optimization and load forecasting of raw materials are enabling companies to manage costs effectively and predict market demands. Additionally, process management & control and feedstock optimization are leveraging AI algorithms to streamline production, reduce waste, and enhance overall operational efficiency, positioning AI as a critical driver of innovation in the chemical sector.
Segments:
Based on Type:
- Hardware
- Software
- Services
Based on Application:
- Discovery of new materials
- Production optimization
- Pricing optimization
- Load forecasting of raw materials
- Product portfolio optimization
- Feedstock optimization
- Process management & control
Based on End User:
- Base Chemicals & Petrochemicals
- Specialty Chemicals
- Agrochemicals
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share in the Artificial Intelligence (AI) in Chemical market, accounting for approximately 35% of the global market. This region's dominance is driven by the early adoption of advanced technologies, a strong presence of AI solution providers, and substantial investment in research and development across various industries. The United States, in particular, leads the region due to its well-established chemical industry and robust infrastructure supporting AI implementation. Additionally, the integration of AI for production optimization, process automation, and sustainability initiatives is widely adopted in North America, further contributing to its leadership position. The presence of major chemical manufacturers, coupled with government initiatives supporting digital transformation, is expected to continue propelling market growth in this region.
Asia Pacific
Asia Pacific is emerging as a rapidly growing region in the AI in Chemical market, capturing nearly 30% of the global market share. The region’s growth is largely driven by the expanding chemical manufacturing sector in countries like China, India, and Japan. The increasing adoption of AI technologies to improve operational efficiency, manage resources, and reduce production costs is particularly prominent in these markets. Government support for smart manufacturing initiatives and the integration of AI in industrial processes are also driving growth. Asia Pacific's large consumer base, coupled with the growing demand for specialty chemicals and sustainable practices, positions it as a key region for future expansion in the AI in Chemical market.
Key Player Analysis
- Sinochem Corporation
- Omya AG
- Tricon Energy Inc.
- Azelis Group NV
- Sojitz Corporation
- Manuchar N.V.
- Biesterfeld AG
- IMCD N.V.
- Brenntag S.E.
- Petrochem Middle East
- ICC Industries Inc.
- HELM AG
- Univar Solutions Inc.
Competitive Analysis
The Artificial Intelligence (AI) in Chemical Market is highly competitive, with major players focusing on innovation and technological advancements to gain a competitive edge. Companies like Univar Solutions Inc., Brenntag S.E., IMCD N.V., and Azelis Group NV are integrating AI technologies into their operations to enhance process efficiency, optimize production, and improve sustainability efforts. These players are investing heavily in AI-driven solutions for predictive maintenance, process automation, and data analytics to streamline chemical manufacturing and distribution. The competition is centered around offering AI-based solutions that can provide actionable insights, reduce operational costs, and improve safety and compliance. Additionally, partnerships, mergers, and acquisitions are key strategies adopted by leading companies to strengthen their market position and expand their AI capabilities. The drive to enhance customer experiences and stay ahead of regulatory requirements is pushing players to continuously innovate and integrate AI across various segments of the chemical industry.
Recent Developments
- In April 2024, Brenntag entered into a strategic partnership with Knowde to master product data with AI, enhancing their digital transformation.
- In August 2023, Sinochem Holdings was ranked 38th on the 2023 Fortune Global 500 list.
- In July 2023, Sojitz Corporation invested in Hycamite TCD Technologies Oy in Finland, a developer of turquoise hydrogen production technology.
Market Concentration & Characteristics
The Artificial Intelligence (AI) in Chemical Market exhibits a moderate to high level of market concentration, with several key players dominating the industry due to their advanced technological capabilities and strong market presence. Large chemical companies are increasingly adopting AI-driven solutions for process optimization, predictive maintenance, and innovation in material discovery. These dominant players benefit from significant investments in research and development, allowing them to integrate AI into various facets of chemical production, from raw material management to pricing optimization. The market is characterized by the growing demand for AI solutions that enhance operational efficiency, reduce costs, and support sustainability initiatives. However, there is also room for smaller, niche companies that provide specialized AI services or focus on specific applications within the chemical industry. As the market evolves, the focus on AI-driven innovation and collaboration between chemical companies and AI technology providers will continue to shape the competitive landscape.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- AI adoption in the chemical industry will continue to accelerate as companies seek to enhance process efficiency and reduce operational costs.
- Predictive analytics will play a key role in improving equipment maintenance and minimizing downtime.
- AI-driven research and development will speed up the discovery of new materials and chemical compounds.
- Integration of AI with IoT devices will enable real-time monitoring and control of chemical processes.
- AI will help chemical companies optimize resource usage, supporting sustainability and environmental goals.
- Demand forecasting and pricing optimization will become more accurate through AI, improving market responsiveness.
- AI will enable more efficient management of complex global supply chains in the chemical sector.
- Ethical considerations and data privacy regulations will become more prominent as AI adoption increases.
- AI-powered platforms will foster greater collaboration between chemical companies and technology providers.
- Smaller companies will increasingly adopt AI solutions as cloud-based platforms make AI more accessible and scalable.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Artificial Intelligence (AI) In Chemical Market?
What factors are driving the growth of the Artificial Intelligence (AI) In Chemical Market?
What are the key segments within the Artificial Intelligence (AI) In Chemical Market?
What are some challenges faced by the Artificial Intelligence (AI) In Chemical Market?
Who are the major players in the Artificial Intelligence (AI) In Chemical Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Artificial Intelligence (AI) In Chemical Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Artificial Intelligence (AI) In Chemical Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,365 million → 2032: USD 16,259.21 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Artificial Intelligence (AI) In Chemical Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Artificial Intelligence (AI) In Chemical Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Artificial Intelligence (AI) In Chemical Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Artificial Intelligence (AI) In Chemical Market Drivers
- 3.3 Artificial Intelligence (AI) In Chemical Market Restraints & Challenges
- 3.4 Artificial Intelligence (AI) In Chemical Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Artificial Intelligence (AI) In Chemical Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Artificial Intelligence (AI) In Chemical Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Artificial Intelligence (AI) In Chemical category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Artificial Intelligence (AI) In Chemical Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Artificial Intelligence (AI) In Chemical Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Artificial Intelligence (AI) In Chemical market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Artificial Intelligence (AI) In Chemical Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Artificial Intelligence (AI) In Chemical Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Artificial Intelligence (AI) In Chemical Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Artificial Intelligence (AI) In Chemical (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Artificial Intelligence (AI) In Chemical Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Artificial Intelligence (AI) In Chemical Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Artificial Intelligence (AI) In Chemical Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Artificial Intelligence (AI) In Chemical Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Artificial Intelligence (AI) In Chemical Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Artificial Intelligence (AI) In Chemical Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Artificial Intelligence (AI) In Chemical Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Artificial Intelligence (AI) In Chemical Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Artificial Intelligence (AI) In Chemical Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
