
Market Overview
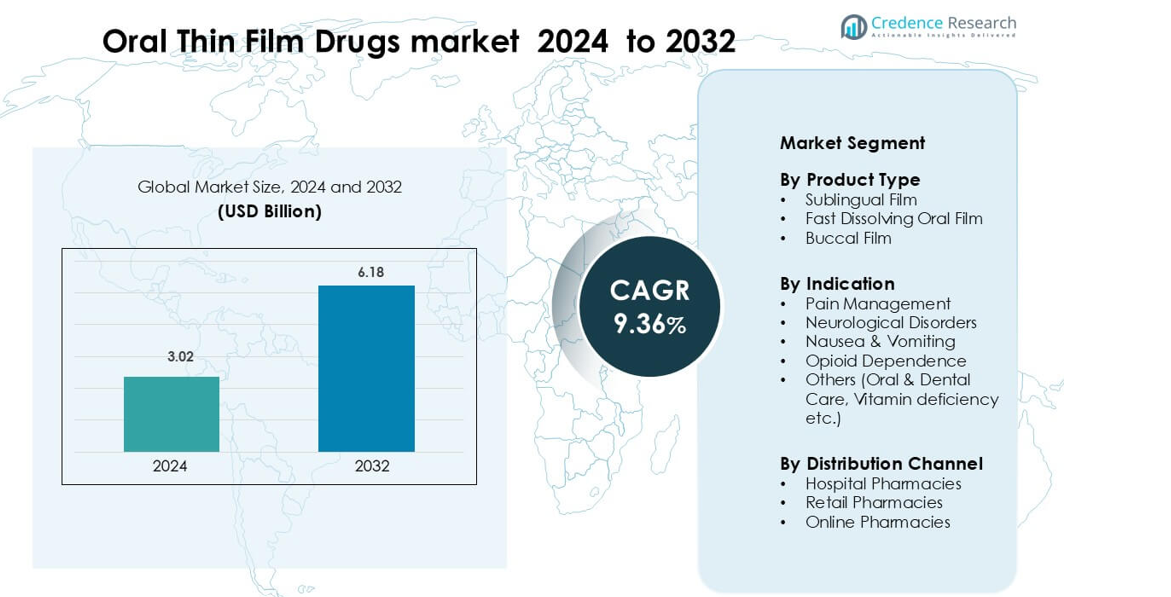
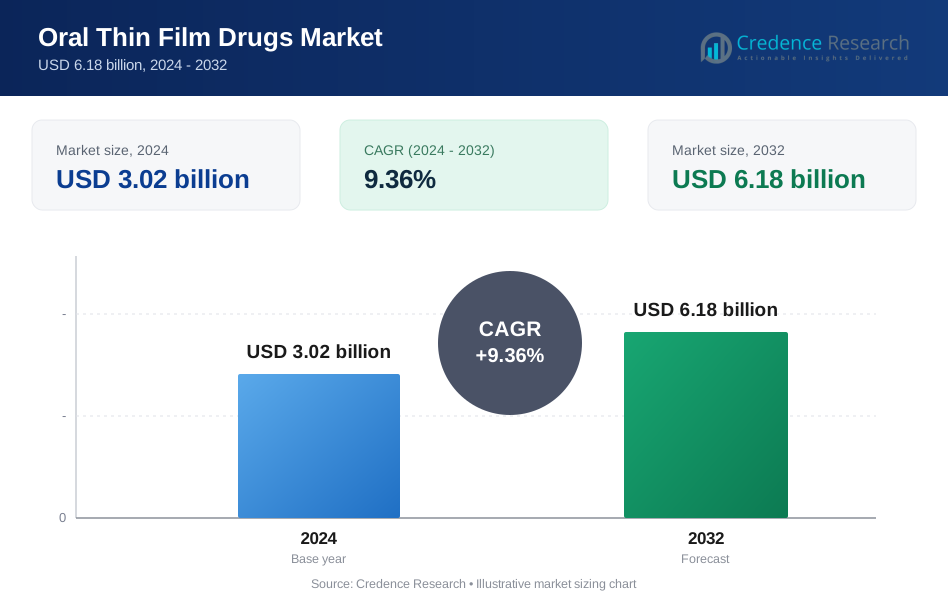
Oral Thin Film Drugs market was valued at USD 3.02 billion in 2024 and is anticipated to reach USD 6.18 billion by 2032, growing at a CAGR of 9.36 % during the forecast period.</p
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Oral Thin Film Drugs Market Size 2024 | USD 3.02 billion |
| Oral Thin Film Drugs Market, CAGR | 9.36% |
| Oral Thin Film Drugs Market Size 2032 | USD 6.18 billion |
The Oral Thin Film Drugs market features leading companies such as Cure Pharmaceutical, Nova Thin Film Pharmaceuticals LLC, ARx LLC, Viatris Inc., C.L. Pharm, CD Formulation, Corium Innovations Inc., ZIM LABORATORIES LIMITED, Aquestive Therapeutics Inc., and LTS Lohmann Therapie-Systeme AG. These firms compete through advancements in rapid-dissolution technologies, improved bioavailability, and patient-centric formulations. North America remains the dominant regional market with 41% share, supported by strong adoption of sublingual and fast-dissolving films in pain, neurological, and opioid-dependence therapies, backed by mature regulatory systems and high innovation activity.
Market Insights
- The Oral Thin Film Drugs market was USD 3.02 billion in 2024, will reach USD 6.18 billion by 2032, growing at a 9.36% CAGR.
- Demand rises due to fast-acting sublingual and fast-dissolving films, with sublingual films holding 48% share in 2024.
- Key trends include reformulation of chronic-care drugs, strong uptake in pediatric and geriatric groups, and wider e-pharmacy access.
- Competitive activity centers on polymer upgrades, better taste-masking, and stronger stability control led by major players aiming for wider global reach.
- North America leads the market with 41% share, while Europe holds 28% and Asia-Pacific follows with 22%, supported by rising use in pain and neurological care.
Market Segmentation Analysis:
By Product Type
Sublingual film holds the dominant position in the Oral Thin Film Drugs market with about 48% share in 2024. This format leads because sublingual delivery offers faster absorption and higher bioavailability than conventional oral routes. The segment grows due to rising demand for rapid-onset therapies in pain and neurological care. Fast dissolving oral films gain steady traction for pediatric and geriatric patients, while buccal films expand in chronic disease treatment. Growth across all formats is driven by better patient compliance and improved polymer-based film technologies.
- For instance, Orexo, a company specialising in sublingual tablet, leveraged its sublingual platform to commercialise Abstral, which delivers fentany via a sublingual route.
By Indication
Pain management remains the leading indication with nearly 40% share, driven by the need for fast relief and convenient dosing options. Thin-film formats help avoid swallowing difficulties, which supports their preference in acute and chronic pain cases. Neurological disorders show solid adoption due to improved onset time and reduced first-pass metabolism. Nausea and vomiting treatments benefit from easy administration during active symptoms. Opioid dependence films rise with the wider use of buprenorphine-based therapies, while other categories expand through vitamin and dental-care formulations.
- For instance, Abstral is a fentanyl sublingual tablet used in the management of breakthrough pain in adult cancer patients who are already receiving and are tolerant to around-the-clock opioid therapy. It is available in multiple strengths, ranging from 100 µg to 800 µg, including a 200 µg tablet, and is formulated for rapid onset of pain relief.
By Distribution Channel
Retail pharmacies dominate this segment with around 52% market share, supported by high patient footfall and broad accessibility of prescription and OTC thin-film drugs. Hospital pharmacies follow due to strong use in acute care and emergency settings where rapid-action dosing is needed. Online pharmacies grow at a faster pace as users shift toward home-delivery and subscription-based medication models. The rise of e-pharmacy regulation and digital prescriptions boosts adoption. Overall demand is driven by greater patient awareness and expanding availability of thin-film formulations across channels.
Key Growth Drivers
Rising Demand for Rapid-Onset Drug Delivery
Growing demand for fast-acting therapies drives strong adoption of oral thin film drugs. Patients prefer these films because they dissolve quickly and deliver active molecules directly into systemic circulation. This bypass of first-pass metabolism improves therapeutic effect and reduces dose load. The benefit supports wide use in pain, migraine, allergy, and nausea treatment. Healthcare providers value predictable onset time and ease of administration in non-hospital settings. Growth also comes from rising need for effective options for patients with swallowing issues. These advantages help thin film formats outperform many traditional oral dosage forms.
- For instance, Aquestive Therapeutics’ PharmFilm® platform supports rapid-onset delivery, demonstrated by Sympazan®, an oral film delivering 5 mg, 10 mg, and 20 mg clobazam, engineered to achieve therapeutic plasma levels without swallowing tablets.
Expanding Use in Chronic Disease Management
Chronic conditions require adherence, and thin film drugs improve patient compliance. The format supports simple dosing, which helps long-term treatment. Buccal and sublingual films serve neurological disorders, opioid dependence, and hormonal therapy with better accuracy. Their portability strengthens adoption among active adults. Growth also rises from wider integration of thin film versions of established molecules. Drug makers reformulate trusted drugs to enhance patient experience and extend brand value. Continued innovation in polymer design boosts stability, allowing films to suit complex molecules. This strengthens long-term growth across chronic care.
- For instance, Endo Pharmaceuticals’ BELBUCA® buprenorphine buccal film (using BEMA® technology) was titrated in a long-term safety study across 506 chronic pain patients up to a dose of 900 µg every 12 hours, and 158 patients (36.3%) completed 48 weeks with stable pain scores around 3–4/10.
Growing Pediatric and Geriatric Patient Need
Pediatric and elderly groups face difficulty swallowing tablets, which strengthens thin film use. Fast dissolving films remove the need for water and reduce choking risk. Caregivers prefer controlled dosing, simple handling, and better taste masking. These benefits increase adoption in vitamins, antiallergy drugs, antiemetics, and neurological therapies. Hospitals use thin films for patients with reduced mobility or severe nausea. Manufacturers design age-friendly formulations with improved mouthfeel and stable packaging. Global aging boosts demand for practical dose formats. Combined, these factors push strong growth in patient-centric medicine.
Key Trend & Opportunity
Expansion of High-Potency and Biologics-Compatible Films
Thin film technologies advance toward high-potency molecules and small biologics. New polymer blends improve loading capacity and maintain drug stability. This allows delivery of complex APIs that previously required injections. Companies explore peptide and small-protein films for chronic diseases. Increased interest in non-invasive alternatives supports these innovations. Research teams test bioadhesive designs that enhance residence time and improve absorption. These improvements open opportunities for competitive drug reformulation. The trend encourages partnerships between film specialists and major pharma companies. Wider acceptance from regulators supports growth.
- For instance, CD Formulation has developed an oral thin film protein/peptide delivery platform capable of incorporating fragile biologics: they report using solvent-casting or 3D printing to embed peptides or proteins in films while maintaining structural stability, even for macromolecules of dozens of amino acids.
Growth of Digital and Home-Based Treatment Models
Digital health adoption expands use of oral thin films across home-care settings. Patients prefer films that enable self-management without complex dosing steps. Online pharmacies promote film-based drugs through subscription plans. Growth in telemedicine boosts remote prescription volume. Drug makers explore smart packaging for adherence tracking. This trend supports personalized treatments with flexible dosage control. Home therapy demand rises in nausea, neurological disorders, and opioid dependence care. Stable shelf life and portable design help thin films fit digital-first healthcare ecosystems. These shifts strengthen long-term market opportunity.
- For instance, Indivior launched a mobile app to support patients on SUBOXONE® Film, offering education, medication reminders, and tracking the film itself is packaged in unit-dose child-resistant pouches, aiding safe home administration.
Reformulation Strategy to Extend Product Lifecycle
Pharma companies reformulate existing APIs into thin films to extend market value. This strategy helps reduce development risk because the safety profile is known. Fast development cycles make thin films attractive for competitive markets. Many firms use this approach for pain, allergy, and antiemetic therapies. Reformulation supports product differentiation while meeting patient-centric care needs. New films with improved taste and rapid onset help brands gain loyalty. Increased investment in polymer engineering supports this opportunity. Growth continues as companies shift focus toward lifecycle management.
Key Challenge
Limited Drug Load and Molecular Compatibility
Thin film technologies face constraints on drug load capacity. Some molecules require higher strength than films can safely carry. Large biologics and unstable compounds struggle with rapid degradation in film matrices. These limits slow development for high-dose therapies. Manufacturers work on advanced polymers, yet progress remains gradual. Compatibility issues increase formulation cost and time. Small firms find these steps expensive, reducing innovation pace. These barriers make thin film use more suitable for potent low-dose drugs. This challenge restricts adoption across several therapeutic classes.
Stringent Quality, Packaging, and Stability Requirements
Thin films require strict control of moisture, temperature, and packaging to maintain stability. Small changes affect dissolution, strength, and dose uniformity. Regulatory authorities demand extensive analytical testing and stability data. These requirements slow approvals and raise production costs. Packaging design also adds complexity because films need protection from humidity. Manufacturers must invest in specialized machinery and controlled environments. Small producers struggle with this expense. These factors limit new entrants and reduce overall market speed. The challenge affects global scalability of new thin film drugs.
Regional Analysis
North America
North America leads the Oral Thin Film Drugs market with about 41% share due to strong uptake of sublingual and fast-dissolving formulations in pain, neurological, and opioid-dependence care. High prescription volume, mature reimbursement systems, and broad acceptance of patient-centric dosage forms support regional leadership. The U.S. dominates because of strong innovation activity, early adoption of reformulated drugs, and rising demand in pediatric and geriatric groups. Canada adds stable growth through expanding hospital and retail pharmacy usage. Overall demand strengthens with increased focus on rapid-onset therapies and home-based care.
Europe
Europe holds nearly 28% share in the Oral Thin Film Drugs market, driven by rising preference for non-invasive dosage forms and strong adoption in chronic disease management. Germany, the UK, and France lead regional demand due to advanced pharmaceutical R&D and strong regulatory support for patient-friendly formulations. Aging population trends push thin-film use in neurological and pain-management therapies. Retail pharmacies account for major distribution, while hospital pharmacies expand use for acute-care settings. Growing acceptance of buccal and sublingual films supports steady market expansion across Western and Northern Europe.
Asia-Pacific
Asia-Pacific accounts for roughly 22% share and represents the fastest-growing region in the Oral Thin Film Drugs market. Rising healthcare access in China and India, along with growing pediatric and geriatric populations, strengthens demand for easy-to-administer dosage forms. Japan leads regional adoption due to early acceptance of fast-dissolving films in allergy, nausea, and neurological care. Expanding e-pharmacy penetration accelerates uptake across emerging markets. Local manufacturers increasingly produce cost-effective thin films, improving availability. These factors position Asia-Pacific as a high-growth region with strong long-term potential.
Latin America
Latin America holds about 6% share, supported by rising demand for simple, rapid-acting formulations in pain, nausea, and vitamin deficiency management. Brazil and Mexico dominate the regional market due to wider pharmacy networks and improving access to chronic-care treatments. Adoption strengthens as thin films serve patients with swallowing challenges and support home-care routines. Increasing distribution through retail and online pharmacies supports growth. Although regulatory pathways remain slower than major regions, investment from international drug makers is expanding availability of sublingual and fast-dissolving film products.
Middle East & Africa
The Middle East & Africa region holds nearly 3% share in the Oral Thin Film Drugs market, driven by growing investment in healthcare modernization and better access to chronic-disease therapies. Gulf countries such as the UAE and Saudi Arabia show stronger adoption due to improved healthcare spending and rapid procurement of innovative dosage formats. Demand rises in pediatric and geriatric care, where thin films offer easier administration. In Africa, growth remains gradual but improves with expanding pharmacy networks and international partnerships. The region shows long-term potential as awareness of patient-friendly formulations increases.
Market Segmentations:
By Product Type
- Sublingual Film
- Fast Dissolving Oral Film
- Buccal Film
By Indication
- Pain Management
- Neurological Disorders
- Nausea & Vomiting
- Opioid Dependence
- Others (Oral & Dental Care, Vitamin deficiency etc.)
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Oral Thin Film Drugs market includes key participants such as Cure Pharmaceutical, Nova Thin Film Pharmaceuticals LLC, ARx LLC, Viatris Inc., C.L. Pharm, CD Formulation, Corium Innovations Inc., ZIM LABORATORIES LIMITED, Aquestive Therapeutics Inc., and LTS Lohmann Therapie-Systeme AG. These companies compete by advancing polymer science, enhancing drug-loading capacity, and improving taste-masking technologies to strengthen patient compliance. Many firms invest in reformulating high-value APIs into sublingual, buccal, and fast-dissolving films to extend product lifecycles and gain regulatory traction. Strategic partnerships with major pharmaceutical manufacturers help expand portfolios and global reach, while R&D efforts focus on chronic-disease products and pediatric-friendly formulations. Growing emphasis on manufacturing automation, stability control, and moisture-resistant packaging further shapes competition.
Key Player Analysis
- Cure Pharmaceutical
- Nova Thin Film Pharmaceuticals LLC
- ARx, LLC.
- Viatris Inc.
- L. Pharm
- CD Formulation
- Corium Innovations, Inc.
- ZIM LABORATORIES LIMITED
- Aquestive Therapeutics, Inc.
- LTS Lohmann Therapie-Systeme AG
Recent Developments
- In June 2025, Aquestive Therapeutics, Inc. announced that the U.S. Food and Drug Administration (FDA) had accepted the company’s New Drug Application (NDA) for Anaphylm (epinephrine) Sublingual Film for the treatment of Type 1 allergic reactions, including anaphylaxis, and has assigned a Prescription Drug User Fee Act (PDUFA) target action date of January 31, 2026.
- In April 2025, ZIM Laboratories Limited entered into Dossier License, Product Supply, and Technology Know-How License Agreement with Globalpharma Co. (L.L.C.). As per the agreement terms, ZIM labs agreed to license its proprietary Oral Thin Film technology platform, ThinOral with Globalpharma, under which the latter firm would register and sell 10 OTF-based Pharmaceutical and Nutraceutical products suitable for GCC region patient needs.
- In September 2024, Viatris Inc. launched (Pr)Viagra ODF in Canada, introducing a new sildenafil oral dissolving film formulation that offers an alternative to conventional tablets for erectile dysfunction and expands the commercial use of ODF technology.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Indication, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of thin film formulations will rise as demand grows for fast-acting therapies.
- Sublingual and buccal films will gain wider use in chronic disease care.
- Advances in polymer technology will support higher drug-loading capacity.
- Pediatric and geriatric treatments will expand due to improved ease of use.
- More pharmaceutical companies will reformulate existing drugs into thin film formats.
- Digital health and online pharmacies will accelerate home-based medication use.
- Taste-masking and stability improvements will strengthen product acceptance.
- Emerging markets in Asia-Pacific will drive strong new demand for thin films.
- Regulatory approval pathways will become clearer, enabling faster product launches.
- Strategic partnerships between film specialists and major pharma firms will increase global reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid-Onset Drug Delivery Preference
Oral thin film drugs offer fast dissolution and absorption, bypassing first-pass metabolism and providing immediate therapeutic effects, which is especially valued in pain, migraine, and emergency care settings.
Improved Compliance for Pediatric and Geriatric Patients
Thin film formats are easier to administer for children and elderly patients who have difficulty swallowing tablets, leading to higher adherence and broader adoption in these demographics.
Expansion in Chronic Disease Management
The convenience and dosing accuracy of sublingual and buccal films make them increasingly popular for long-term management of chronic conditions such as neurological disorders and opioid dependence.
Advancements in Polymer and Taste-Masking Technologies
Ongoing innovation in film-forming polymers and taste-masking techniques enhances drug stability, patient acceptability, and enables the delivery of a wider range of active pharmaceutical ingredients.
Growth of Digital Health and E-Pharmacy Channels
The rise of online pharmacies and telemedicine is making oral thin film drugs more accessible for home-based care, supporting market expansion through convenient distribution and improved patient engagement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Oral Thin Film Drugs market, and what is its projected size in 2032?
t what Compound Annual Growth Rate is the Oral Thin Film Drugs market projected to grow between 2025 and 2032?
What is the Oral Thin Film Drugs Market CAGR?
Who are the major players in this market?
Who are the leading companies in the Oral Thin Film Drugs market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Indication
- 1.2.1 Pain Management
- 1.2.2 Neurological Disorders
- 1.2.3 Nausea & Vomiting
- 1.2.4 Opioid Dependence
- 1.2.5 Others (Oral & Dental Care, Vitamin Deficiency, etc.)
- 1.3 By Product Type
- 1.3.1 Sublingual Film
- 1.3.2 Fast Dissolving Oral Film
- 1.3.3 Buccal Film
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.02 billion → 2032: USD 6.18 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Oral Thin Film Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Oral Thin Film Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Oral Thin Film Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Oral Thin Film Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Oral Thin Film Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Oral Thin Film Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Oral Thin Film Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Oral Thin Film Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.02 billion → 2032: USD 6.18 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Oral Thin Film Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Indication - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pain Management
- 12.3.7.2 Neurological Disorders
- 12.3.7.3 Nausea & Vomiting
- 12.3.7.4 Opioid Dependence
- 12.3.7.5 Others (Oral & Dental Care, Vitamin Deficiency, etc.)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sublingual Film
- 12.4.7.2 Fast Dissolving Oral Film
- 12.4.7.3 Buccal Film
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Oral Thin Film Drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Oral Thin Film Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Oral Thin Film Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Cure Pharmaceutical
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Nova Thin Film Pharmaceuticals LLC
- 17.4 ARx LLC
- 17.5 Viatris Inc.
- 17.6 C.L. Pharm
- 17.7 CD Formulation
- 17.8 Corium Innovations Inc.
- 17.9 ZIM LABORATORIES LIMITED
- 17.10 Aquestive Therapeutics Inc.
- 17.11 LTS Lohmann Therapie-Systeme AG
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

