
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia Conveyor Belt Market Size 2023 | USD 386.68 million |
| Australia Conveyor Belt Market, CAGR | 4.82% |
| Australia Conveyor Belt Market Size 2032 | USD 593.46 million |
Market Overview
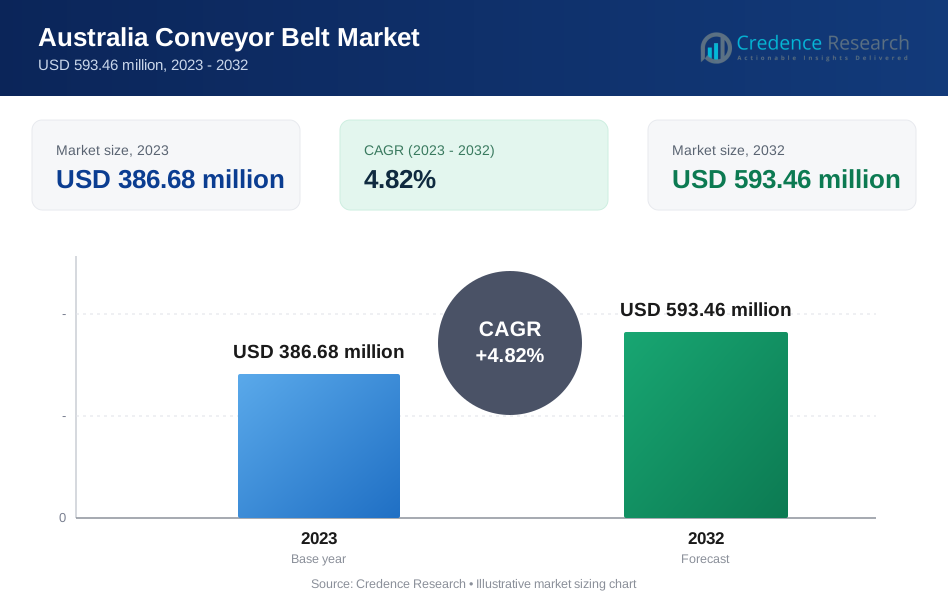
The Australia Conveyor Belt Market is projected to grow from USD 386.68 million in 2023 to an estimated USD 593.46 million by 2032, with a compound annual growth rate (CAGR) of 4.82% from 2024 to 2032. This robust growth is driven by the increasing demand for conveyor belts across various industries, including mining, manufacturing, and logistics.
Several key factors drive the growth of the conveyor belt market in Australia. The mining industry's resurgence, coupled with the rising adoption of automation in manufacturing processes, significantly boosts the demand for conveyor belts. Moreover, the growing logistics and warehousing sector, driven by e-commerce growth, necessitates efficient material handling solutions, thus propelling market growth. Trends such as the integration of IoT and smart conveyor systems are also shaping the market, providing enhanced operational efficiency and predictive maintenance capabilities.
Geographically, the market sees substantial demand from regions such as New South Wales and Western Australia, primarily due to their extensive mining activities. Additionally, the industrial hubs in Victoria and Queensland contribute significantly to market demand. Key players in the Australia Conveyor Belt Market include BHP Group, Fenner Dunlop, and ContiTech Australia, who continuously innovate to meet the evolving needs of various end-use industries. These companies focus on expanding their product portfolios and enhancing their technological capabilities to maintain a competitive edge in the market.
Market Drivers
Resurgence of the Mining Industry
The resurgence of the mining industry is a primary driver for the growth of the Australia conveyor belt market. Australia is a global leader in the production of minerals such as iron ore, coal, gold, and lithium, among others. The increasing demand for these minerals on both domestic and international fronts necessitates efficient and reliable material handling systems, with conveyor belts being a critical component. For instance, mining contributed a record $455 billion in export revenue for Australia in the 2022-23 financial year. The expansion of existing mines and the establishment of new mining projects drive the demand for high-performance conveyor belts capable of handling large volumes of materials. Additionally, mining companies are investing heavily in automation and advanced conveyor belt systems to enhance productivity and reduce operational costs. This push towards modernization and efficiency in the mining sector significantly boosts the demand for conveyor belts in Australia.
Adoption of Automation in Manufacturing
The growing adoption of automation in the manufacturing sector is another key driver of the conveyor belt market in Australia. Industries are increasingly leveraging automation to streamline their operations, improve efficiency, and reduce labor costs. Conveyor belts are integral to automated manufacturing processes, facilitating the seamless movement of materials and products across different stages of production. The automotive, food and beverage, pharmaceuticals, and packaging industries, in particular, are adopting automated conveyor systems to meet the demands of high-speed production and stringent quality standards. The integration of advanced technologies such as robotics, artificial intelligence, and IoT with conveyor belt systems enables real-time monitoring, predictive maintenance, and enhanced operational control. As manufacturers continue to prioritize automation to stay competitive, the demand for sophisticated conveyor belt systems is expected to rise steadily.
Growth of the E-commerce and Logistics Sector
The rapid growth of the e-commerce and logistics sector significantly drives the demand for conveyor belts in Australia. The rise of online shopping has led to a surge in the need for efficient warehousing and distribution systems to handle the increased volume of goods. For instance, over nine million Australian households made online purchases in 2022, with expenditure rising during sales events, such as the cyber sales period. Conveyor belts play a vital role in modern logistics facilities, aiding in the efficient sorting, handling, and transportation of packages. The expansion of e-commerce giants and the establishment of new fulfillment centers across Australia create substantial opportunities for the conveyor belt market. Additionally, advancements in conveyor belt technology, such as the development of modular and flexible conveyor systems, cater to the dynamic needs of the logistics sector. These systems offer scalability, adaptability, and improved throughput, making them indispensable for efficient supply chain management. As the e-commerce and logistics sector continues to expand, the demand for advanced conveyor belt solutions is expected to witness significant growth.
Technological Advancements and Innovation
Technological advancements and continuous innovation in conveyor belt systems are crucial drivers of market growth. Manufacturers are investing in research and development to introduce conveyor belts with enhanced features such as improved durability, energy efficiency, and operational flexibility. The development of smart conveyor systems equipped with sensors, IoT connectivity, and automation capabilities is revolutionizing the industry. These smart systems enable real-time monitoring, predictive maintenance, and data-driven decision-making, enhancing overall operational efficiency and reducing downtime. Moreover, the shift towards environmentally friendly and sustainable conveyor belt solutions is gaining traction. The introduction of energy-efficient conveyor belts and the use of eco-friendly materials align with the growing emphasis on sustainability and environmental conservation. Technological advancements also include the development of specialized conveyor belts tailored for specific applications, such as high-temperature belts for the steel industry and food-grade belts for the food and beverage sector. As technological innovation continues to shape the industry, the demand for advanced and high-performance conveyor belt systems is expected to grow.
Market Trends
Integration of Smart Technologies
The integration of smart technologies is a significant trend shaping the Australia conveyor belt market. The adoption of Industry 4.0 principles has led to the development and implementation of smart conveyor systems that leverage advanced technologies such as the Internet of Things (IoT), artificial intelligence (AI), and machine learning (ML). These systems are equipped with sensors and IoT connectivity, enabling real-time monitoring and data collection on various operational parameters such as belt speed, temperature, load, and wear and tear. For instance, Fenner Dunlop’s iBelt intelligent conveyor solution is increasing productivity and giving customers real-time transparency of their plant’s performance with predictive analytics and other insights. The collected data is analyzed using AI and ML algorithms to provide predictive maintenance insights, optimizing the performance and lifespan of conveyor belts. This proactive approach to maintenance reduces downtime, prevents unexpected failures, and enhances overall operational efficiency. Additionally, smart conveyor systems can be integrated with centralized control systems, allowing for remote monitoring and control, which is particularly beneficial for industries with extensive and complex material handling needs, such as mining and logistics.
Emphasis on Sustainability and Energy Efficiency
Another prominent trend in the Australia conveyor belt market is the growing emphasis on sustainability and energy efficiency. As environmental concerns and regulatory pressures increase, industries are prioritizing the development and adoption of eco-friendly conveyor belt solutions. Manufacturers are focusing on creating conveyor belts made from sustainable and recyclable materials to reduce their environmental footprint. Moreover, there is a significant push towards improving the energy efficiency of conveyor belt systems. Innovations such as low-energy belts, which reduce energy consumption during operation, are gaining popularity. These belts are designed to minimize friction and require less power to operate, leading to substantial energy savings. Additionally, conveyor systems are being equipped with energy-efficient motors and drives that optimize power usage. For instance, a solution for this comes in the form of a variable frequency drive (VFD), which is used to regulate the speed of the conveyor and adjust it to meet production needs in real-time. This trend towards sustainability is further driven by the demand from end-users who seek to enhance their corporate social responsibility (CSR) profiles and comply with stringent environmental regulations. As a result, the market is witnessing increased investments in research and development to introduce conveyor belt systems that align with sustainable practices while maintaining high performance and durability.
Market Restraints and Challenges
High Initial Costs and Maintenance Expenses
One of the primary restraints in the Australia conveyor belt market is the high initial cost associated with the installation of advanced conveyor belt systems. These costs include not only the purchase price of the conveyor belts but also the expenses related to installation, integration with existing systems, and initial setup. Advanced technologies, such as smart conveyor belts equipped with IoT and AI capabilities, further escalate these costs. Additionally, maintaining these systems can be expensive due to the need for specialized technicians, regular maintenance checks, and the potential for costly repairs or replacements of parts. Small and medium-sized enterprises (SMEs), in particular, may find it challenging to invest in such high-cost systems, limiting market penetration and adoption rates. The financial burden of these expenses can deter companies from upgrading or expanding their conveyor belt infrastructure, thereby restraining market growth.
Environmental and Regulatory Compliance
Another significant challenge in the Australia conveyor belt market is meeting stringent environmental and regulatory compliance standards. Conveyor belt manufacturers must adhere to rigorous regulations regarding emissions, waste management, and the use of sustainable materials. The push towards eco-friendly solutions necessitates significant research and development efforts to create products that meet these standards, which can be both time-consuming and costly. Additionally, navigating the complex regulatory landscape requires substantial expertise and resources, potentially diverting focus from core business operations. Non-compliance can result in hefty fines, legal repercussions, and damage to a company’s reputation. Moreover, the shift towards sustainable practices demands the adoption of new technologies and processes, which may face resistance from industries accustomed to traditional methods. These regulatory and environmental challenges pose a considerable barrier to market entry for new players and can slow down the pace of innovation and development within the market.
Market Segmentation Analysis
By Type
Crescent belts, known for their flexibility and ability to handle various materials, are widely used in food processing and packaging industries, especially for delicate items. Floor belts facilitate efficient movement within manufacturing and assembly lines, ensuring continuous workflows in industrial settings. Overhead belts, ideal for industries with limited floor space, are prevalent in automotive assembly lines and warehousing, transporting products above ground level. Pallet belts, designed for heavy loads, are essential in distribution centers and warehouses for moving large items like pallets and containers. Roller belts, versatile and commonly used in retail and logistics, are perfect for sorting and packaging lines, providing a fixed path for item movement.
By Belt Type
Heavy-weight conveyor belts are designed for high-load applications like mining and quarrying, offering superior strength and durability to withstand harsh working conditions and heavy material loads. Medium-weight belts cater to applications requiring moderate load handling, such as manufacturing and processing plants, balancing strength and flexibility for various industrial uses. Lightweight conveyor belts are essential in industries such as food processing and pharmaceuticals, where precision and gentle handling are critical, and are designed for speed and efficiency with minimal wear and tear.
Segments
Based on Type
- Crescent Belts
- Floor Belts
- Overhead Belts
- Pallet Belts
- Roller Belts
Based on Belt Type
- Heavy-Weight Belts
- Medium-Weight Belts
- Lightweight Belts
Based on Material
- Polymers
- Metals
Based on Installation
- Stationary Belts
- Portable Belts
Based on End User
- Automotive
- Retail
- Industrial
- Poultry & Dairy
- Others
Based on Region
- New South Wales
- Western Australia
- Victoria and Queensland
Regional Analysis
New South Wales (25%):
New South Wales (NSW) holds a substantial share of the Australia conveyor belt market, accounting for approximately 25% of the market. This region is a major industrial hub with diverse activities ranging from manufacturing to logistics and warehousing. Sydney, the capital city, is a focal point for industrial and commercial operations, requiring efficient material handling solutions. The growth in e-commerce and retail sectors in NSW further boosts the demand for conveyor belts, particularly for sorting and distribution applications. Additionally, NSW's robust infrastructure and continuous investment in industrial development contribute to the steady demand for conveyor belt systems.
Western Australia (30%):
Western Australia is a key player in the Australia conveyor belt market, commanding around 30% of the market share. The region is renowned for its extensive mining activities, particularly in iron ore and gold mining. The harsh and demanding mining environment in Western Australia necessitates the use of durable and high-performance conveyor belts capable of handling large volumes of raw materials. The mining sector's continuous expansion and the development of new mining projects drive the substantial demand for conveyor belts in this region. Moreover, Western Australia's focus on automation and modernization of mining operations further propels the market growth.
Victoria (20%):
Victoria contributes approximately 20% to the Australia conveyor belt market. The state's diversified industrial base, which includes automotive manufacturing, food processing, and packaging industries, drives the demand for conveyor belts. Melbourne, the state capital, is a significant industrial and commercial center, fostering a high demand for efficient material handling solutions. The increasing adoption of automation in manufacturing processes and the growth of the logistics sector in Victoria further bolster the demand for advanced conveyor belt systems. The state's strategic investments in industrial development and infrastructure projects also play a crucial role in sustaining market growth.
Key players
- Daifuku Co. Ltd
- Murata Machinery, Ltd.
- SSI Schaefer AG
- KUKA AG (Swisslog AG)
- BEUMER Group
- KNAPP AG
- Honeywell Intelligrated Inc.
- Kardex Group
- Flexlink Systems, Inc.
Competitive Analysis
The Australia conveyor belt market is highly competitive, with key players such as Daifuku Co. Ltd, Murata Machinery, Ltd., and SSI Schaefer AG leading the industry. These companies are renowned for their innovative conveyor solutions and advanced automation technologies. KUKA AG (Swisslog AG) and BEUMER Group focus on integrating smart technologies like IoT and AI into their systems, enhancing operational efficiency and predictive maintenance capabilities. KNAPP AG and Honeywell Intelligrated Inc. emphasize customized solutions to cater to specific industry needs, particularly in e-commerce and logistics. Kardex Group and Flexlink Systems, Inc. leverage their expertise in modular conveyor systems, providing flexible and scalable solutions for various industrial applications. The competitive landscape is characterized by continuous innovation, strategic partnerships, and a strong focus on sustainable and energy-efficient solutions, ensuring these companies maintain their market leadership while addressing the evolving demands of the industry.
Recent Developments
In May 2022, Dunlop Conveyor Belting introduced the OptimaHeat Xtreme, a groundbreaking heat-resistant belt. This innovation represents the first truly novel heat-resistant belt design available to industrial users. Developed in collaboration with its sister company Dunlop of the United States, the OptimaHeat Xtreme is a revolutionary single-ply high heat-resistant belt. This new product aims to provide superior performance in high-temperature environments, setting a new standard in the industry. The introduction of the OptimaHeat Xtreme reflects Dunlop's commitment to innovation and meeting the evolving needs of industrial users.
In January 2023, Power, LLC acquired Dunham Rubber & Belting Corporation, enhancing its ability to serve various markets. This strategic acquisition allows Power, LLC to better meet the needs of the food processing, material handling, building products, pharmaceutical, and general industrial sectors. By integrating Dunham Rubber & Belting Corporation's expertise and resources, Power, LLC strengthens its market position and expands its product offerings. This acquisition underscores Power, LLC's commitment to growth and delivering comprehensive solutions to its customers across multiple industries.
In July 2022, Continental AG acquired WCCO Belting, Inc., a U.S.-based belting manufacturer. This acquisition bolsters Continental AG's conveyor solutions for the agricultural sector, enhancing its product portfolio and market reach. WCCO Belting, Inc.'s expertise in manufacturing high-quality belts complements Continental's existing capabilities, allowing for improved service and innovation in the agricultural industry. This strategic move aligns with Continental AG's goal of expanding its influence and providing advanced solutions to meet the specific needs of agricultural applications.
In April 2021, Marubeni Corporation acquired Remacan Industries Inc., a conveyor belt distribution business based in Ontario, Canada. This acquisition was conducted through Marubeni’s subsidiary, Belterra Corporation. The integration of Remacan Industries enhances Marubeni's distribution capabilities and strengthens its presence in the North American market. By acquiring Remacan Industries, Marubeni Corporation aims to provide comprehensive conveyor belt solutions and improve service delivery to its customers in the region. This acquisition supports Marubeni's strategy of expanding its global footprint and reinforcing its position in the conveyor belt industry.
Market Concentration and Characteristics
The Australia conveyor belt market exhibits moderate market concentration, with a mix of established global players and regional manufacturers contributing to the competitive landscape. Key characteristics of this market include a strong emphasis on technological innovation, driven by the integration of smart technologies such as IoT and AI to enhance operational efficiency and predictive maintenance. The market is also characterized by a growing focus on sustainability and energy efficiency, with manufacturers developing eco-friendly and energy-saving conveyor belt solutions. Additionally, the market caters to diverse industries, including mining, manufacturing, logistics, and food processing, each requiring specialized conveyor belt systems to meet specific operational needs.
Report Coverage
The research report offers an in-depth analysis based on Type, Belt Type, Material, Installation, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The integration of IoT, AI, and machine learning will drive innovation in smart conveyor belt systems, enhancing efficiency and predictive maintenance capabilities.
- Increasing environmental regulations will push manufacturers to develop eco-friendly and energy-efficient conveyor belts, aligning with global sustainability goals.
- Continued investment in mining projects will boost demand for robust and high-performance conveyor belts, essential for handling heavy materials in harsh environments.
- The trend towards automation will continue to drive the adoption of advanced conveyor belt systems, optimizing production processes and reducing labor costs.
- The rapid growth of e-commerce will increase the need for efficient material handling solutions in logistics and warehousing, propelling the demand for conveyor belts.
- There will be a growing demand for customized conveyor belt solutions that cater to specific industry needs, offering flexibility and scalability.
- Companies will invest more in research and development to create innovative conveyor belt technologies, addressing emerging challenges and improving performance.
- Manufacturers will explore new markets within Australia, focusing on regional areas with growing industrial activities to expand their customer base.
- The market will witness heightened competition among key players, driving strategic partnerships, mergers, and acquisitions to enhance market presence and capabilities.
- Stricter safety and quality regulations will necessitate the development of advanced conveyor belts that comply with industry standards, ensuring operational safety and reliability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Resurgence of the Mining Industry
Australia's mining sector is expanding, with increased production of minerals such as iron ore, coal, and lithium. This drives demand for high-performance conveyor belts capable of handling large volumes and harsh conditions, as mining companies invest in automation and modernization.
Adoption of Automation in Manufacturing
Manufacturers in Australia are increasingly automating production lines to improve efficiency and reduce labor costs. Conveyor belts are integral to these automated systems, especially in industries like automotive, food and beverage, and pharmaceuticals, fueling market growth.
Growth of E-commerce and Logistics
The rapid rise of e-commerce in Australia has led to a surge in logistics and warehousing activities. Conveyor belts are essential for efficient sorting, handling, and transportation of goods in fulfillment centers, driving demand in the logistics sector.
Technological Advancements and Innovation
Manufacturers are developing smart conveyor systems with IoT, AI, and predictive maintenance capabilities. These innovations improve operational efficiency, reduce downtime, and align with industry trends toward automation and data-driven management.
Emphasis on Sustainability and Energy Efficiency
Increasing regulatory and customer focus on sustainability is pushing manufacturers to develop eco-friendly and energy-efficient conveyor belts. This includes the use of recyclable materials and energy-saving technologies, supporting both compliance and corporate social responsibility goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Australia conveyor belt market?
What are the key drivers of the conveyor belt market in Australia?
How does the mining industry impact the conveyor belt market in Australia?
What role does automation play in the conveyor belt market?
Which regions in Australia have the highest demand for conveyor belts?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Crescent Belts
- 1.2.2 Floor Belts
- 1.2.3 Overhead Belts
- 1.2.4 Pallet Belts
- 1.2.5 Roller Belts
- 1.3 By End User
- 1.3.1 Automotive
- 1.3.2 Retail
- 1.3.3 Industrial
- 1.3.4 Poultry & Dairy
- 1.3.5 Others
- 1.4 By Material
- 1.4.1 Polymers
- 1.4.2 Metals
- 1.5 By Belt Type
- 1.5.1 Heavy-Weight Belts
- 1.5.2 Medium-Weight Belts
- 1.5.3 Lightweight Belts
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 386.68 million → 2032: USD 593.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Conveyor Belt Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Conveyor Belt Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Conveyor Belt Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Conveyor Belt Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Conveyor Belt Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Conveyor Belt Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Conveyor Belt Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Conveyor Belt Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 386.68 million → 2032: USD 593.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Conveyor Belt Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Crescent Belts
- 12.3.7.2 Floor Belts
- 12.3.7.3 Overhead Belts
- 12.3.7.4 Pallet Belts
- 12.3.7.5 Roller Belts
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Retail
- 12.4.7.3 Industrial
- 12.4.7.4 Poultry & Dairy
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Polymers
- 12.5.7.2 Metals
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Belt Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Heavy-Weight Belts
- 12.6.7.2 Medium-Weight Belts
- 12.6.7.3 Lightweight Belts
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Conveyor Belt End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Conveyor Belt Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Conveyor Belt Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Conveyor Belt Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Daifuku Co. Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Murata Machinery, Ltd.
- 18.4 SSI Schaefer AG
- 18.5 KUKA AG (Swisslog AG)
- 18.6 BEUMER Group
- 18.7 KNAPP AG
- 18.8 Honeywell Intelligrated Inc.
- 18.9 Kardex Group
- 18.10 Flexlink Systems, Inc.
- 18.11 Fenner Dunlop
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

