
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia Diabetes Care Devices Market Size 2024 | USD 188.49 Million |
| Australia Diabetes Care Devices Market, CAGR | 9.12% |
| Australia Diabetes Care Devices Market Size 2032 | USD 427.95 Million |
Market Overview
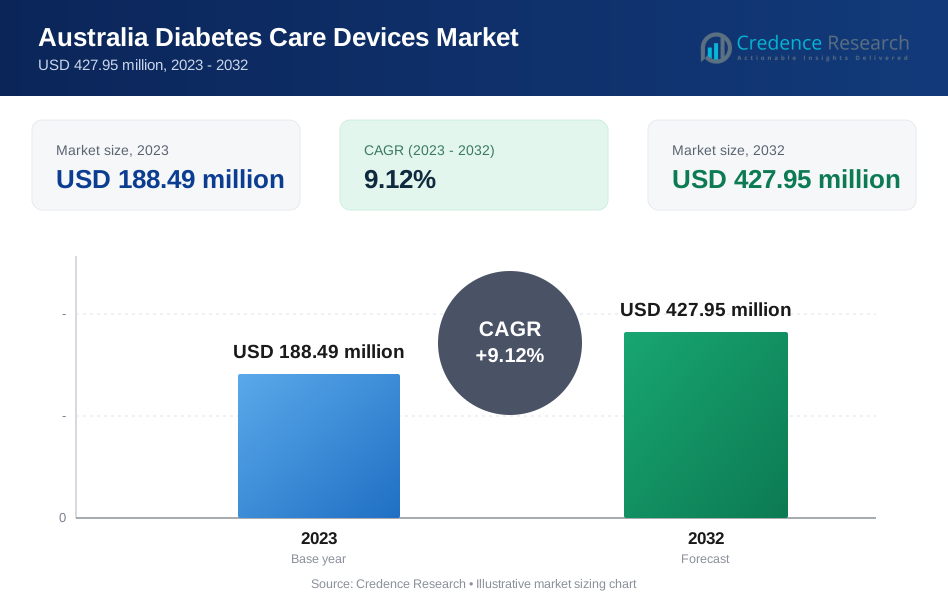
The Australia Diabetes Care Devices Market is projected to grow from USD 188.49 million in 2023 to USD 427.95 million by 2032, expanding at a CAGR of 9.12%.
The Australia Diabetes Care Devices market is driven by the rising prevalence of diabetes, increasing healthcare awareness, and advancements in diabetes management technologies. The growing demand for more efficient and user-friendly devices, such as continuous glucose monitoring (CGM) systems and insulin pumps, is further fueling market growth. Additionally, the adoption of telemedicine and digital health solutions for remote monitoring and personalized care is gaining momentum. Technological innovations, including smart insulin pens and connected devices, are enhancing patient convenience and treatment outcomes. The Australian government's supportive initiatives for chronic disease management and the integration of diabetes care devices into healthcare systems are also contributing to the market’s expansion. With a strong focus on improving patient quality of life, these trends are expected to continue shaping the market in the coming years, offering substantial growth opportunities for manufacturers and stakeholders in the diabetes care sector.
The Australian diabetes care devices market is characterized by the presence of both global and regional players driving innovation and market growth. Key players in the market include Abbott Laboratories, known for its continuous glucose monitoring systems; ACON Laboratories, Inc. and Ascensia Diabetes Care Holdings AG, which offer a range of blood glucose meters and test strips. Becton, Dickinson and Company and Medtronic plc are major contributors with their insulin pumps and advanced diabetes management solutions. Dexcom, Inc. is recognized for its CGM systems, while F. Hoffmann-La Roche Ltd and Johnson & Johnson offer a wide array of glucose monitoring and insulin delivery devices. Novo Nordisk A/S plays a significant role in the insulin delivery segment, and YPSOMED specializes in insulin pens and other delivery solutions. These companies, along with their ongoing product innovations, help shape the competitive landscape in Australia’s diabetes care device market.
Market Insights
- The Australian diabetes care devices market was valued at USD 188.49 million in 2023 and is expected to reach USD 427.95 million by 2032, growing at a CAGR of 9.12%.
- The increasing prevalence of diabetes, especially type 2, is driving demand for advanced diabetes care devices.
- Government subsidies and reimbursement policies are making diabetes devices more accessible to patients.
- Technological advancements, including continuous glucose monitors and insulin pumps, are enhancing diabetes management.
- High device costs and complex reimbursement systems are key challenges for market growth.
- Limited access to specialized diabetes care in certain regions hinders optimal device usage.
- New South Wales and Victoria are major contributors to the market, with increased adoption of telehealth and diabetes management devices.
Market Drivers
Rising Prevalence of Diabetes
Australia has seen a significant rise in the number of individuals living with diabetes, both type 1 and type 2. This surge is driven by an aging population and increasing obesity rates, which are key risk factors for diabetes. As the number of affected individuals grows, the demand for effective diabetes management solutions, such as glucose monitoring devices and insulin delivery systems, is also rising. This increased patient population is a major factor propelling the demand for advanced diabetes care devices in Australia, further contributing to the market’s expansion.
Government Initiatives and Reimbursement Policies
The Australian government plays a crucial role in supporting diabetes care through various initiatives and reimbursement policies. Financial incentives and subsidies for diabetes devices, such as insulin pumps and continuous glucose monitoring (CGM) systems, make these technologies more accessible to patients. For instance, the National Diabetes Services Scheme (NDSS) provides subsidized products and support services to people with diabetes. In addition, the government allocates funding for diabetes education and management programs, ensuring that individuals with diabetes have access to comprehensive care. These initiatives are instrumental in driving the adoption of advanced diabetes care devices and stimulating market growth.
Technological Advancements
Continuous innovation in diabetes care technology has been a key driver in the market. Newer and more advanced devices, such as CGM systems, insulin pumps, and mobile health applications, offer more accurate, user-friendly, and efficient solutions for diabetes management. These innovations have not only improved the effectiveness of treatment but have also enhanced the overall quality of life for patients. As technology continues to evolve, it plays a pivotal role in addressing the growing demand for diabetes care solutions, improving patient outcomes, and supporting long-term management.
Increased Awareness and Patient Empowerment
As awareness of diabetes and its complications continues to grow, patients are becoming more proactive in managing their condition. This heightened awareness encourages individuals to embrace advanced devices and digital health tools that allow for better control over their diabetes. For instance, the National Diabetes Services Scheme (NDSS) offers comprehensive diabetes education and support programs to empower patients. Empowered patients are increasingly demanding innovative diabetes care solutions that provide greater autonomy and improve their daily management of the disease. This trend of patient empowerment is expected to drive ongoing demand for advanced diabetes care devices in Australia.
Telehealth and Remote Monitoring
The COVID-19 pandemic significantly accelerated the adoption of telehealth and remote monitoring solutions, which have become an integral part of diabetes care. Diabetes devices are now being integrated with telehealth platforms, enabling remote patient monitoring and virtual consultations. This integration enhances convenience and accessibility for patients, allowing them to receive continuous care and real-time feedback without the need for frequent in-person visits. As telehealth continues to evolve, it is expected to remain a prominent feature in the diabetes care landscape, further driving market growth.
Market Trends
Growing Prevalence of Diabetes and Government Support
The rising prevalence of diabetes, especially among the aging population, is a key trend driving the demand for diabetes care devices in Australia. Increasing rates of type 2 diabetes, fueled by sedentary lifestyles, poor diets, and other lifestyle factors, have significantly contributed to this surge. As the patient population grows, there is a pressing need for effective diabetes management solutions, such as continuous glucose monitoring (CGM) systems and insulin pumps. These devices are critical in helping individuals manage their condition more effectively. Additionally, the Australian government's initiatives and reimbursement policies play a pivotal role in making advanced diabetes care devices more accessible to patients. The government’s focus on supporting innovative healthcare solutions through funding and subsidies is enabling wider adoption of devices like CGM systems and insulin pumps, which are essential in managing diabetes effectively. Such measures are expected to drive significant growth in the diabetes care device market, improving both the affordability and availability of essential technologies.
Technological Advancements and Patient Empowerment
Technological advancements are revolutionizing the diabetes care landscape. Continuous glucose monitoring (CGM) systems have become indispensable tools for real-time monitoring, providing patients with precise data to make informed decisions about insulin dosing and dietary changes. Insulin pump therapy is another breakthrough, offering more accurate and consistent insulin delivery, which helps improve glycemic control and minimizes the risk of hypoglycemia. For instance, the Medtronic MiniMed™ 670G system, which functions like an artificial pancreas, has been a game changer in diabetes management. The integration of diabetes care devices with smartphones is also a growing trend, allowing for remote monitoring, data sharing with healthcare providers, and more personalized treatment plans. These technological innovations are not only enhancing the effectiveness of diabetes management but are also empowering patients to take control of their condition. Additionally, the ongoing focus on telehealth and remote monitoring-accelerated by the COVID-19 pandemic-has facilitated the use of diabetes devices in telemedicine settings. This trend provides patients with more convenience and flexibility in managing their diabetes, while healthcare providers can monitor patient progress and offer real-time guidance. Finally, patient empowerment is further supported by user-friendly devices and digital health tools, enabling individuals to make informed decisions and take an active role in their health. With growing awareness and efforts to focus on diabetes prevention and early detection, the market is well-positioned for continued growth, with long-term health outcomes benefiting from earlier diagnosis and better management strategies.
Market Challenges Analysis
High Cost and Complex Reimbursement Systems
The high cost of advanced diabetes care devices, such as continuous glucose monitoring (CGM) systems and insulin pumps, remains a significant barrier to widespread adoption in Australia. Although government subsidies and insurance coverage can mitigate some of the costs, many patients still face challenges in affording these devices. For instance, the Australian Institute of Health and Welfare reports that the annual cost of CGM devices can exceed AUD 5,000, making them financially out of reach for many. This financial burden can limit access to life-saving technology for a considerable portion of the population, particularly those without adequate insurance coverage or financial resources. Furthermore, the complexity of reimbursement systems adds another layer of difficulty. Reimbursement policies can vary across states and insurance providers, leading to inconsistencies in device availability and potential delays in access. Navigating these complex systems can be confusing for both healthcare providers and patients, which may result in unnecessary hurdles for individuals seeking the necessary treatment.
Device Complexity, Data Privacy, and Adherence Challenges
Advanced diabetes devices often come with a steep learning curve, requiring significant user training and education to ensure proper usage and accurate data interpretation. This is particularly challenging for older adults or individuals with limited technological literacy, who may struggle to fully understand how to use the devices effectively. Additionally, the increasing reliance on digital technologies in diabetes care raises concerns about data privacy and cybersecurity. Ensuring the security of patient data is essential for building trust and encouraging adoption of these technologies. With digital health tools becoming integral to diabetes management, protecting sensitive health information is more crucial than ever. Lastly, patient adherence to treatment plans and consistent device usage can be difficult, especially given factors such as device discomfort, sensor site reactions, and the psychological burden of managing diabetes. These barriers to adherence can negatively impact patient outcomes and limit the overall effectiveness of diabetes care devices.
Market Opportunities
Expansion of Telehealth and Remote Monitoring
The growing adoption of telehealth and remote monitoring offers significant opportunities for the Australian diabetes care devices market. The integration of diabetes management devices with telemedicine platforms allows for real-time patient monitoring and virtual consultations, providing patients with greater convenience and access to care. This shift, accelerated by the COVID-19 pandemic, is expected to continue, especially in rural and underserved regions where access to healthcare specialists may be limited. As more patients seek remote care solutions, diabetes devices that offer seamless integration with digital health platforms, such as mobile apps and cloud-based systems, are poised for growth. The ability to monitor patients remotely not only improves convenience but also allows for timely interventions and personalized treatment, improving overall patient outcomes.
Focus on Diabetes Prevention and Early Detection
There is also a growing focus on diabetes prevention and early detection, which presents new opportunities for diabetes care device manufacturers. Screening programs, lifestyle interventions, and public health campaigns are helping identify individuals at risk of developing diabetes, driving the need for devices that facilitate early monitoring and management. With early diagnosis, patients can benefit from more effective long-term management, preventing or delaying the onset of complications. Companies that develop devices aimed at early detection, as well as those that support preventive care measures, will be well-positioned to tap into this emerging market. Additionally, advancements in wearable technology, such as continuous glucose monitors and smart insulin pens, can play a crucial role in supporting these preventive efforts, further driving market growth in the coming years.
Market Segmentation Analysis:
By Type:
The Australian diabetes care devices market can be segmented by type into monitoring and delivery devices, each playing a critical role in diabetes management. Monitoring devices are crucial for tracking glucose levels, while delivery devices ensure the precise administration of insulin. As the prevalence of diabetes continues to rise, the demand for both types of devices has increased, with monitoring devices experiencing substantial growth due to their vital role in managing blood glucose levels. Delivery devices, including insulin pumps and smart pens, are also gaining popularity as they offer more accurate insulin administration, improving glycemic control and reducing complications.
By Monitoring Devices:
The monitoring devices segment is further divided into continuous monitoring devices, lancets, test strips, and self-monitoring devices. Continuous monitoring devices, particularly continuous glucose monitors (CGMs), are seeing significant adoption due to their ability to provide real-time glucose readings, enabling patients to make informed decisions about their diet and insulin dosing. Lancets and test strips remain essential for blood glucose testing, particularly in home care settings. Self-monitoring devices, which allow patients to check their glucose levels independently, continue to be widely used, offering convenience and control. This diversity of monitoring options allows for a more personalized approach to diabetes management, contributing to the overall growth of the market. The increasing demand for non-invasive and more accurate monitoring tools is expected to drive further innovations in this segment.
Segments:
Based on Type:
- Monitoring
- Delivery
Based on Monitoring Devices:
- Continuous Monitoring Devices
- Lancets
- Test Strips
- Self Monitoring Devices
Based on Delivery Devices:
- Insulin Pumps
- Pens
- Syringes
- Needles
Based on End-Users:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Based on Indication:
- Diabetes Type I
- Diabetes Type II
- Gestational Diabetes
Based on the Geography:
- New South Wales
- Victoria
- Queensland
- Western Australia (WA)
- South Australia
Regional Analysis
New South Wales (NSW)
New South Wales (NSW) holds the largest market share in the Australian diabetes care devices market, driven by its large population and advanced healthcare infrastructure. NSW accounts for approximately 35% of the overall market, with Sydney, the state capital, being a major hub for medical technology and diabetes care innovations. The state's extensive healthcare networks, including both public and private sectors, contribute significantly to the widespread adoption of advanced diabetes management devices, such as continuous glucose monitoring (CGM) systems and insulin pumps. Additionally, the increasing prevalence of diabetes in urban centers, alongside government initiatives promoting preventive healthcare and diabetes management, further fuels the demand for these devices in the region. As healthcare providers in NSW continue to embrace telemedicine and digital health solutions, the adoption of remote monitoring devices is expected to increase, further supporting market growth. The presence of leading medical device manufacturers and research institutions in NSW also fosters innovation, positioning the region as a key player in the overall diabetes care devices market.
Queensland and Western Australia
Queensland holds a significant share of the Australian diabetes care devices market, accounting for approximately 25%. This is primarily due to the growing elderly population in the region, as older individuals are more susceptible to diabetes, particularly type 2. The demand for diabetes management devices is especially high in regional areas, where access to healthcare professionals can be limited. Remote monitoring devices and telehealth solutions are particularly beneficial in Queensland, as they provide greater access to healthcare in rural and remote areas. Additionally, Queensland’s emphasis on preventative care and early diabetes detection initiatives has encouraged the use of monitoring devices, driving further market demand. Meanwhile, Western Australia (WA) contributes about 15% to the market share, with Perth being the central location for diabetes care advancements. Like Queensland, WA faces challenges related to its vast geographical landscape, which makes remote monitoring solutions increasingly important. Both regions are seeing increased adoption of insulin pumps and CGMs, supported by government funding and reimbursement policies that enhance device affordability. The growing awareness of diabetes care in these regions, combined with healthcare initiatives focusing on better management and prevention, positions Queensland and Western Australia as key regions driving the growth of diabetes care devices in Australia.
Key Player Analysis
- Abbott Laboratories
- ACON Laboratories, Inc.
- Ascensia Diabetes Care Holdings AG
- Becton, Dickinson and Company
- Dexcom, Inc.
- Hoffmann-La Roche Ltd
- Johnson & Johnson
- Medtronic plc
- Novo Nordisk A/S
- YPSOMED
- Company 11
- Company 12
- Company 13
- Company 14
Competitive Analysis
The competitive landscape of the Australian diabetes care devices market is dominated by leading players such as Abbott Laboratories, ACON Laboratories, Inc., Ascensia Diabetes Care Holdings AG, Becton, Dickinson and Company, Dexcom, Inc., F. Hoffmann-La Roche Ltd, Johnson & Johnson, Medtronic plc, Novo Nordisk A/S, and YPSOMED. Leading firms focus on continuous innovation, particularly in the development of continuous glucose monitoring (CGM) systems, insulin pumps, and self-monitoring devices. Companies are increasingly integrating digital health solutions, such as mobile apps and telehealth capabilities, to offer patients more accessible and personalized care. Additionally, advancements in sensor technology and insulin delivery systems are improving patient outcomes and driving market growth. The market is also characterized by increasing investments in research and development, aiming to enhance the accuracy, user-friendliness, and affordability of diabetes care devices. Furthermore, partnerships between device manufacturers and healthcare providers are becoming more common, allowing for expanded access to advanced diabetes management solutions. As a result, the competitive landscape is marked by strong product differentiation, with companies striving to meet the growing demand for effective and accessible diabetes care devices. Despite the competitive intensity, regulatory compliance and reimbursement policies play a significant role in shaping the market dynamics.
Recent Developments
- In October 2024, Glooko secured a USD 100 million investment aimed at expanding its diabetes management system. The funding was intended to enhance the company's reach across North America, as well as the Middle East and Asia.
- In August 2024, Medtronic announced its partnership with Abbott, which was expected to improve its struggling diabetes care segment by integrating advanced glucose monitoring technology, enhancing their offerings and potentially strengthening Medtronic's position in the market.
- In March 2024, Dexcom introduced its newest CGM system, Dexcom ONE+, in Ireland. Dexcom ONE+ utilizes Dexcom's top-tier and highly accurate sensor design. This product launch will bolster the company's product portfolio in the Irish market and is expected to boost the company's revenue.
- In May 2023, Medtronic agreed to acquire EOFlow, a manufacturer of insulin devices. The integration of EOFlow with Medtronic's Meal Detection Technology algorithm and advanced continuous glucose monitor (CGM) is expected to enhance the company's ability to serve a broader range of people with diabetes
- In April 2023, Undbio announced its plan to invest USD 100 million in constructing a US-based insulin manufacturing plant. The South Korean company intends to build a new facility in West Virginia to manufacture insulin and distribute its products within the country
- In July 2023, CharmHealth and Bioverge jointly invested in My Diabetes Tutor, a startup focused on improving the lives of individuals with diabetes
Market Concentration & Characteristics
The market concentration of diabetes care devices in Australia is relatively high, with a few key players dominating the industry. This concentration is driven by the strong presence of global companies that have established significant brand recognition and extensive distribution networks across the country. These companies often lead in innovation, offering advanced products such as continuous glucose monitoring (CGM) systems, insulin pumps, and smart insulin pens. However, the market also sees the emergence of smaller, specialized players that focus on niche segments, including wearable devices and mobile health applications, offering differentiated solutions to meet specific patient needs. Despite the concentration, the market remains competitive, with ongoing product innovations and collaborations between manufacturers and healthcare providers to enhance patient outcomes. The growth of telehealth and remote monitoring solutions is further shaping market dynamics, contributing to the expansion of digital health technologies in diabetes management. Additionally, the Australian government's support through reimbursement policies and subsidies plays a pivotal role in maintaining a competitive environment, enabling broader access to advanced devices. As the demand for diabetes care devices continues to rise, particularly with the aging population and increasing prevalence of diabetes, the market is expected to remain both concentrated and dynamic, with continued efforts toward improving device affordability, usability, and patient empowerment.
Report Coverage
The research report offers an in-depth analysis based on Type, Monitoring Devices, Delivery Devices, Indication, End-Users and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australian diabetes care devices market is expected to continue growing due to the rising prevalence of diabetes, especially among the aging population.
- Technological advancements, particularly in continuous glucose monitoring (CGM) systems, will drive the development of more accurate and user-friendly devices.
- The integration of diabetes care devices with mobile health apps and telehealth platforms will enhance remote monitoring and patient engagement.
- Increasing government funding and reimbursement policies will make diabetes care devices more affordable and accessible to a larger patient base.
- The market will see a rise in the adoption of insulin pumps and smart insulin pens, offering more precise and customizable insulin delivery.
- Demand for wearable diabetes devices will increase as consumers seek non-invasive solutions for continuous glucose monitoring.
- Telehealth adoption, accelerated by the COVID-19 pandemic, will continue to impact the diabetes care devices market, allowing patients to manage their condition remotely.
- Companies will focus on improving device affordability, targeting a wider demographic, including lower-income populations.
- As awareness of diabetes management grows, patients will become more proactive in using advanced devices to control their condition effectively.
- The market will witness increased competition, leading to innovations and partnerships aimed at improving device performance and patient outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Diabetes
Australia is experiencing a significant increase in both type 1 and type 2 diabetes cases, driven by an aging population and rising obesity rates. This expanding patient base is fueling demand for advanced diabetes care devices to support effective disease management.
Government Initiatives and Reimbursement Policies
Supportive government programs, such as the National Diabetes Services Scheme (NDSS), provide subsidies and reimbursement for diabetes care devices, making them more accessible and encouraging wider adoption across the country.
Technological Advancements in Diabetes Management
Continuous innovation in devices like continuous glucose monitoring (CGM) systems, insulin pumps, and smart insulin pens is improving accuracy, usability, and patient outcomes, driving market growth as patients and providers seek more effective solutions.
Expansion of Telehealth and Remote Monitoring
The integration of diabetes care devices with telemedicine platforms has accelerated, especially post-pandemic, enabling remote monitoring and virtual consultations that improve access to care, particularly in rural and underserved regions.
Increased Awareness and Patient Empowerment
Growing public awareness and education initiatives are empowering patients to proactively manage their diabetes, increasing the uptake of user-friendly and connected devices that support self-management and better health outcomes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Diabetes Care Devices Market?
What factors are driving the growth of the Australia Diabetes Care Devices Market?
What are the key segments within the Australia Diabetes Care Devices Market?
What are some challenges faced by the Australia Diabetes Care Devices Market?
Who are the major players in the Australia Diabetes Care Devices Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Monitoring Devices
- 1.2.2 Delivery Devices
- 1.3 By End-Users
- 1.3.1 Hospital Pharmacies
- 1.3.2 Retail Pharmacies
- 1.3.3 Online Pharmacies
- 1.4 By Delivery Devices
- 1.4.1 Insulin Pumps
- 1.4.2 Pens
- 1.4.3 Syringes
- 1.4.4 Needles
- 1.5 By Monitoring Devices
- 1.5.1 Continuous Monitoring Devices
- 1.5.2 Lancets
- 1.5.3 Test Strips
- 1.5.4 Self Monitoring Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 188.49 million → 2032: USD 427.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Diabetes Care Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Diabetes Care Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Diabetes Care Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Diabetes Care Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Diabetes Care Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Diabetes Care Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Diabetes Care Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Diabetes Care Devices Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 188.49 million → 2032: USD 427.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Diabetes Care Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Monitoring Devices
- 12.3.7.2 Delivery Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Users - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospital Pharmacies
- 12.4.7.2 Retail Pharmacies
- 12.4.7.3 Online Pharmacies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Delivery Devices - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Insulin Pumps
- 12.5.7.2 Pens
- 12.5.7.3 Syringes
- 12.5.7.4 Needles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Monitoring Devices - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Continuous Monitoring Devices
- 12.6.7.2 Lancets
- 12.6.7.3 Test Strips
- 12.6.7.4 Self Monitoring Devices
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Diabetes Care Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Diabetes Care Devices Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Diabetes Care Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Diabetes Care Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic plc
- 18.4 Dexcom, Inc.
- 18.5 Becton, Dickinson and Company
- 18.6 F. Hoffmann-La Roche Ltd
- 18.7 Johnson & Johnson
- 18.8 Novo Nordisk A/S
- 18.9 YPSOMED
- 18.10 Ascensia Diabetes Care Holdings AG
- 18.11 ACON Laboratories, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

