
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Toy Market Size 2024 | USD 2,653.43 million |
| Australia Toy Market, CAGR | 5.08% |
| Australia Toy Market Size 2032 | USD 3,943.08 million |
Market Overview
Australia Toy market size was valued at USD 2,653.43 million in 2024 and is anticipated to reach USD 3,943.08 million by 2032, at a CAGR of 5.08% during the forecast period (2024-2032).
The Australian toy market is experiencing steady growth, driven by increasing disposable income, rising demand for educational and STEM-based toys, and the influence of digital transformation on toy innovation. Parents are prioritizing interactive and learning-focused toys, fostering demand for smart and tech-enabled products. Sustainability trends are also shaping consumer preferences, with eco-friendly and ethically sourced toys gaining traction. The rise of e-commerce and omnichannel retailing enhances market accessibility, enabling wider product reach and competitive pricing. Licensing agreements with popular entertainment franchises further drive sales, as character-based toys remain highly sought after. Additionally, the growing awareness of the importance of play in early childhood development supports demand for toys that promote cognitive and motor skills. As industry players invest in digital integration, augmented reality (AR), and artificial intelligence (AI)-enabled toys, the market is set to evolve, catering to the tech-savvy younger generation while maintaining traditional play value.
The Australian toy market is geographically diverse, with major sales driven by urban centers such as Sydney, Melbourne, Brisbane, and Perth. New South Wales and Victoria lead in consumer demand due to their high population density, strong retail infrastructure, and evolving consumer preferences. Queensland and Western Australia also contribute significantly, with outdoor and educational toys gaining traction in these regions. The market is highly competitive, featuring global players like Hasbro, Mattel, and Lego Group, alongside domestic brands such as Funskool Australia. Major retailers, including Big W, Target, and Kmart, play a crucial role in toy distribution, offering a mix of branded and private-label products. The increasing shift toward e-commerce has allowed smaller brands to gain market visibility, while sustainability-focused companies are emerging as key players. Innovation in digital and STEM-based toys continues to shape the competitive landscape, with manufacturers investing in interactive and technology-driven play experiences.
Market Insights
- The Australian toy market was valued at USD 2,653.43 million in 2024 and is projected to reach USD 3,943.08 million by 2032, growing at a CAGR of 5.08% during the forecast period.
- The global toy market was valued at USD 3,18,806.93 million in 2024 and is expected to reach USD 4,44,770.79 million by 2032, growing at a CAGR of 4.25% from 2024 to 2032.
- Rising disposable income and increasing demand for educational and STEM-based toys are driving market growth, as parents prioritize interactive and skill-enhancing play.
- Digital transformation is shaping the industry, with AI-powered, AR-integrated, and app-connected toys gaining popularity among tech-savvy consumers.
- The market is highly competitive, with key players such as Hasbro, Mattel, Lego Group, and Funskool Australia, along with major retailers like Big W, Target, and Kmart.
- Challenges include rising production costs, stringent regulatory compliance, and supply chain disruptions affecting pricing and product availability.
- New South Wales and Victoria dominate the market due to high population density and strong retail infrastructure, while Queensland and Western Australia show increasing demand for outdoor and sustainable toys.
- Sustainability trends are reshaping consumer preferences, with eco-friendly and ethically produced toys gaining significant traction in the market.
Report scope
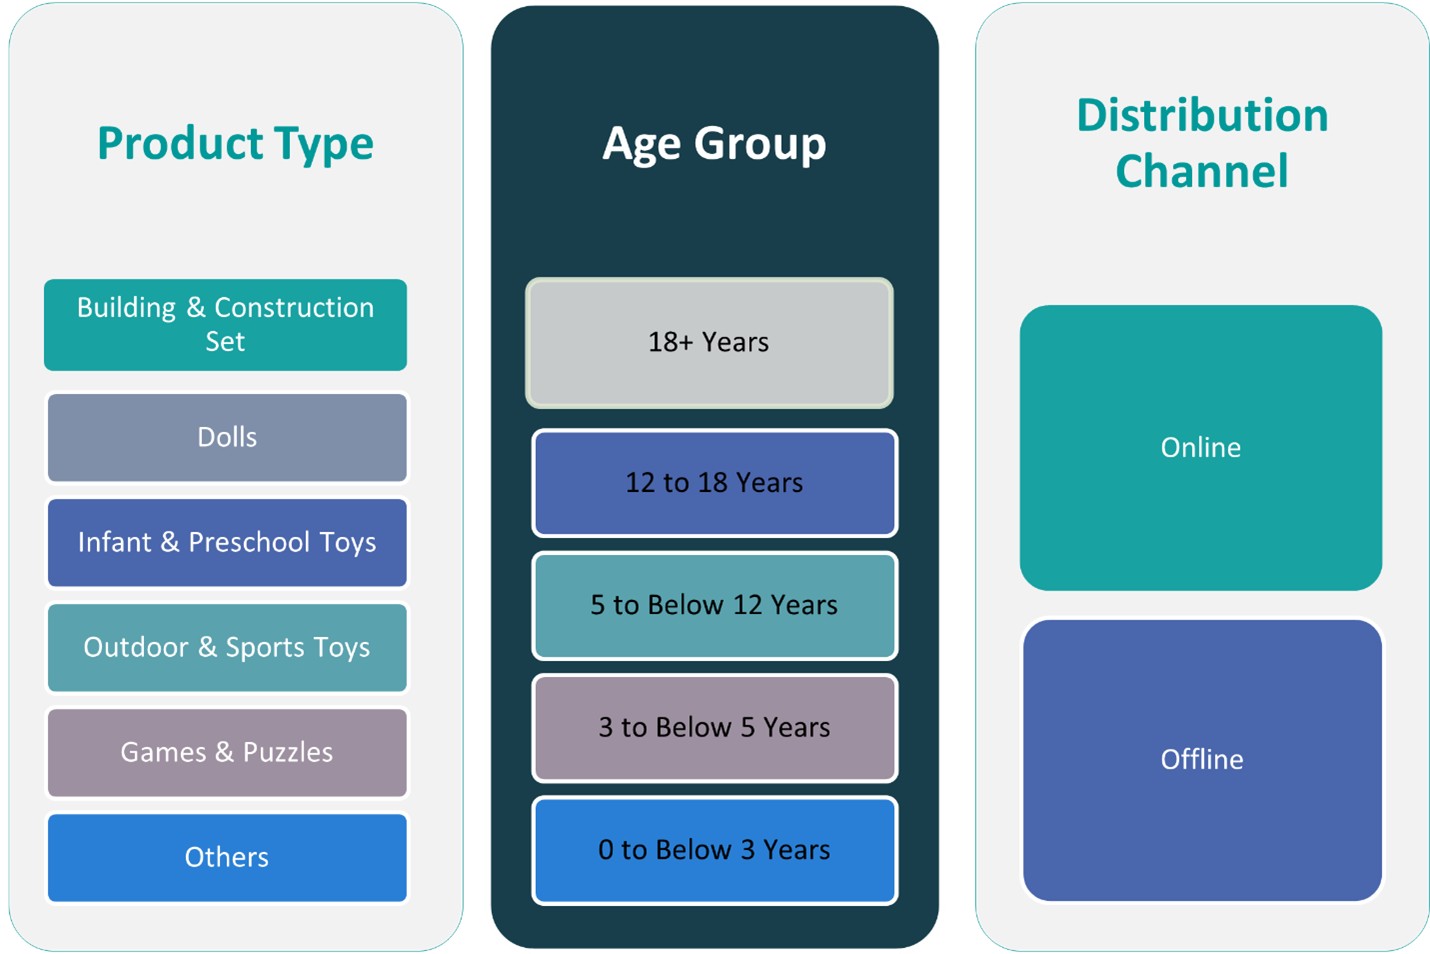
This report segments the Australia Market as follows:
Market Drivers
Rising Disposable Income and Changing Consumer Preferences
Australia’s growing economy and increasing disposable income among households are key drivers of the toy market. Parents are willing to invest in high-quality, educational, and innovative toys that offer long-term value for their children’s development. The demand for premium toys, including STEM-based, interactive, and smart toys, is on the rise as consumers prioritize products that enhance learning and engagement. Additionally, changing lifestyle patterns and urbanization contribute to higher spending on toys, especially in metropolitan areas where access to diverse retail options is greater.
Growing Demand for Educational and STEM Toys
Modern parents emphasize cognitive and motor skill development through play, fueling demand for educational and STEM-based toys. For example, government-backed initiatives in early childhood education have integrated robotics kits and coding games into school curricula, promoting hands-on learning. Schools and early childhood education centers also incorporate learning-oriented toys into their curricula, further boosting market growth. Science kits, robotics, coding games, and building sets are gaining popularity as they align with Australia’s education system, which encourages problem-solving and critical thinking skills. This trend is reinforced by the increasing awareness of technology’s role in shaping future careers, prompting manufacturers to develop more engaging and intellectually stimulating toys.
Digital Transformation and Technology Integration
The integration of technology in toys, including artificial intelligence (AI), augmented reality (AR), and smart features, is revolutionizing the industry. Australian consumers are increasingly drawn to interactive and app-connected toys that offer personalized experiences. The rise of the digital-native generation has led to a shift toward hybrid toys that blend physical and digital play, enhancing engagement and interactivity. For instance, consumer behavior studies show that Australian families are drawn to app-connected toys that offer personalized experiences, such as interactive storytelling devices. Additionally, social media and online platforms significantly influence purchasing decisions, with parents and children exposed to trending toys through influencers, advertisements, and online reviews. E-commerce platforms and omnichannel retailing further drive market expansion by providing convenience, competitive pricing, and a wider selection of products.
Sustainability and Ethical Consumerism
Environmental concerns and sustainability initiatives are shaping the Australian toy market, with consumers demanding eco-friendly and ethically produced toys. Manufacturers are increasingly using recycled materials, biodegradable packaging, and non-toxic components to align with sustainability goals. Regulatory bodies and environmental organizations also advocate for stricter standards in toy production, further encouraging brands to adopt sustainable practices. As ethical consumerism gains momentum, companies that emphasize responsible sourcing, fair labor practices, and environmentally friendly production methods gain a competitive edge. This shift not only caters to eco-conscious parents but also aligns with Australia’s broader commitment to sustainability and corporate social responsibility.
Market Trends
Increasing Popularity of Educational and STEM Toys
The Australian toy market is witnessing a strong shift towards educational and STEM-based toys as parents and educators prioritize cognitive development through play. Science kits, robotics, coding games, and building sets are in high demand, aligning with Australia’s education system, which promotes problem-solving and critical thinking skills. For instance, toy manufacturers are incorporating STEM concepts into their products, ensuring that children engage with interactive and skill-building toys that prepare them for future careers in technology, engineering, and science. This trend is supported by surveys from educational institutions that highlight the importance of early STEM education in shaping future career paths.
Digital Integration and Smart Toys on the Rise
The rapid advancement of technology is transforming the toy industry, with AI-powered, augmented reality (AR), and interactive app-enabled toys gaining popularity. These toys offer immersive and personalized experiences, appealing to tech-savvy children and parents seeking innovative entertainment solutions. Hybrid toys that combine physical and digital play are becoming mainstream, supported by the growing penetration of smartphones and tablets. Additionally, social media influences consumer preferences, with viral trends and online reviews significantly impacting toy sales and brand visibility.
Sustainability and Eco-Friendly Toy Demand
Consumers in Australia are increasingly prioritizing sustainability, leading to higher demand for eco-friendly and ethically produced toys. Parents prefer toys made from recycled materials, biodegradable components, and non-toxic substances, encouraging manufacturers to adopt sustainable practices. Many toy companies are now focusing on reducing plastic usage, improving packaging sustainability, and ensuring ethical labor practices. This trend aligns with Australia’s broader environmental initiatives and growing awareness of corporate social responsibility, making sustainability a key factor in purchasing decisions.
Expansion of E-Commerce and Omnichannel Retailing
The Australian toy market is experiencing a shift in retail dynamics, with e-commerce and omnichannel strategies playing a crucial role in sales growth. Online platforms offer convenience, competitive pricing, and a vast selection of toys, attracting busy parents and tech-savvy consumers. For example, major toy brands are leveraging digital marketing, personalized recommendations, and direct-to-consumer (DTC) sales models to enhance customer engagement. Additionally, traditional retailers are integrating online and offline experiences, such as click-and-collect services and interactive in-store displays, to cater to evolving shopping behaviors and improve customer satisfaction.
Market Challenges Analysis
Rising Production Costs and Supply Chain Disruptions
The Australian toy market faces significant challenges due to increasing production costs and ongoing supply chain disruptions. The rising cost of raw materials, labor, and transportation directly impacts toy pricing, making it difficult for manufacturers to maintain affordability while ensuring quality. Global supply chain disruptions, exacerbated by geopolitical tensions and logistical bottlenecks, have led to delays in product availability and higher import costs. Many Australian toy retailers rely on international suppliers, particularly from China, making them vulnerable to fluctuations in shipping costs, currency exchange rates, and regulatory changes. These challenges force businesses to explore local manufacturing, alternative supply sources, or cost-cutting measures, which may affect product diversity and innovation.
Regulatory Compliance and Market Competition
Strict safety and compliance regulations in Australia pose another challenge for toy manufacturers and retailers. For instance, the Australian Competition and Consumer Commission (ACCC) enforces five mandatory toy safety standards aligned with international benchmarks like ISO 8124 and ASTM F963. Adhering to stringent safety standards, including non-toxic materials, age-appropriate designs, and rigorous testing, increases operational costs and time-to-market for new products. Additionally, the market is becoming increasingly competitive, with local brands, international companies, and private-label retailers vying for consumer attention. The dominance of large multinational toy brands, combined with the rise of e-commerce marketplaces, puts pressure on small and mid-sized businesses to differentiate themselves through unique product offerings and marketing strategies. As consumer preferences shift towards sustainable and tech-driven toys, companies must continuously innovate while managing regulatory and financial constraints to remain competitive in the evolving market landscape.
Market Opportunities
Australia's toy market presents significant growth opportunities driven by evolving consumer preferences and technological advancements. The increasing demand for educational and STEM-based toys offers manufacturers a chance to develop innovative products that support children's cognitive and motor skill development. As parents prioritize learning through play, companies can expand their product lines to include interactive, coding, and robotics-based toys that align with modern educational trends. Additionally, the growing awareness of mental and emotional well-being among children has created opportunities for sensory toys, mindfulness kits, and toys designed to enhance social skills. With schools and early learning centers incorporating play-based education, manufacturers can collaborate with educational institutions to introduce curriculum-aligned toys, further expanding their market reach.
Sustainability and digital transformation also present lucrative opportunities in the Australian toy industry. Consumers are increasingly seeking eco-friendly toys made from recycled materials and sustainable packaging, allowing brands to differentiate themselves by adopting environmentally responsible practices. Companies that prioritize ethical sourcing and transparency in production can build strong brand loyalty among eco-conscious parents. Additionally, the rapid expansion of e-commerce and omnichannel retailing provides opportunities for toy brands to leverage digital platforms for direct-to-consumer sales, subscription-based toy services, and personalized shopping experiences. The integration of augmented reality (AR) and artificial intelligence (AI) into toys further enhances engagement, appealing to tech-savvy children and parents. By embracing digital marketing strategies and leveraging data-driven insights, toy companies can refine their product offerings, target specific consumer segments, and enhance customer engagement in a competitive market.
Market Segmentation Analysis:
By Product Type:
The Australian toy market is segmented into various product categories, each catering to different consumer preferences and play experiences. Building and construction sets are highly popular, particularly among children interested in STEM learning, as they enhance creativity, problem-solving skills, and spatial awareness. Brands offering modular and interactive construction toys continue to witness strong demand. Dolls remain a key segment, driven by evolving trends in character-based and fashion dolls, often influenced by entertainment franchises and social media trends. The infant and preschool toys segment benefits from growing awareness of early childhood development, with parents opting for interactive, sensory, and educational toys that promote motor skills and cognitive growth. Outdoor and sports toys continue to see increased demand, especially post-pandemic, as parents encourage outdoor play to promote physical activity. Additionally, games and puzzles remain a strong segment, appealing to both children and adults by fostering strategic thinking and social interaction, with rising demand for family-oriented and educational board games.
By Age Group:
The toy market in Australia is also segmented by age group, addressing the specific needs and interests of different demographics. The 0 to below 3 years segment is driven by demand for sensory, soft, and educational toys that promote early developmental skills, while the 3 to below 5 years group shows strong interest in creative play, including role-playing sets and interactive learning toys. The 5 to below 12 years segment dominates the market, with a preference for construction sets, board games, and tech-enabled toys that balance entertainment and education. The 12 to 18 years segment sees demand for strategy-based board games, collectibles, and digital-integrated toys, while the 18+ years category has grown due to nostalgia-driven purchases, collectibles, and gaming-related merchandise, reflecting an expanding adult toy consumer base.
Segments:
Based on Product Type:
- Building & Construction Set
- Dolls
- Infant & Preschool Toys
- Outdoor & Sports Toys
- Games & Puzzles
Based on Age Group:
- 18+ Years
- 12 to 18 Years
- 5 to Below 12 Years
- 3 to Below 5 Years
- 0 to Below 3 Years
Based on Distribution Channel:
- Online
- Offline
Based on the Geography:
- New South Wales
- Victoria
- Queensland
- Western Australia (WA)
- South Australia
Regional Analysis
New South Wales
New South Wales holds the largest share of the Australian toy market, accounting for approximately 32% of total sales. As the most populous state, NSW benefits from a high concentration of urban centers, affluent consumers, and a strong retail presence, including flagship toy stores and shopping malls. Sydney, in particular, serves as a major hub for toy distribution and retail, with both brick-and-mortar stores and e-commerce platforms driving significant sales. The demand for STEM-based and tech-integrated toys is notably strong in this region, fueled by parents' emphasis on educational development. Additionally, the presence of major entertainment venues and themed attractions contributes to the demand for licensed character toys and collectibles.
Victoria
Victoria follows closely, contributing around 28% of the total toy market share. Melbourne, known for its vibrant culture and diverse population, plays a crucial role in shaping toy preferences and trends. The state’s growing emphasis on sustainability and ethical consumerism has fueled demand for eco-friendly and ethically sourced toys. Victoria also boasts a strong market for board games and puzzles, as family-oriented leisure activities gain popularity. Additionally, the expansion of online shopping and digital retail platforms has significantly boosted toy sales, particularly among tech-savvy consumers seeking convenience and variety. The integration of omnichannel retailing strategies, such as click-and-collect services, has further strengthened the toy market in this region.
Queensland
Queensland represents approximately 18% of the Australian toy market, with strong demand for outdoor and sports toys due to the state's warm climate and active lifestyle. Cities like Brisbane and Gold Coast drive substantial sales, as parents invest in toys that encourage outdoor play and physical activity. The tourism industry in Queensland also contributes to toy sales, with theme parks and attractions generating demand for souvenir toys, collectibles, and branded merchandise. Additionally, the state’s growing population and rising disposable income levels support market expansion, as families seek high-quality, engaging toys that cater to both entertainment and education.
Western Australia
Western Australia holds a 12% market share, with Perth being the primary driver of toy sales in the state. The region's geographic isolation poses logistical challenges for toy distribution, leading to a higher reliance on e-commerce platforms. However, WA's strong economy and high disposable income levels contribute to steady demand, particularly for premium and imported toys. Educational toys and interactive learning products are increasingly popular among parents in Perth, aligning with the national trend toward STEM-based learning. Additionally, WA’s focus on sustainability has influenced consumer choices, with a growing preference for eco-friendly toys made from recycled materials and biodegradable packaging.
Key Player Analysis
- Hasbro, Inc.
- Funskool Australia
- Big W, Target, Kmart (Retailers)
- Mattel, Inc.
- Lego Group
Competitive Analysis
The Australian toy market is highly competitive, with established global brands and strong domestic retailers shaping the industry. Hasbro, Mattel, Lego Group, and Funskool Australia, along with major retailers such as Big W, Target, and Kmart, dominate the market. Companies compete based on product diversity, pricing strategies, and technological advancements, particularly in STEM-based and interactive toys. The rising demand for digital and eco-friendly toys has intensified competition, pushing manufacturers to invest in smart technology, augmented reality integration, and sustainable materials. Retailers play a crucial role in shaping consumer preferences by offering exclusive product lines, competitive pricing, and omnichannel shopping experiences. The expansion of e-commerce has further fueled market competition, allowing both global and emerging brands to reach a wider audience. Additionally, licensing agreements with entertainment franchises continue to influence purchasing decisions, as character-based toys remain highly popular. Despite market opportunities, challenges such as rising production costs, regulatory compliance, and supply chain disruptions require companies to continuously adapt and innovate to maintain their competitive edge.
Recent Developments
- In March 2025, the LEGO Group launched a wide range of new sets, including LEGO Architecture, LEGO Art, and LEGO Formula 1, with over 40 sets released on March 1st, including the Trevi Fountain and several Formula 1 Speed Champions sets.
- In March 2025, MGA Entertainment's Little Tikes brand announced a partnership with BBC Studios to launch a line of Bluey-inspired toys, including the Bluey Grannies Car Coupe, Bluey Bushland Adventures Splash Pad, Bluey Beach Day Sand Box, and Bluey Beach Water Table.
- In March 2025, the LEGO Group announced a new multi-year partnership with The Pokémon Company International to bring LEGO Pokémon sets starting in 2026.
- In March 2025, Spin Master announced the renewal of its global master toy licensee agreement with DreamWorks Animation for Gabby's Dollhouse.
- In March 2025, Hasbro participated in the North American International Toy Fair, showcasing new products and collaborations, including a PLAY-DOH Barbie line and Marvel's Iron Man toys.
- In March 2025, Mattel renewed its multi-year global licensing agreement with Disney for Toy Story, planning new products for the franchise's 30th anniversary and Toy Story 5.
Market Concentration & Characteristics
The Australian toy market exhibits a moderate to high level of market concentration, with a few dominant players controlling a significant share of sales. Large multinational toy manufacturers, alongside major domestic retailers, shape industry trends through strong brand presence, product innovation, and extensive distribution networks. The market is characterized by a diverse product range, including traditional toys, educational and STEM-based products, digital-integrated playthings, and eco-friendly alternatives. Consumer preferences are shifting towards interactive, technology-driven, and sustainable toys, prompting companies to invest in smart features, augmented reality, and environmentally responsible materials. The rise of e-commerce and omnichannel retailing has further influenced market dynamics, enabling smaller brands to compete with established players. Despite increasing competition, barriers to entry remain due to strict safety regulations, high production costs, and the need for strong retail partnerships. As demand evolves, companies must balance affordability, innovation, and sustainability to maintain a competitive edge in this dynamic market.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Age Group, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australian toy market is expected to witness steady growth, driven by increasing demand for educational and interactive toys.
- Digital transformation will continue shaping the industry, with AI-powered, AR-integrated, and app-connected toys gaining popularity.
- Sustainability will play a crucial role, with consumers preferring eco-friendly, biodegradable, and ethically produced toys.
- E-commerce and omnichannel retailing will expand further, allowing brands to reach a wider audience through digital platforms.
- Licensing agreements with entertainment franchises will remain a key growth factor, boosting demand for character-based toys.
- The rise of STEM-based toys will continue as parents and educators emphasize skill development through play.
- Supply chain optimization and local manufacturing may increase to reduce dependency on international suppliers.
- Retailers will focus on personalized shopping experiences and exclusive product lines to enhance consumer engagement.
- Collectible toys and nostalgia-driven purchases will gain traction among both children and adult consumers.
- Companies will invest more in product innovation, ensuring a balance between affordability, quality, and sustainability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Disposable Income and Changing Consumer Preferences
Australia's growing economy and higher household incomes are enabling parents to spend more on premium, educational, and innovative toys, particularly in urban centers with strong retail infrastructure.
Growing Demand for Educational and STEM Toys
Parents and educators are increasingly prioritizing toys that support cognitive and motor skill development, driving demand for science kits, robotics, coding games, and building sets that align with Australia's education system.
Digital Transformation and Technology Integration
The integration of AI, AR, and app-connected features in toys is attracting tech-savvy families, with hybrid physical-digital play experiences becoming mainstream and influencing purchasing decisions through online channels.
Sustainability and Ethical Consumerism
Australian consumers are showing a strong preference for eco-friendly, ethically produced toys, prompting manufacturers to adopt recycled materials, biodegradable packaging, and responsible sourcing to meet regulatory and consumer expectations.
Expansion of E-Commerce and Omnichannel Retailing
The growth of online platforms and omnichannel strategies is making toys more accessible, offering convenience, competitive pricing, and a wider product selection, which is especially important in geographically dispersed regions like Western Australia.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Toy market?
What factors are driving the growth of the Australia Toy market?
What are some challenges faced by the Australia Toy market?
Who are the major players in the Australia Toy market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Age Group
- 1.2.1 0 to Below 3 Years
- 1.2.2 3 to Below 5 Years
- 1.2.3 5 to Below 12 Years
- 1.2.4 12 to 18 Years
- 1.2.5 18+ Years
- 1.3 By Product Type
- 1.3.1 Building & Construction Set
- 1.3.2 Dolls
- 1.3.3 Infant & Preschool Toys
- 1.3.4 Outdoor & Sports Toys
- 1.3.5 Games & Puzzles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,653.43 million → 2032: USD 3,943.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Toy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Toy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Toy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Toy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Toy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Toy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Toy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Toy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,653.43 million → 2032: USD 3,943.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Toy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Age Group - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 0 to Below 3 Years
- 12.3.7.2 3 to Below 5 Years
- 12.3.7.3 5 to Below 12 Years
- 12.3.7.4 12 to 18 Years
- 12.3.7.5 18+ Years
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Building & Construction Set
- 12.4.7.2 Dolls
- 12.4.7.3 Infant & Preschool Toys
- 12.4.7.4 Outdoor & Sports Toys
- 12.4.7.5 Games & Puzzles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Toy Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia Toy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia Toy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Hasbro, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Mattel, Inc.
- 17.4 Lego Group
- 17.5 Funskool Australia
- 17.6 Spin Master
- 17.7 MGA Entertainment
- 17.8 Big W
- 17.9 Target Australia
- 17.10 Kmart Australia
- 17.11 Moose Toys
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

