
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Toy Market Size 2024 | USD 316.14 Billion |
| Toy Market, CAGR | 4.33% |
| Toy Market Size 2032 | USD 445.97 Billion |
Market Overview
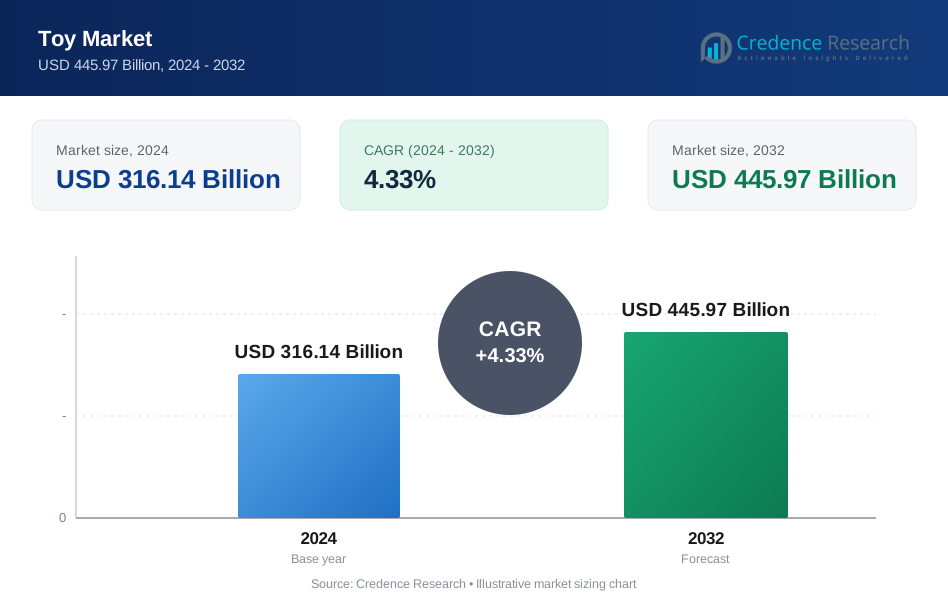
The global demand for the Toys Market was valued at USD 316.14 Billion in 2024 is expected to reach USD 445.97 Billion in 2032 growing at a CAGR of 4.33% between 2025 and 2032.
The global toy market is driven by factors such as increasing disposable income, technological advancements, and a rising demand for educational and interactive toys. The growing popularity of e-commerce has expanded market access, enabling consumers to easily purchase toys online. Additionally, the shift toward sustainability has led to a growing preference for eco-friendly and ethically produced toys, further fueling market growth. Innovations such as augmented reality (AR) and smart toys are gaining traction, appealing to tech-savvy consumers. Changing consumer preferences, with a focus on STEM (Science, Technology, Engineering, and Mathematics) toys, have also contributed to market expansion, as parents seek toys that combine entertainment with educational value. Furthermore, the rising influence of licensing and character-based toys, driven by popular media franchises, continues to drive consumer interest globally. As a result, the toy industry is poised for steady growth, with a focus on technological integration and sustainable production methods.
The global toy market is geographically diverse, with key players spanning across North America, Europe, Asia-Pacific, and emerging regions like Latin America and the Middle East. North America and Europe remain dominant in terms of both consumption and innovation, driven by high disposable incomes and a strong preference for quality and educational toys. In Asia-Pacific, countries like China, Japan, and India are rapidly growing markets, both in production and consumption, influenced by rising disposable income and urbanization. Leading players in the global toy industry include prominent companies like LEGO Group, Hasbro, MGA Entertainment, Mattel, and Spin Master, which are known for their vast product portfolios and innovative offerings. These companies are continuously expanding their reach through online channels, strategic acquisitions, and by focusing on sustainability and technological integration to meet the evolving preferences of consumers worldwide.
Market Insights
- The global toy market was valued at USD 316.14 billion in 2024 and is expected to reach USD 445.97 billion by 2032, growing at a CAGR of 4.33% from 2024 to 2032.
- Technological advancements, such as the rise of smart toys, AR, and robotics, are significantly driving market growth.
- Increasing demand for educational and STEM toys is reshaping consumer preferences, especially among parents seeking developmental benefits.
- E-commerce expansion is making toys more accessible, contributing to higher sales across global markets.
- Major players like LEGO, Hasbro, and Mattel are constantly innovating to stay competitive, focusing on licensing, sustainability, and digital play integration.
- Supply chain disruptions and rising production costs are key challenges facing the toy industry.
- The Asia-Pacific region is the fastest-growing market, driven by rising disposable incomes, urbanization, and an increasing appetite for both traditional and tech-based toys.
Report Scope
This report segments the global Market as follows: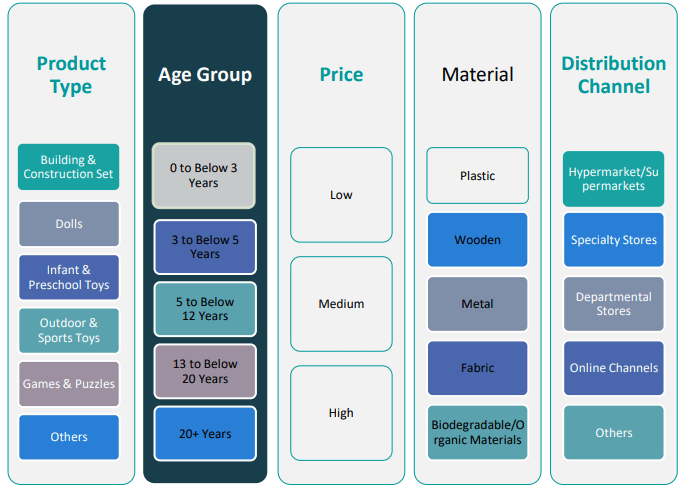
Market Drivers
Technological Advancements in Toys
The rapid development of technology has significantly influenced the global toy market. The rise of smart toys, robotics, augmented reality (AR), and virtual reality (VR) has created new opportunities for product innovation. For instance, initiatives like India's "Made in India Toys" program have encouraged the development of innovative toys that integrate robotics and AI. These advanced toys not only offer enhanced play experiences but also incorporate educational elements, fostering both learning and entertainment. Parents increasingly seek toys that combine fun with developmental benefits, such as promoting STEM (Science, Technology, Engineering, and Mathematics) skills in children. Smart toys that use artificial intelligence (AI) or connect to mobile apps have gained popularity, making playtime more interactive and engaging. As technology continues to evolve, toys that integrate with digital platforms and offer personalized experiences will become even more attractive to consumers, further fueling market growth.
E-commerce Expansion
The global expansion of e-commerce has transformed the toy market by making it easier for consumers to purchase toys from anywhere at any time. The convenience of online shopping, coupled with detailed product information, reviews, and delivery services, has led to a significant shift in consumer buying behavior. For instance, a study by the Competition Commission of India highlights how e-commerce platforms have revolutionized consumer access to toys, offering detailed product descriptions and personalized recommendations. The COVID-19 pandemic accelerated this trend, as more consumers turned to online retailers for their toy purchases. Additionally, e-commerce platforms allow for more personalized recommendations based on browsing history and preferences, which can further drive toy sales. As internet penetration and digital literacy improve globally, online toy sales will continue to increase, making e-commerce a key driver for the industry.
Rising Disposable Incomes and Changing Lifestyles
Increasing disposable incomes, especially in emerging markets, are playing a crucial role in the growth of the global toy market. As more people move into the middle class and experience an improved standard of living, spending on non-essential items like toys has increased. This trend is particularly evident in regions such as Asia-Pacific, where rapid urbanization and economic growth are expanding the consumer base. Additionally, changing lifestyles, with a focus on family activities and entertainment, are driving higher demand for toys that provide value through engagement, learning, and interactive experiences. Parents are willing to invest in high-quality toys that support the development of their children, particularly those that offer long-term educational benefits. As purchasing power increases in these regions, the toy market is expected to expand in tandem, with higher spending on both traditional and innovative toys.
Sustainability and Eco-friendly Toy Demand
Sustainability is increasingly influencing consumer purchasing decisions, driving a growing preference for eco-friendly and ethically produced toys. As concerns over environmental impact rise, more consumers are looking for products made from sustainable materials such as wood, biodegradable plastics, or recycled components. Additionally, toys that promote environmental awareness, such as those that teach about nature or conservation, are gaining popularity. Leading toy manufacturers are responding to this demand by incorporating sustainable practices into their production processes, from using renewable resources to reducing packaging waste. This shift is not only driven by consumer demand but also by government regulations and industry standards encouraging sustainability. As environmental consciousness continues to grow, the market for eco-friendly toys is expected to expand, further contributing to the overall growth of the global toy industry.
Market Trends
Shift Towards Educational and STEM Toys
A significant market trend in the global toy industry is the increasing demand for educational toys, particularly those focused on STEM (Science, Technology, Engineering, and Mathematics) learning. For instance, government initiatives like India's National Education Policy emphasize the integration of STEM learning through toys, encouraging manufacturers to develop products that foster creativity and problem-solving skills. Parents and educators are recognizing the importance of integrating learning with play, leading to a surge in toys that encourage problem-solving, creativity, and cognitive development. From building sets and robotics kits to coding toys, these products engage children while promoting critical thinking and technical skills. As children’s educational needs evolve, manufacturers are continually innovating to offer toys that help children learn while having fun. This trend is likely to grow, with a strong focus on products that bridge the gap between entertainment and education.
Incorporation of Technology and Digital Play
Technology continues to be a defining trend in the toy market, with toys becoming increasingly interactive and digitally connected. The rise of smart toys, which incorporate artificial intelligence, augmented reality (AR), and app-based play, is revolutionizing the toy industry. These high-tech toys allow children to engage with physical products that also interact with digital devices, creating a more immersive play experience. For example, some toys use AR to enhance storytelling, while others integrate with mobile apps for interactive games. As digital natives become the primary consumers, toys that blend traditional play with modern technology will dominate the market, offering new experiences and value for both children and parents.
Rise of Eco-friendly and Sustainable Toys
Sustainability has become a key trend in the global toy market, as consumers increasingly demand products that are environmentally friendly. In response, toy manufacturers are focusing on creating toys that are made from sustainable materials, such as recycled plastics, organic cotton, and biodegradable components. For instance, companies like Playmobil and Mattel are leading the way in sustainability by using recycled materials and biodegradable components in their toy production. Additionally, brands are reducing packaging waste and improving the energy efficiency of their production processes. Parents are becoming more conscious of the environmental impact of their purchasing choices, seeking out eco-friendly toys that align with their values. This shift towards sustainability is not only being driven by consumer demand but also by evolving regulations and industry guidelines focused on reducing the environmental footprint of toys.
Growing Popularity of Licensed and Character-based Toys
Another prominent trend in the global toy market is the growing popularity of licensed toys based on movies, television shows, and video games. Characters from popular franchises like Marvel, Star Wars, and Disney continue to be a major influence on toy sales, as children and collectors eagerly purchase toys that feature their favorite characters. This trend extends beyond traditional toys to include apparel, games, and collectibles, contributing to the widespread commercialization of media content. Licensed toys tap into the strong emotional connection that children and adults have with these characters, creating a loyal customer base. As franchises expand and new ones emerge, the demand for character-based toys is expected to remain a key trend in the market.
Market Challenges Analysis
Increasing Regulatory Pressure and Safety Concerns
One of the primary challenges facing the global toy market is the increasing regulatory pressure and safety concerns surrounding toy manufacturing. As consumer awareness of product safety rises, regulatory bodies worldwide are implementing stricter standards for toy safety, particularly concerning materials, construction, and age-appropriate features. For instance, the European Union's Toy Safety Directive mandates rigorous testing for hazardous chemicals and choking hazards, ensuring toys meet stringent safety standards. Similarly, India's Bureau of Indian Standards (BIS) has introduced regulations requiring toy manufacturers to comply with safety norms, including the use of non-toxic materials. Additionally, the scrutiny around the use of hazardous chemicals, small parts, and choking hazards is heightening concerns. Ensuring the safety of toys while maintaining affordability and innovation presents a challenge for manufacturers, who must balance cost constraints with the need to meet safety expectations. This issue is especially pressing in markets like Europe and North America, where regulations are becoming increasingly stringent.
Intense Competition and Price Sensitivity
The global toy market is highly competitive, with numerous players, including established multinational corporations and small niche brands, vying for consumer attention. This intense competition places significant pressure on manufacturers to continuously innovate while maintaining competitive pricing. The rising costs of raw materials, logistics, and labor can exacerbate these challenges, especially in emerging markets where price sensitivity is higher. Additionally, the growth of e-commerce has increased the reach of both global brands and independent toy sellers, making it more difficult for companies to stand out. To remain competitive, toy manufacturers must focus on brand differentiation, quality, and offering value-added features, all while ensuring their products remain affordable to price-conscious consumers. This ongoing pressure for innovation and cost efficiency represents a significant challenge in maintaining profitability in a crowded and rapidly changing market.
Market Opportunities
The global toy market presents significant opportunities driven by evolving consumer preferences and technological advancements. One of the most promising opportunities lies in the growing demand for educational toys, particularly those focused on STEM (Science, Technology, Engineering, and Mathematics) education. As parents and educators increasingly seek products that promote learning and skill development alongside play, manufacturers have the chance to create innovative toys that blend education with entertainment. Additionally, the rise of digital play, including smart toys and augmented reality (AR)-enhanced products, presents a unique opportunity to tap into the tech-savvy generation of children. These toys not only provide immersive experiences but also foster cognitive and creative growth, positioning them as valuable tools for modern parenting. By capitalizing on these trends, companies can cater to a more conscious and educated consumer base while also positioning themselves as leaders in the future of toy manufacturing.
Sustainability and eco-friendly toys are another area of substantial opportunity. As environmental awareness increases among consumers, the demand for toys made from sustainable materials, such as recycled plastics and organic materials, is rapidly growing. Brands that prioritize ethical sourcing, sustainable production practices, and eco-friendly packaging can attract environmentally conscious consumers, particularly in developed markets. This shift also presents opportunities for companies to differentiate themselves through green certifications or partnerships with environmental organizations, tapping into a growing segment of the market that values sustainability. Furthermore, the rise of e-commerce provides access to global markets, allowing toy manufacturers to expand their reach and cater to international consumers. As digital retail platforms become increasingly influential, companies can leverage data-driven insights to optimize marketing strategies and target specific consumer groups, ensuring long-term growth and market expansion.
Market Segmentation Analysis:
By Product Type:
The global toy market is diverse, with several product types driving growth. The Building & Construction Set segment continues to gain traction, appealing to children and adults alike due to its educational value and creativity-enhancing features. These toys encourage cognitive development, problem-solving, and fine motor skills. The Dolls segment remains a key player, with a wide range of options from traditional dolls to high-tech, interactive models, driven by popular characters from franchises like Disney and Barbie. Infant & Preschool Toys represent a crucial market segment, focusing on toys that stimulate early childhood development, such as sensory toys, educational tools, and activity centers. The Outdoor & Sports Toys segment is growing as parents increasingly invest in products that promote physical activity and outdoor play. These toys not only provide entertainment but also promote health and fitness. Lastly, the Games & Puzzles segment appeals to all age groups and emphasizes family bonding, cognitive growth, and skill-building, particularly in digital and traditional formats.
By Age Group:
The global toy market also exhibits a broad diversity across age groups. For the 18+ Years segment, there is an increasing demand for collectible and hobby-based toys, such as action figures, building kits, and board games. These toys cater to adult collectors or enthusiasts, often tying into pop culture and nostalgia. The 12 to 18 Years group demands more complex toys, such as drones, robotics kits, and video games, blending entertainment with technological advancements. For the 5 to Below 12 Years segment, toys focus on education, creativity, and social development, with a rise in STEM-related products, games, and toys promoting teamwork and learning. 3 to Below 5 Years is a pivotal age group for developmental toys that encourage motor skills, basic problem-solving, and social interaction, with products like puzzles, arts and crafts, and early STEM kits. Finally, the 0 to Below 3 Years segment remains focused on sensory toys, rattles, and plush toys that engage infants’ senses and foster early motor development.
Segments:
Based on Product Type:
- Building & Construction Set
- Dolls
- Infant & Preschool Toys
- Outdoor & Sports Toys
- Games & Puzzles
- Others
Based on Age Group:
- 0 to Below 3 Years
- 3 to Below 5 Years
- 5 to Below 12 Years
- 13 to Below 20 Years
- 20+ Years
- Plastic
- Wooden
- Metal
- Fabric
- Biodegradable/Organic Materials
- Low
- Medium
- High
Based on Distribution Channel:
- Hypermarket/Supermarkets
- Specialty Stores
- Departmental Stores
- Online Channels
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a significant share of the global toy market, accounting for approximately 30% of the total market revenue. The region is driven by strong consumer demand, particularly in the United States, where the toy industry benefits from high disposable income, a large population, and a strong retail presence. The popularity of digital and interactive toys, along with the demand for licensed products based on popular entertainment franchises, is fueling growth. Moreover, the region is seeing a rise in e-commerce sales, providing consumers with easier access to a broad range of toy products. In addition to the growing demand for innovative toys, North America’s strict safety standards and regulations ensure that only high-quality products are available, which is crucial in maintaining consumer trust and market stability.
Europe
Europe is another prominent region in the global toy market, contributing to approximately 25% of the market share. This region sees significant demand for both traditional and innovative toys, particularly those focused on educational development and sustainability. European consumers are increasingly drawn to eco-friendly toys, pushing manufacturers to adapt to sustainability trends. Countries such as Germany, the UK, and France are key players in the European market, with strong sales in both online and offline retail channels. The market is also influenced by the rising popularity of digital toys and the integration of technology into traditional play experiences. The European toy market is expected to continue its steady growth, driven by the demand for diverse product types, from dolls and building sets to STEM toys and interactive games.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth, with a market share of about 35%. This growth is largely driven by the booming economies of China, India, and Japan, where increasing disposable income and changing consumer preferences are reshaping the toy market. In particular, China is a dominant force in the production of toys, while India represents a growing consumer market. The demand for educational toys, especially those in the STEM category, is surging in this region. Additionally, the popularity of outdoor and sports toys is rising, especially in urban areas with more access to recreational facilities. E-commerce is also playing a vital role in the Asia-Pacific region, as digital platforms make toys more accessible to consumers, especially in emerging markets. The Asia-Pacific toy market is poised for robust growth, supported by both local demand and global exports.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa (MEA) regions account for a combined market share of approximately 10%. In Latin America, countries like Brazil and Mexico are witnessing increased toy sales due to economic development, rising disposable incomes, and greater urbanization. The demand for educational toys, such as building sets and dolls, is growing as parents place more emphasis on developmental products. The Middle East & Africa region, while smaller, is also experiencing growth, especially in countries with expanding middle-class populations such as Saudi Arabia, the UAE, and South Africa. E-commerce is gaining traction in these regions, providing access to a broader range of toy options and driving sales. Despite challenges related to economic instability and lower disposable incomes in certain areas, the toy market in these regions is projected to expand steadily, fueled by regional demand for quality products and increasing online shopping opportunities.
Key Player Analysis
- LEGO Group
- Hasbro
- MGA Entertainment Inc
- Mattel
- Spin Master
- Moose Toys
- Tomy Company Ltd.
- Funko
- Bandai Namco Holdings Inc.
- JAKKS Pacific, Inc.
- Others
Competitive Analysis
The global toy market is highly competitive, with several leading players continually innovating to maintain their market positions. Major companies such as LEGO Group, Hasbro, MGA Entertainment, Mattel, and Spin Master dominate the market by offering a wide range of toys, including licensed products, educational toys, and interactive games. These companies leverage strong brand recognition, extensive distribution networks, and strategic partnerships with entertainment franchises to secure their competitive edge. Innovation is key, as companies are increasingly integrating digital technology into toys, with products incorporating augmented reality, artificial intelligence, and smart connectivity to engage tech-savvy consumers. Additionally, the rise of educational toys, particularly those in the STEM category, is driving competition, with companies competing to offer the most engaging and developmental products. As sustainability becomes a growing concern, many players are focusing on eco-friendly materials and packaging, aligning their offerings with consumer demand for environmentally conscious products. The increasing popularity of online shopping is further intensifying competition, as digital retail platforms allow companies to reach global markets more easily and engage with consumers directly. This highly dynamic and fast-evolving market requires companies to stay adaptable and forward-thinking in order to maintain their positions.
Recent Developments
- In March 2025, the LEGO Group launched a wide range of new sets, including LEGO Architecture, LEGO Art, and LEGO Formula 1, with over 40 sets released on March 1st, including the Trevi Fountain and several Formula 1 Speed Champions sets.
- In March 2025, MGA Entertainment's Little Tikes brand announced a partnership with BBC Studios to launch a line of Bluey-inspired toys, including the Bluey Grannies Car Coupe, Bluey Bushland Adventures Splash Pad, Bluey Beach Day Sand Box, and Bluey Beach Water Table.
- In March 2025, the LEGO Group announced a new multi-year partnership with The Pokémon Company International to bring LEGO Pokémon sets starting in 2026.
- In March 2025, Spin Master announced the renewal of its global master toy licensee agreement with DreamWorks Animation for Gabby's Dollhouse.
- In March 2025, Hasbro participated in the North American International Toy Fair, showcasing new products and collaborations, including a PLAY-DOH Barbie line and Marvel's Iron Man toys.
- In March 2025, Mattel renewed its multi-year global licensing agreement with Disney for Toy Story, planning new products for the franchise's 30th anniversary and Toy Story 5.
Market Concentration & Characteristics
The global toy market is characterized by a moderate level of market concentration, with a few large multinational companies dominating the industry, while numerous smaller players cater to niche segments. The leading companies hold significant market share due to their extensive product portfolios, strong brand recognition, and widespread distribution networks. These companies focus on innovation, including the integration of technology in toys, and are continuously expanding their reach through strategic partnerships, acquisitions, and e-commerce channels. Despite the dominance of large players, the market also exhibits characteristics of fragmentation, with numerous regional and smaller brands offering specialized products such as educational toys, eco-friendly options, and licensed collectibles. Consumer preferences are increasingly influenced by trends in technology, sustainability, and educational value, which are pushing companies to adapt their offerings. The competitive landscape is marked by ongoing product innovation, shifting consumer demands, and the increasing importance of online retail channels.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Age Group, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global toy market is expected to continue growing at a steady pace, driven by increasing demand for educational and interactive toys.
- E-commerce will play an increasingly important role, with online sales expected to account for a larger share of total toy sales.
- Consumer preferences will shift toward toys that offer both entertainment and developmental benefits, particularly in STEM education.
- Sustainable and eco-friendly toys will gain more popularity as environmental awareness continues to rise among consumers.
- Technological integration, including augmented reality, robotics, and AI, will become more prevalent in toys, enhancing interactivity and engagement.
- The demand for collectible and nostalgic toys will grow, particularly among adult consumers and collectors.
- Asia-Pacific will remain the fastest-growing region, driven by urbanization, rising disposable incomes, and evolving consumer preferences.
- Licensing agreements with entertainment franchises will continue to fuel demand for toys based on popular movies, TV shows, and video games.
- Safety and regulatory compliance will remain critical, with companies focusing on ensuring their products meet stringent safety standards.
- The market will see increased competition from both traditional toy manufacturers and new entrants, particularly from digital and tech-driven startups.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Toys
The integration of smart technology, robotics, augmented reality (AR), and artificial intelligence (AI) into toys is creating new interactive and educational experiences, attracting tech-savvy consumers and driving market growth.
E-commerce Expansion
The rise of online retail platforms has made toys more accessible to a global consumer base, offering convenience, wider selection, and personalized recommendations, which has significantly boosted sales, especially post-pandemic.
Rising Disposable Incomes and Urbanization
Increasing disposable incomes, particularly in emerging markets like Asia-Pacific, are enabling more families to spend on both traditional and innovative toys, while urbanization is expanding the consumer base and demand for diverse toy categories.
Shift Toward Educational and STEM Toys
Growing parental emphasis on toys that combine entertainment with developmental and educational value, especially in STEM fields, is reshaping product offerings and fueling demand for toys that foster learning and creativity.
Sustainability and Eco-friendly Toy Demand
Heightened environmental awareness among consumers is driving demand for toys made from sustainable, biodegradable, or recycled materials, prompting manufacturers to innovate with eco-friendly products and packaging.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Toy Market?
What factors are driving the growth of the Global Toy Market?
What are the key segments within the Global Toy Market?
What are some challenges faced by the Global Toy Market?
Who are the major players in the Global Toy Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Plastic
- 1.2.2 Wooden
- 1.2.3 Metal
- 1.2.4 Fabric
- 1.2.5 Biodegradable/Organic Materials
- 1.3 By Age Group
- 1.3.1 0 to Below 3 Years
- 1.3.2 3 to Below 5 Years
- 1.3.3 5 to Below 12 Years
- 1.3.4 13 to Below 20 Years
- 1.3.5 20+ Years
- 1.4 By Product Type
- 1.4.1 Building & Construction Set
- 1.4.2 Dolls
- 1.4.3 Infant & Preschool Toys
- 1.4.4 Outdoor & Sports Toys
- 1.4.5 Games & Puzzles
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 316.14 Billion → 2032: USD 445.97 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Toy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Toy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Toy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Toy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Toy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Toy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Toy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Toy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 316.14 Billion → 2032: USD 445.97 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Toy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Plastic
- 12.3.7.2 Wooden
- 12.3.7.3 Metal
- 12.3.7.4 Fabric
- 12.3.7.5 Biodegradable/Organic Materials
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 0 to Below 3 Years
- 12.4.7.2 3 to Below 5 Years
- 12.4.7.3 5 to Below 12 Years
- 12.4.7.4 13 to Below 20 Years
- 12.4.7.5 20+ Years
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Building & Construction Set
- 12.5.7.2 Dolls
- 12.5.7.3 Infant & Preschool Toys
- 12.5.7.4 Outdoor & Sports Toys
- 12.5.7.5 Games & Puzzles
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Toy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Toy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Toy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 LEGO Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Hasbro
- 17.4 MGA Entertainment Inc
- 17.5 Mattel
- 17.6 Spin Master
- 17.7 Moose Toys
- 17.8 Tomy Company Ltd.
- 17.9 Funko
- 17.10 Bandai Namco Holdings Inc.
- 17.11 JAKKS Pacific, Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
