
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Writing Instruments Market Size 2023 | USD 163.23 million |
| Australia Writing Instruments Market, CAGR | 11.50% |
| Australia Writing Instruments Market Size 2032 | SD 435.28 million |
Market Overview
Australia Writing Instruments Market size was valued at USD 163.23 million in 2023 and is anticipated to reach USD 435.28 million by 2032, at a CAGR of 11.50% during the forecast period (2023-2032).
The Australia writing instruments market is experiencing strong growth due to several key drivers and evolving trends. Increasing demand for premium and ergonomic writing tools, particularly among professionals and students, is significantly boosting market expansion. The rise in creative and artistic activities, such as journaling, sketching, and calligraphy, has further fueled consumer interest in specialty pens and markers. Educational reforms and a growing emphasis on handwriting in early learning curricula also support market growth. Additionally, sustainability trends are encouraging manufacturers to develop eco-friendly and refillable products, aligning with consumer preferences for environmentally responsible choices. The corporate sector’s rising investment in customized stationery for branding and gifting purposes adds another layer of demand. Moreover, digital detox trends have led consumers to revalue traditional writing experiences, thereby revitalizing interest in high-quality instruments. These factors collectively contribute to the consistent growth of the writing instruments market in Australia across various end-user segments.
The Australia writing instruments market exhibits strong regional diversity, with major demand concentrated in urbanized and educationally advanced states such as New South Wales, Victoria, Queensland, and Western Australia. These regions benefit from high student populations, robust academic infrastructure, and growing professional sectors, all of which contribute to sustained consumption of writing tools. The market also reflects evolving consumer preferences for sustainable, ergonomic, and premium products across the country. Prominent players operating in the Australian writing instruments market include global and domestic brands such as Lamy, Montblanc, Waterman, Faber-Castell, Montegrappa, Pelikan, Kaweco, Diplomat, Aurora, Sheaffer, Cello Pens, and Robert Oster. These companies compete on innovation, product quality, and brand value, offering a wide range of pens, pencils, markers, and art supplies. Additionally, the growing popularity of online shopping and specialty stationery boutiques has enhanced product accessibility, enabling both established brands and niche players to expand their consumer base nationwide.
Market Insights
- The Australia writing instruments market was valued at USD 163.23 million in 2023 and is projected to reach USD 435.28 million by 2032, growing at a CAGR of 11.50% from 2023 to 2032.
- The Global Writing Instruments market was valued at USD 22,000.00 million in 2023 and is expected to reach USD 57,196.01 million by 2032, growing at a CAGR of 11.20% during the forecast period.
- Increased focus on education, rising literacy rates, and government investment in schools are key drivers boosting demand for writing instruments.
- Consumers are showing growing interest in eco-friendly, refillable, and premium-quality pens and pencils, shaping the market's product innovation trends.
- Digital and e-commerce channels are expanding the reach of writing instruments, with online platforms supporting both global and local brands.
- The market faces restraints such as increasing digitalization in classrooms and workplaces, reducing dependence on traditional stationery.
- New South Wales, Victoria, Queensland, and Western Australia are the leading regional markets due to strong educational infrastructure and urban population.
- Key players include Lamy, Montblanc, Faber-Castell, Waterman, Pelikan, and Robert Oster, competing through quality, brand positioning, and product variety.
Report Scope
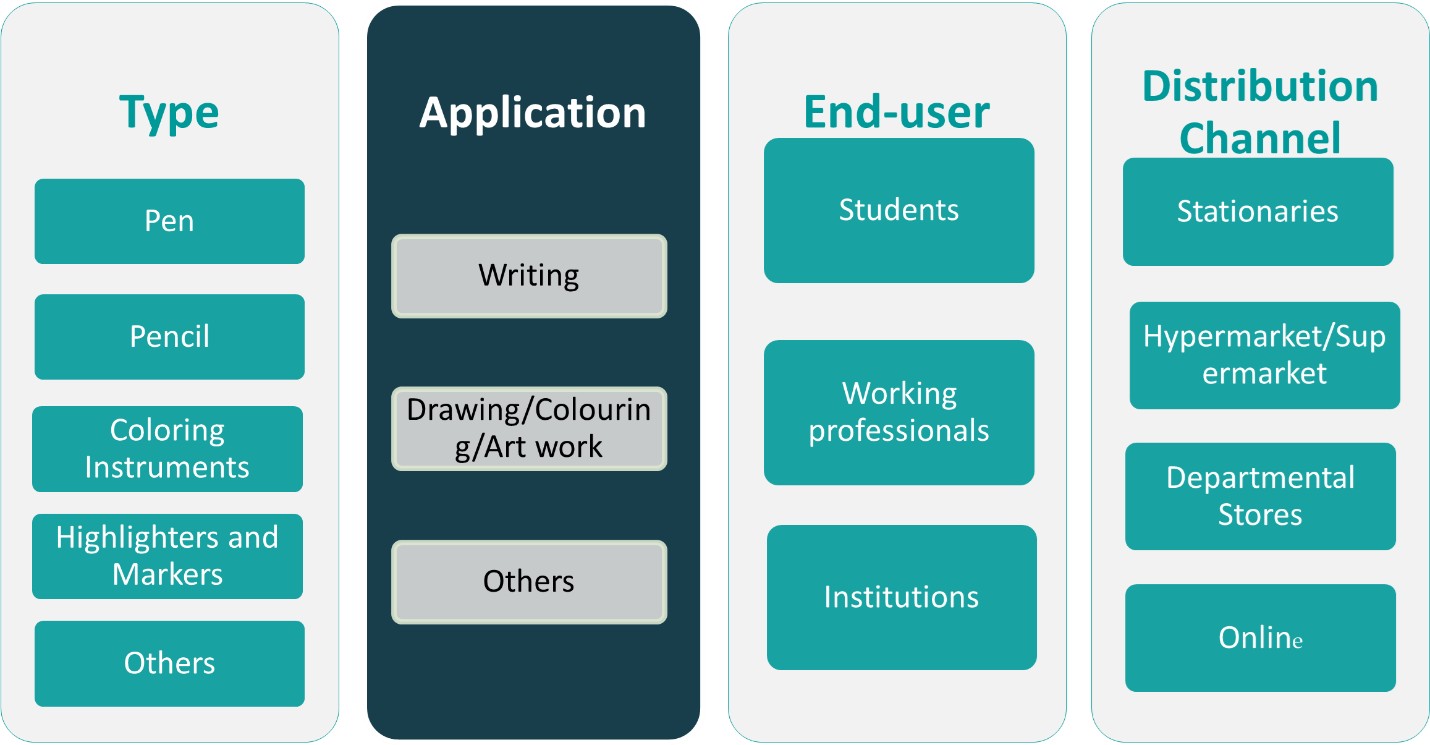
This report segments the Australia Writing Instruments Market as follows:
Market Drivers
Rising Demand from Educational Institutions
One of the primary drivers of the Australia writing instruments market is the consistent demand from the education sector. Schools, colleges, and universities continue to rely heavily on writing instruments for day-to-day academic activities, examinations, and creative projects. While digital devices have become increasingly integrated into learning environments, traditional writing tools remain essential for foundational learning, particularly in early education. Writing plays a critical role in cognitive development, and the Australian curriculum places strong emphasis on handwriting skills in the early years. This has led to sustained consumption of pens, pencils, erasers, and markers across both public and private institutions. Furthermore, educational reforms that support inclusive and activity-based learning have increased the adoption of various types of writing tools, including color-coded and ergonomically designed products for younger children.
Increasing Popularity of Premium and Customized Writing Tools
The rising popularity of premium and personalized writing instruments is significantly influencing market growth. For instance, brands like Pilot and Montblanc have introduced limited-edition collections and engraving services that cater to professional and gifting segments. Consumers in Australia are increasingly seeking writing tools that reflect their individual style, status, and preferences, leading to a surge in demand for luxury pens, stylized markers, and customized stationery. Brands are responding by launching limited-edition collections, engraving services, and stylish packaging that cater to both professional and gifting segments. The growing corporate gifting culture also contributes to this trend, as businesses use branded writing instruments as promotional tools to reinforce their brand identity. In addition, consumers view high-end writing tools as collectible items or thoughtful gifts for occasions such as graduations and career milestones. This rising appreciation for craftsmanship and individuality is reshaping the value perception around writing instruments in the Australian market.
Creative Expression and Digital Detox Trends
A renewed interest in creative expression and analog experiences is fueling demand for writing instruments in Australia. For instance, the Australia Council for the Arts reports that activities like journaling and calligraphy have gained popularity as part of the "digital detox" movement. As consumers seek balance from screen-dominated routines, activities such as journaling, calligraphy, bullet journaling, and sketching have gained popularity across age groups. Writing instruments such as fine liners, brush pens, fountain pens, and sketch pencils are being embraced by hobbyists and artists alike. Social media platforms and influencer-driven content have further amplified the popularity of hand-lettering and artistic writing, driving sales of specialty pens and design-focused tools. These evolving consumer habits are reshaping the market, positioning writing instruments not just as utility products but as tools for creativity and well-being.
Emphasis on Sustainable and Eco-Friendly Products
Sustainability has become a central theme in consumer behavior, and this trend is driving innovation in the writing instruments market in Australia. Customers are becoming increasingly aware of the environmental impact of disposable plastic pens and markers, prompting a shift toward biodegradable, refillable, and recyclable products. Manufacturers are responding by offering eco-friendly alternatives made from sustainable materials such as bamboo, recycled paper, or bioplastics. Refillable pens, erasable markers, and non-toxic inks are gaining popularity, particularly among environmentally conscious buyers, educational institutions, and eco-friendly organizations. Additionally, regulatory support for reducing single-use plastics further encourages both consumers and manufacturers to embrace sustainable options. This growing green movement is expected to remain a key driver of market expansion over the coming years.
Market Trends
Sustainability Driving Product Innovation
The growing emphasis on environmental sustainability is playing a pivotal role in shaping product development within the Australia writing instruments market. For instance, the Australian Government’s National Plastics Plan encourages the reduction of single-use plastics, prompting manufacturers to design pens and markers using biodegradable plastics, bamboo, and recycled paper. With rising environmental awareness among consumers and increased scrutiny of plastic waste, demand for eco-friendly and recyclable products is steadily increasing. Government policies promoting sustainability and waste reduction further support this shift. Additionally, educational institutions and corporate organizations are beginning to adopt green procurement policies, encouraging the use of sustainable stationery. This trend is not only opening new opportunities for innovation but also enabling brands to differentiate themselves in a highly competitive market. Companies that successfully communicate their commitment to environmental responsibility are likely to foster brand loyalty, especially among younger, eco-conscious consumers.
Evolving Retail Landscape and Digital Sales Channels
The retail distribution of writing instruments in Australia is rapidly shifting, with e-commerce and omnichannel retailing emerging as dominant forces. For instance, the Australian Bureau of Statistics reports a steady increase in online retail turnover, driven by platforms like Amazon and eBay. Consumers are increasingly turning to online platforms to explore a wider product range, compare prices, and access exclusive online deals. This shift has prompted brands to strengthen their digital presence through direct-to-consumer websites, online marketplaces, and social media channels. Retailers are leveraging advanced analytics and personalization tools to tailor product recommendations and enhance customer engagement. Furthermore, the hybrid retail model-combining physical stores with online capabilities-is becoming more prevalent, allowing consumers to enjoy the convenience of online browsing with the assurance of in-store service. Subscription models for office and school supplies, especially post-pandemic, are also gaining traction. As digital penetration deepens across urban and regional Australia, writing instrument brands are investing in logistics, digital marketing, and user experience to optimize their reach and performance in this evolving retail environment.
Rise in Demand for Premium and Personalized Writing Instruments
There is a growing consumer preference in Australia for high-end, aesthetically pleasing, and customizable writing instruments. This trend is particularly visible among professionals, gift buyers, and collectors who value craftsmanship, branding, and exclusivity. As a result, luxury pen brands are expanding their presence, offering pens with premium materials such as gold, lacquer, and fine resins, alongside features like ergonomic designs and smooth ink technology. Furthermore, the trend of personalization-such as name engraving, corporate logos, and customized packaging-has become increasingly popular for both individual gifting and corporate promotions. The gifting culture, especially during festivals and business events, is fueling the market for personalized writing instruments. This trend also aligns with the broader consumer movement toward self-expression and uniqueness, encouraging manufacturers to offer bespoke services and limited-edition product lines that enhance emotional value and perceived prestige.
Technological Convergence with Writing Instruments
The integration of digital technology with traditional writing tools is transforming the landscape of the Australia writing instruments market. Smart pens and styluses that digitize handwritten notes in real time, sync with mobile applications, and offer handwriting-to-text conversion are witnessing increased adoption among tech-savvy users. These tools appeal to both students and professionals seeking efficiency in note-taking and digital organization. Hybrid devices that bridge the gap between analog writing and digital interfaces are enabling seamless workflows across paper and screen. As remote learning and hybrid working environments become more entrenched, demand for these tech-integrated tools is likely to grow. Manufacturers are investing in R&D to enhance compatibility with popular digital platforms and improve battery life, storage capacity, and real-time connectivity. This evolving trend is expected to blur the lines between digital and traditional tools while fostering innovation in writing accessories.
Market Challenges Analysis
Rising Digitalization and Decline in Traditional Usage
One of the most significant challenges confronting the Australia writing instruments market is the rapid shift toward digitalization. For instance, the Australian Bureau of Statistics highlights that digital activity accounted for 6.1% of the total economy in 2020–21, reflecting the growing integration of digital tools in schools and workplaces. Government-backed initiatives like the Digital Education Revolution have equipped classrooms with laptops and tablets, reducing reliance on traditional writing tools. Similarly, businesses are increasingly adopting paperless workflows to streamline operations and cut costs, further diminishing the demand for pens and pencils. This shift, while fostering efficiency, presents a long-term challenge for manufacturers to innovate and adapt to changing consumer preferences.
Intense Competition and Price Sensitivity
The Australia writing instruments market also faces intense competition, both from established international brands and low-cost imports. Local manufacturers often struggle to match the economies of scale and pricing strategies of global players, making it difficult to maintain market share. In addition, consumer price sensitivity, particularly in the mass-market segment, forces companies to keep prices low while maintaining quality-a balance that is not always sustainable. Retailers also face the challenge of differentiating their offerings in a market saturated with similar products. The proliferation of private-label brands and e-commerce platforms offering discounted prices further compresses profit margins. Moreover, the rising cost of raw materials, especially sustainable and eco-friendly alternatives, adds to operational burdens. These competitive pressures necessitate constant innovation and marketing investment, which can strain resources, especially for small and medium-sized players in the industry.
Market Opportunities
The Australia writing instruments market presents considerable growth opportunities driven by changing consumer behavior, education sector reforms, and rising demand for premium products. With the ongoing emphasis on personalized learning and early childhood education, demand for writing instruments-especially ergonomic pens, markers, and pencils-is on the rise. Schools are increasingly integrating creative and visual learning techniques that require a wide variety of stationery, including color-coded pens, sketch pens, and highlighters. Moreover, the expansion of the homeschooling sector and increased parental spending on quality educational tools are driving consistent product consumption. As educational institutions continue to invest in quality teaching aids and stationery, manufacturers have the chance to develop innovative, child-friendly, and sustainable writing products that cater to modern academic needs.
Additionally, the growth of Australia’s business gifting culture and the emergence of niche luxury and customizable stationery brands offer significant avenues for market expansion. Professionals and corporations are showing a growing preference for aesthetically designed, high-quality pens and markers, especially for branding, awards, and executive gifting. This trend is also amplified by rising disposable incomes and a shift towards premium consumerism in urban markets. Furthermore, the digital evolution of retail has opened up direct-to-consumer models, allowing small and emerging brands to target specific consumer segments with specialized offerings. As e-commerce and omnichannel marketing continue to evolve, manufacturers have the opportunity to expand their footprint by leveraging online sales platforms, influencer partnerships, and data-driven marketing strategies. Innovations such as smart pens and styluses, which integrate with mobile devices for note digitization, are also gaining traction, particularly among students and professionals. By investing in product diversification and digital engagement, players in the writing instruments market can capture emerging consumer needs and strengthen their market position in Australia.
Market Segmentation Analysis:
By Type:
The Australia writing instruments market is segmented by type into pens, pencils, coloring instruments, highlighters and markers, and others. Among these, pens account for the largest market share, driven by their widespread use in educational institutions, offices, and homes. Ballpoint and gel pens are particularly popular due to their affordability, ease of use, and availability in various designs. Pencils follow closely, especially mechanical and graphite types, which are frequently used by students and professionals. Meanwhile, the coloring instruments segment-including crayons, colored pencils, and sketch pens-is experiencing growing demand, particularly in the education and hobbyist segments. Parents and educators are increasingly investing in creative tools that support children's development and learning, boosting consumption of these products. Highlighters and markers are also gaining traction in academic and professional settings due to their utility in note organization and presentations. As consumer preferences shift towards ergonomic, eco-friendly, and refillable options, each product segment offers manufacturers opportunities for innovation and market penetration.
By Application:
Based on application, the market is categorized into writing, drawing/colouring/art work, and others. Writing remains the dominant segment, largely fueled by consistent demand from students, teachers, and working professionals. Even in the digital age, writing instruments retain essential functions in academic assessments, note-taking, form-filling, and business communications. This segment benefits from both disposable and refillable product lines, with customers increasingly showing interest in sustainable options. The drawing, colouring, and art work segment is expanding steadily, supported by rising participation in creative hobbies, art education, and DIY crafts. Increased awareness of art's role in cognitive development among children and its therapeutic value for adults further boosts this segment. Additionally, products under the "others" category-such as calligraphy pens and styluses-are gaining popularity among niche audiences, including artists and design professionals. The diversification of use cases across education, office, and recreational segments enables manufacturers to tailor products to specific consumer needs and tap into emerging lifestyle-driven trends.
Segments:
Based on Type:
- Pen
- Pencil
- Coloring Instruments
- Highlighters and Markers
- Others
Based on Application:
- Writing
- Drawing/Colouring/Art Work
- Others
Based on End- User:
- Students
- Working Professionals
- Institutions
Based on Distribution Channel:
- Stationaries
- Hypermarket/Supermarket
- Departmental Stores
- Online
Based on the Geography:
- New South Wales
- Victoria
- Queensland
- Western Australia (WA)
- South Australia
Regional Analysis
New South Wales
New South Wales holds the largest share in the Australia writing instruments market, accounting for approximately 31% of the total market in 2023. As the most populous state and a major educational and business hub, New South Wales drives strong demand for writing tools across schools, universities, and corporate offices. The presence of key cities like Sydney, which houses numerous academic institutions and multinational corporations, contributes significantly to consumption. Furthermore, the rise in enrollment across primary and secondary schools, coupled with increased parental investment in quality educational tools, is boosting the market for pens, pencils, markers, and coloring instruments. E-commerce penetration and a growing preference for premium and eco-friendly stationery products are also gaining momentum in this region, encouraging retailers to expand both online and offline distribution.
Victoria
Victoria commands a solid 26% share of the Australia writing instruments market, driven by its well-established education sector and thriving urban population. Melbourne, as the capital city, plays a critical role in generating high product demand across schools, design institutes, and office spaces. The market benefits from a culturally rich and creative population that actively engages in drawing, design, and other art-related activities-further propelling demand for coloring instruments, highlighters, and specialty pens. The adoption of sustainable and ergonomic stationery products is also increasing among Victorian consumers, aligning with broader environmental awareness across the state. Additionally, Victoria’s strategic retail infrastructure and strong digital commerce capabilities make it a favorable landscape for emerging stationery brands and global players seeking regional expansion.
Queensland
Queensland contributes approximately 18% to the national writing instruments market, supported by growing urbanization, rising school enrollment, and increased office activity. Brisbane, as the central economic zone, experiences steady demand from students and working professionals. The region is witnessing a surge in after-school creative programs and community-based art workshops, which in turn is stimulating demand for coloring pens, sketch markers, and drawing tools. The growing focus on early childhood education and student well-being is prompting educators and parents to seek high-quality, non-toxic, and ergonomic writing products. Although the market here is less saturated than in NSW and Victoria, increasing digital awareness and e-commerce accessibility are opening new avenues for retailers and manufacturers to strengthen their presence in the region.
Western Australia
Western Australia, led by Perth as the economic and administrative center, accounts for 12% of the Australia writing instruments market. Though smaller in comparison to the eastern states, the region maintains stable demand due to consistent investment in education and regional development programs. The growing mining and industrial workforce also contributes to demand for practical, durable writing instruments used in fieldwork and technical documentation. Additionally, local schools and universities have been adopting a hybrid teaching approach, integrating digital and traditional learning, which sustains demand for pens, pencils, and markers. Retail penetration remains moderate, with increasing consumer preference for online shopping of stationery items. As awareness of sustainable and smart writing tools spreads, Western Australia offers opportunities for niche players and digital-first brands aiming to serve targeted demographics through tailored offerings.
Key Player Analysis
- Lamy
- Montblanc
- Waterman
- Faber-Castell
- Montegrappa
- Pelikan
- Kaweco
- Diplomat
- Aurora
- Sheaffer
- Cello Pens
- Robert Oster
Competitive Analysis
The Australia writing instruments market is highly competitive, with both global and local brands vying for market share through innovation, brand positioning, and product quality. Leading players in the market include Lamy, Montblanc, Waterman, Faber-Castell, Montegrappa, Pelikan, Kaweco, Diplomat, Aurora, Sheaffer, Cello Pens, and Robert Oster. These companies dominate with their diverse product portfolios ranging from premium luxury pens to everyday writing tools, catering to a wide spectrum of consumer preferences. Premium brands dominate the high-end segment, focusing on luxury, craftsmanship, and customization to appeal to professionals and collectors. These brands prioritize exclusivity, craftsmanship, and a strong brand identity, providing consumers with high-quality writing tools that offer superior performance and longevity. On the other hand, mid-range brands emphasize affordability and value for money, offering a balance between quality and price. They cater to students, professionals, and everyday users, focusing on providing reliable, durable, and ergonomic writing instruments. The demand for sustainable and eco-friendly products is also influencing the competitive landscape, with several brands introducing environmentally friendly options such as refillable pens and recyclable materials. In addition, online retail and digital marketing have become crucial in expanding brand reach, making it easier for both well-established and emerging brands to access a wider audience. Competition is also fueled by the growing trend of personalization, with several companies offering customizable writing instruments to cater to individual preferences. The continuous product innovation and adoption of new technologies ensure that the market remains dynamic and competitive.
Recent Developments
- In February 2023, Zebra Pen Corp., a prominent player in the industry, announced its partnership with Liqui-Mark. This collaboration aims to enhance distribution aspects in the market, bringing about a new era of possibilities.
- In July 2023, Montblanc launched its exclusive "Meisterstück 146 LeGrand" fountain pen, featuring a handcrafted design with intricate detailing, addressing the rising demand for personalized, high-end writing tools in luxury segments.
- In April 2022, Zebra Pen Corp. announced the launch of its official website. This step was taken by the company to enhance user experience, increase e-commerce functionality, and improve brand communication, among other objectives.
Market Concentration & Characteristics
The market concentration of Australia’s writing instruments sector is moderately fragmented, with a mix of established global brands and local players competing across various price points and product categories. While a few premium brands dominate the high-end market, offering luxury, handcrafted, and customizable products, mid-range and budget-friendly segments are occupied by numerous players, catering to mass-market demand. The presence of both large international brands and smaller, niche players leads to a diverse product landscape, from everyday writing tools to specialized instruments for art and design. The market is characterized by a strong emphasis on innovation, particularly in eco-friendly, ergonomic, and refillable products, as consumer preferences evolve towards sustainability and practicality. Additionally, the rise of e-commerce platforms and digital marketing has intensified competition, enabling smaller and emerging brands to compete effectively with established names. Overall, the Australian market remains dynamic, with steady growth driven by a combination of local preferences and global trends
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The trend of digital integration in writing tools, such as smart pens and digital notebooks, is expected to expand significantly.
- Manufacturers will increasingly focus on ergonomic designs to enhance comfort, catering to both professional and educational users.
- The demand for specialty writing instruments, such as fountain pens and high-end calligraphy tools, is expected to grow among hobbyists and collectors.
- Retailers are expanding their presence through e-commerce platforms to reach a broader consumer base, increasing accessibility.
- The market will likely see more collaborations between writing instrument brands and other lifestyle or luxury brands, enhancing product appeal.
- With increasing awareness of sustainability, the focus on refillable and long-lasting writing instruments will intensify.
- Growth in the demand for writing instruments in the arts and design sectors will continue, especially among younger demographics.
- The market will witness a shift towards greater product variety, with brands offering a range of colors, styles, and materials.
- Advances in ink technology, including smudge-proof and fade-resistant formulas, are expected to enhance product offerings.
- As the overall writing instruments market expands, regional players will play a larger role by introducing locally relevant designs and products.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Writing Instruments?
What factors are driving the growth of the Australia Writing Instruments?
What are the key segments within the Australia Writing Instruments?
Who are the major players in the Australia Writing Instruments?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Writing Instruments Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Australia Writing Instruments Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 163.23 million → 2032: USD 435.28 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Writing Instruments Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Writing Instruments Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Writing Instruments Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Australia Writing Instruments Drivers
- 3.3 Australia Writing Instruments Restraints & Challenges
- 3.4 Australia Writing Instruments Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Writing Instruments Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Writing Instruments Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Writing Instruments category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Writing Instruments Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Australia Writing Instruments Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Australia Writing Instruments in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Writing Instruments Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Australia Writing Instruments Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Australia Writing Instruments Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Writing Instruments (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Australia Writing Instruments
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Australia Writing Instruments – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Australia Writing Instruments – Priority Domestic Market 1
Chapter 10. Australia Writing Instruments – Priority Domestic Market 2
Chapter 11. Australia Writing Instruments – Priority Domestic Market 3
Chapter 12. Australia Writing Instruments – Priority Domestic Market 4
Chapter 13. Australia Writing Instruments Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
