
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automatic Teller Machines (ATM) Market Size 2023 | USD 22610 million |
| Automatic Teller Machines (ATM) Market, CAGR | 8.6% |
| Automatic Teller Machines (ATM) Market Size 2032 | USD 43746.08 million |
Market Overview:
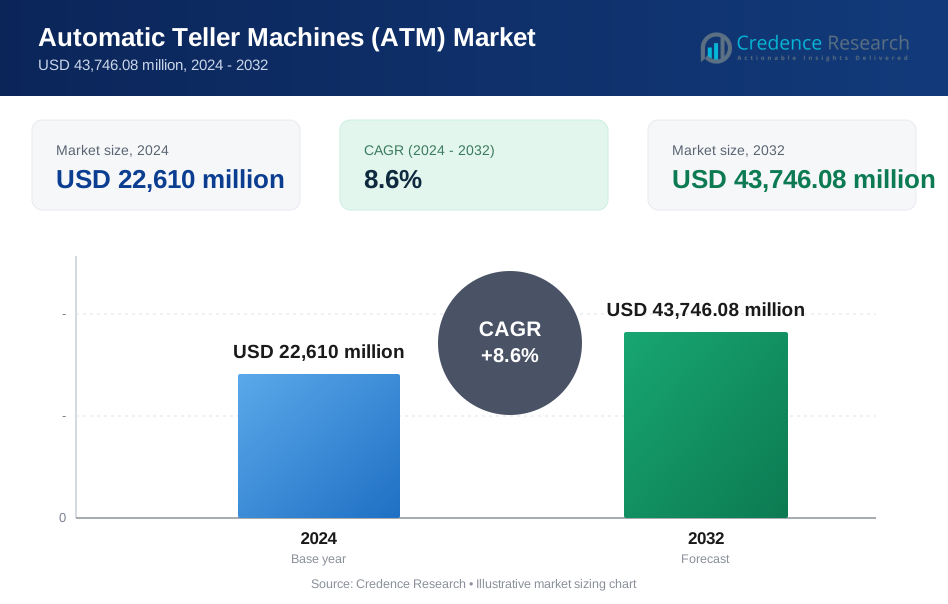
The Automatic Teller Machines (ATM) Market is projected to grow from USD 22610 million in 2024 to an estimated USD 43746.08 million by 2032, with a compound annual growth rate (CAGR) of 8.6% from 2024 to 2032.
Key drivers in the ATM market include the continuous demand for cash-based transactions, especially in regions with lower adoption of digital payment methods, and the increasing trend of ATM installations in remote and rural areas. Additionally, technological advancements, such as cash recycling ATMs and interactive teller machines (ITMs), have bolstered the market by offering enhanced services and cost-efficiency to financial institutions. The rise of smart ATMs equipped with biometric and advanced security features has also responded to growing security concerns, making ATMs more accessible and secure. Moreover, strategic partnerships between banks and non-banking financial institutions for ATM deployment, particularly in locations with limited financial services, have further spurred market growth.
Regionally, the ATM market shows diverse dynamics. Asia-Pacific leads in terms of market size, driven by the high population density and large unbanked population in countries like India, China, and Southeast Asian nations. These countries are actively expanding their ATM networks to promote financial inclusion. North America and Europe, while relatively mature markets, continue to see growth with the adoption of advanced ATMs for enhanced security and customer experience. Latin America and Africa present promising opportunities due to increasing ATM deployments aimed at providing financial services to underserved areas. The Middle East has also seen a rise in demand, supported by government initiatives to improve financial infrastructure, particularly in the Gulf countries.
Market Drivers:
Increasing Demand for Cash Transactions in Emerging Economies:
The demand for cash transactions remains strong in many emerging economies, where cash is still a preferred mode of payment. In India, for instance, as of February 2024, there were 2.19 lakh (219,000) ATMs deployed by Indian banks, Despite the global shift towards digital banking, a significant portion of the population in these regions lacks access to digital payment methods or internet banking services. As a result, Automatic Teller Machines (ATMs) play a crucial role in providing accessible financial services, particularly in rural and semi-urban areas where traditional banking infrastructure is limited. Financial institutions and governments are heavily investing in expanding ATM networks to meet this demand and enhance financial inclusion, thereby driving steady growth in the ATM market.
Advancements in ATM Technology:
Technological advancements have significantly reshaped the ATM market, making machines more efficient, user-friendly, and secure. The introduction of innovative features such as cash recycling, which allows ATMs to recirculate deposited cash, has reduced operational costs for banks while improving ATM uptime and availability for customers. Moreover, smart ATMs equipped with biometric authentication, facial recognition, and touchless operations address rising concerns about transaction security. Interactive Teller Machines (ITMs), which provide enhanced services like video calling and on-screen assistance, offer a more personalized banking experience. These technological upgrades not only enhance customer satisfaction but also help financial institutions reduce costs, boosting the adoption of advanced ATMs in the market.
Growing Focus on Financial Inclusion Initiatives:
Financial inclusion has become a key priority for governments and financial institutions worldwide. In many developing regions, large portions of the population remain unbanked, often due to limited access to banking infrastructure. To address this, governments and banks are working together to expand ATM networks, particularly in underserved and remote areas. For example, in Bangladesh, ongoing financial inclusion efforts have made it one of the fastest-growing ATM markets in Asia, expanding by 11% in 2023. The deployment of mobile ATMs and solar-powered machines has emerged as a viable solution to reach populations in areas with limited connectivity or power supply. This focus on financial inclusion initiatives has bolstered ATM deployment in several regions, allowing a wider population to access essential banking services. Consequently, these initiatives are accelerating ATM market growth by increasing demand and usage rates, particularly in rural and economically disadvantaged areas.
Increased Emphasis on Security and Fraud Prevention:
Security and fraud prevention have become critical concerns in the ATM industry due to the rising incidence of ATM-related crimes and fraud. Financial institutions are increasingly investing in advanced security technologies to protect both customers and ATMs from theft, skimming, and cyber threats. Modern ATMs are now equipped with sophisticated security measures such as anti-skimming devices, biometric authentication, PIN shields, and encrypted communication channels. Additionally, ATMs with remote monitoring capabilities allow banks to respond quickly to security incidents, enhancing operational security. This heightened emphasis on security is not only improving customer trust but also encouraging further investments in ATM infrastructure, as secure and reliable ATMs remain an essential service for both banks and consumers.
Market Trends:
Rise of Contactless and Biometric ATMs:
As technology evolves, contactless and biometric features in ATMs are gaining traction, offering users more secure and convenient transaction methods. In response to the rising demand for touchless solutions, particularly following the global health concerns in recent years, ATMs are increasingly being upgraded with contactless capabilities. These ATMs allow users to initiate transactions using mobile devices or contactless cards, minimizing physical interaction with the machine. Additionally, biometric ATMs that utilize fingerprint or facial recognition for identity verification are also becoming more popular, adding an extra layer of security. This trend is driven by both consumer demand for convenience and financial institutions’ desire to enhance security and protect against fraud.
Expansion of ATM Networks in Rural and Underbanked Regions:
The ATM market is witnessing a strong push to expand networks into rural and underbanked regions, primarily driven by financial inclusion efforts. In developing regions, a substantial portion of the population remains unbanked due to limited access to traditional banking services. Governments and financial institutions are actively investing in ATM deployments in these areas to ensure that basic financial services are more widely available. Mobile ATMs and solar-powered ATMs are also being introduced as innovative solutions to overcome infrastructure challenges in remote locations. This expansion trend is expected to play a crucial role in narrowing the financial inclusion gap while also driving ATM market growth.
Increased Adoption of Cash Recycling and Smart ATMs:
Cash recycling and smart ATMs are increasingly being adopted due to their efficiency and cost-saving potential. Cash recycling ATMs allow deposited cash to be recirculated, reducing the frequency and cost of cash replenishment. For instance, Diebold Nixdorf reported that their cash recycling ATMs have significantly reduced cash handling costs for banks. These ATMs not only lower operational expenses for banks but also enhance machine availability, allowing customers more reliable access to cash. Similarly, smart ATMs with interactive and multimedia features provide additional banking services beyond traditional withdrawals and deposits. With options like video calling for customer support, these smart ATMs improve customer experience by offering real-time assistance and enabling more complex transactions. Financial institutions are leveraging these advanced machines to offer enhanced services in a self-service format, aligning with consumer expectations for convenience and efficiency.
Growth of ATM-as-a-Service (AaaS) Models:
ATM-as-a-Service (AaaS) is emerging as a strategic trend in the ATM market, enabling banks to reduce capital expenditures associated with ATM deployment and maintenance. In the AaaS model, third-party service providers manage the entire ATM lifecycle, from installation and maintenance to software updates and cash management. For example, Cardtronics, a leading AaaS provider, manages over 285,000 ATMs worldwide, allowing financial institutions to focus on core business functions. This service-oriented model allows financial institutions to focus on core business functions while outsourcing the operational aspects of ATM management. AaaS also brings flexibility in terms of scaling ATM networks according to demand, making it an appealing option for both large banks and smaller financial institutions. With the growing popularity of outsourced ATM services, AaaS is anticipated to reshape the ATM market landscape, offering a more cost-effective and scalable solution for banks and financial organizations.
Market Restraints and Challenges:
Rising Operational Costs and Maintenance Challenges:
One of the primary restraints in the ATM market is the increasing cost of operating and maintaining ATM networks. Regular maintenance, cash replenishment, security upgrades, and compliance with regulatory standards all add to the operational expenses for financial institutions. ATMs in remote and low-traffic areas, in particular, are often costly to maintain relative to their usage, creating challenges in justifying these investments. Additionally, as technology advances, ATMs require frequent upgrades to meet consumer expectations and security standards, which further increases operational costs and creates financial pressure on banks and service providers.
Shift Toward Digital Payments:
The growing adoption of digital payment methods is creating challenges for the ATM market, as consumers increasingly rely on mobile payments, online banking, and contactless transactions for daily financial activities. The convenience of digital payment solutions has reduced the dependency on cash, especially in urban areas and developed regions. This shift poses a direct challenge to the demand for ATM services, potentially reducing transaction volumes and undermining the market growth. Financial institutions must therefore adapt their ATM strategies to remain relevant, potentially through value-added services or innovative ATM features to offset declining cash usage.
Security Threats and Fraud Risks:
Security remains a significant challenge for the ATM market, as ATM-related fraud and cyber threats continue to evolve. Skimming, card trapping, and cyberattacks on ATM networks threaten both consumer trust and financial institutions’ reputations. Maintaining robust security measures and adapting to new fraud prevention technologies add to the operational complexities and costs for ATM operators. As security risks grow, financial institutions face mounting pressure to implement advanced security protocols, which, while necessary, add another layer of complexity to ATM management. Balancing security investments with cost efficiency remains a critical challenge in sustaining ATM deployments.
Market Segmentation Analysis:
By Screen Size, ATMs with 15" & below screens cater primarily to basic cash withdrawal and deposit functions, appealing to cost-sensitive markets. Meanwhile, ATMs with above 15" screens support advanced, interactive functionalities, such as video assistance and personalized services, which are increasingly favored by financial institutions aiming to enhance user experience and accessibility.
By Deployment, the market divides into Off-site ATMs, On-site ATMs, and Others. Off-site ATMs, located in high-traffic areas like shopping centers, continue to grow as they meet demand for accessible cash services beyond traditional bank branches. On-site ATMs, installed within or near bank branches, cater mainly to existing customers and ensure brand-aligned services. Other deployments include mobile and event-based ATMs, which are key in reaching rural and underserved regions.
By Type, the ATM market comprises Conventional/Bank ATMs, Brown Label ATMs, White Label ATMs, Smart ATMs, and Cash Dispenser ATMs. Conventional and brown label ATMs are cost-effective, catering to standard banking needs, whereas White Label ATMs and Smart ATMs offer extended functionalities, appealing to customers of multiple banks and enhancing accessibility in non-banked locations. Cash Dispenser ATMs provide basic services, ideal for high-volume transactions in cash-dependent regions. This segmentation reflects how the ATM market addresses diverse customer needs and adapts to technology-driven demands for enhanced service experiences.
Segmentation:
By Screen Size:
- 15" & Below
- Above 15"
By Deployment:
- Off-site ATMs
- On-site ATMs
- Others
By Type:
- Conventional/Bank ATMs
- Brown Label ATMs
- White Label ATMs
- Smart ATMs
- Cash Dispenser ATMs
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the global ATM market, driven by mature banking infrastructure and high ATM penetration rates, especially in the United States. The region is estimated to capture around 25% of the market share, with steady demand from both urban and suburban areas. While digital payments have impacted ATM usage in urban settings, off-site and mobile ATMs continue to thrive in rural locations and events. The U.S. leads in deploying advanced ATMs, such as interactive teller machines (ITMs) that offer personalized services through video calling. Canada is also investing in smart ATMs to enhance user experience, contributing to a stable market presence.
Europe
Europe follows closely, accounting for approximately 22% of the global ATM market share. Driven by high levels of financial inclusion and widespread banking networks, countries like the UK, Germany, and France contribute significantly to the region’s ATM installations. However, the increasing adoption of contactless payments and mobile banking apps is challenging traditional ATM usage. To counterbalance this shift, European banks are investing in cash recycling and multifunctional ATMs to streamline services and reduce costs. Additionally, Eastern European countries are expanding ATM deployments in rural and underbanked areas, supporting overall market stability and growth.
Asia-Pacific
Asia-Pacific is the largest and fastest-growing region in the ATM market, holding over 35% of the market share. This growth is propelled by a high population density, especially in countries like China, India, and Indonesia, where cash transactions remain prevalent. Financial inclusion initiatives led by governments and financial institutions drive ATM installations in both urban and rural areas, where access to banking infrastructure can be limited. Advanced ATMs, such as biometric and cash recycling ATMs, are also on the rise as financial institutions in Asia-Pacific seek to improve security and operational efficiency. The market in Asia-Pacific continues to expand rapidly, reflecting the region's significant contribution to global ATM growth.
Latin America
Latin America represents roughly 10% of the global ATM market share, with demand fueled by economic challenges and reliance on cash transactions in several countries. In regions where financial inclusion is low, such as in rural parts of Brazil and Mexico, ATMs serve as critical access points to banking services. While digital payments are growing, cash dependency remains high, sustaining demand for ATMs. The deployment of mobile and solar-powered ATMs is also gaining traction as a solution to serve remote areas. Despite these advances, challenges related to security and operational costs hinder broader market expansion in Latin America.
Middle East and Africa
The Middle East and Africa together account for about 8% of the ATM market share. In these regions, ATMs are essential for extending financial services to underbanked populations, especially in rural and remote areas. Countries like South Africa, the UAE, and Saudi Arabia have seen increased investments in ATMs, driven by government initiatives for financial inclusion and the expansion of banking infrastructure. However, in some parts of Africa, infrastructure challenges and security concerns limit ATM deployment. Nevertheless, the adoption of mobile ATMs and strategic partnerships with non-bank financial entities are emerging as solutions to bridge financial service gaps across these regions.
Key Player Analysis:
- Diebold Nixdorf, Incorporated.
- Fujitsu
- G4S Limited
- Guangzhou KingTeller Technology Co. Ltd.
- Hitachi Channel Solutions, Corp.
- NCR Corporation.
- OKI Electric Industry Co., Ltd.
Competitive Analysis:
The ATM market is highly competitive, with prominent players vying for market share through innovation and strategic partnerships. Major companies like NCR Corporation, Diebold Nixdorf, Hitachi-Omron Terminal Solutions, and Fujitsu lead the market by focusing on technological advancements, such as cash recycling and biometric-enabled ATMs, to meet evolving security and customer service needs. These players compete on the basis of product quality, reliability, and after-sales support, with a strong emphasis on providing integrated solutions for cash management and security. Regional players and Independent ATM Deployers (IADs) also contribute to market competition, especially in emerging economies where ATM installations are expanding rapidly. Partnerships with banks and non-banking financial institutions are common, enabling companies to reach underserved markets. Additionally, as digital payments gain traction, ATM providers are diversifying their offerings to include smart ATMs and managed services, strengthening their position in a dynamic market landscape.
Recent Developments:
- In June 2023, NCR Corporation, a corporate technology provider, partnered with the Members ATM Alliance (MAA) to deliver ATM as a Service (ATMaaS) to credit unions. MAA, a Credit Union Service Organization (CUSO), supports credit unions in ATM management and processing. With NCR's ATMaaS, MAA can streamline its managed services, including operations, deployment, transaction processing, cash management, and software management.
- In February 2023, NCR Corporation renewed and expanded its long-term partnership with Walgreens, a leading global drugstore operator. Under the new agreement, NCR will continue providing ATM services across nearly all Walgreens locations in the U.S., Puerto Rico, and the District of Columbia.
- In January 2023, Hitachi Terminal Solutions India expanded its production capacity for cash recycling machines (CRMs) in Bengaluru, tripling its previous capacity of 1,000 CRMs. These machines, similar to ATMs, also allow users to deposit cash, providing a convenient option for those without bank accounts.
- In November 2022, Diebold Nixdorf, a leading ATM manufacturer, expanded its presence in India with a new manufacturing plant in Bengaluru. This facility focuses on producing the company's DN Series cash dispensing and cash recycling machines.
Market Concentration & Characteristics:
The ATM market is moderately concentrated, with a few major players like NCR Corporation, Diebold Nixdorf, Fujitsu, and Hitachi-Omron Terminal Solutions dominating the landscape through innovation and extensive service portfolios. These established players hold a substantial market share due to their advanced technology, product reliability, and comprehensive customer support. However, competition from regional players and Independent ATM Deployers (IADs) in emerging markets is intensifying as these companies seek to fill gaps in rural and underserved areas. Key market characteristics include a focus on technological advancements, such as biometric security, cash recycling, and interactive teller features, which enhance customer experience and operational efficiency. The shift towards ATM-as-a-Service (ATMaaS) models is also shaping the market, allowing banks and financial institutions to outsource ATM management, reduce operational costs, and expand ATM networks flexibly. This structure supports both established and emerging players in sustaining growth in a dynamic, demand-driven environment.
Report Coverage:
The research report offers an in-depth analysis based on By Screen Size, By Deployment and By Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing focus on financial inclusion will drive ATM installations in rural and underserved regions.
- Rising demand for cash recycling and deposit features will propel the adoption of advanced ATMs globally.
- ATM-as-a-Service (ATMaaS) models will become more prevalent, allowing banks to outsource management and reduce costs.
- Integration of biometric and contactless technology will enhance ATM security and user convenience.
- Expansion of mobile and solar-powered ATMs will improve accessibility in remote areas with limited infrastructure.
- Continued investment in smart ATMs with interactive teller features will cater to evolving consumer expectations.
- Growing digital payment adoption may reduce cash usage but will prompt ATMs to diversify into multifunctional service kiosks.
- Strategic partnerships between banks and non-banking financial institutions will support ATM network expansion.
- Regulatory standards and compliance requirements will continue to shape ATM security and operational protocols.
- Focus on sustainable ATM solutions will increase, with eco-friendly machines gaining attention in environmentally conscious markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Persistent Demand for Cash Transactions in Emerging Economies
In many developing regions, cash remains the primary mode of payment due to limited access to digital banking and internet services. This sustains high demand for ATMs, especially in rural and semi-urban areas where traditional banking infrastructure is lacking.
Technological Advancements in ATM Features
The introduction of cash recycling, biometric authentication, and interactive teller machines (ITMs) has made ATMs more efficient, secure, and user-friendly. These innovations reduce operational costs for banks and enhance customer experience, driving further adoption.
Financial Inclusion Initiatives
Governments and financial institutions are prioritizing financial inclusion by expanding ATM networks into underserved and remote areas. Mobile and solar-powered ATMs are being deployed to reach populations with limited access to banking, significantly boosting market growth.
ATM-as-a-Service (AaaS) and Outsourcing Models
Banks are increasingly adopting AaaS models to outsource ATM management, reducing capital and operational expenditures. This trend allows for flexible scaling of ATM networks and encourages broader deployment, especially by smaller financial institutions.
Enhanced Security and Fraud Prevention Measures
Rising concerns over ATM-related crimes have led to the integration of advanced security features such as anti-skimming devices, biometric authentication, and remote monitoring. These improvements increase consumer trust and support continued investment in ATM infrastructure.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate for the ATM market from 2024 to 2032?
What factors are driving the growth of the ATM market?
Which region holds the largest share of the ATM market?
What are some challenges facing the ATM market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Conventional/Bank ATMs
- 1.2.2 Brown Label ATMs
- 1.2.3 White Label ATMs
- 1.2.4 Smart ATMs
- 1.2.5 Cash Dispenser ATMs
- 1.2.6 Others
- 1.3 By Deployment
- 1.3.1 Off-site ATMs
- 1.3.2 On-site ATMs
- 1.3.3 Others
- 1.4 By Screen Size
- 1.4.1 15" & Below
- 1.4.2 Above 15"
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 22,610 million → 2032: USD 43,746.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automatic Teller Machines (ATM) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automatic Teller Machines (ATM) Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Automatic Teller Machines (ATM) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Automatic Teller Machines (ATM) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automatic Teller Machines (ATM) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automatic Teller Machines (ATM) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automatic Teller Machines (ATM) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automatic Teller Machines (ATM) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 22,610 million → 2032: USD 43,746.08 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automatic Teller Machines (ATM) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Conventional/Bank ATMs
- 12.3.6.2 Brown Label ATMs
- 12.3.6.3 White Label ATMs
- 12.3.6.4 Smart ATMs
- 12.3.6.5 Cash Dispenser ATMs
- 12.3.6.6 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Off-site ATMs
- 12.4.6.2 On-site ATMs
- 12.4.6.3 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Screen Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 15" & Below
- 12.5.6.2 Above 15"
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automatic Teller Machines (ATM) Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automatic Teller Machines (ATM) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automatic Teller Machines (ATM) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Diebold Nixdorf, Incorporated
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Fujitsu
- 17.4 G4S Limited
- 17.5 Guangzhou KingTeller Technology Co. Ltd.
- 17.6 Hitachi Channel Solutions, Corp.
- 17.7 NCR Corporation
- 17.8 OKI Electric Industry Co., Ltd.
- 17.9 Cardtronics
- 17.10 GRG Banking
- 17.11 Triton Systems
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

