
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Cybersecurity Market Size 2024 | USD 2,889.5 Million |
| Automotive Cybersecurity Market, CAGR | 13.70% |
| Automotive Cybersecurity Market Size 2032 | USD 8,070.61 Million |
Market Overview
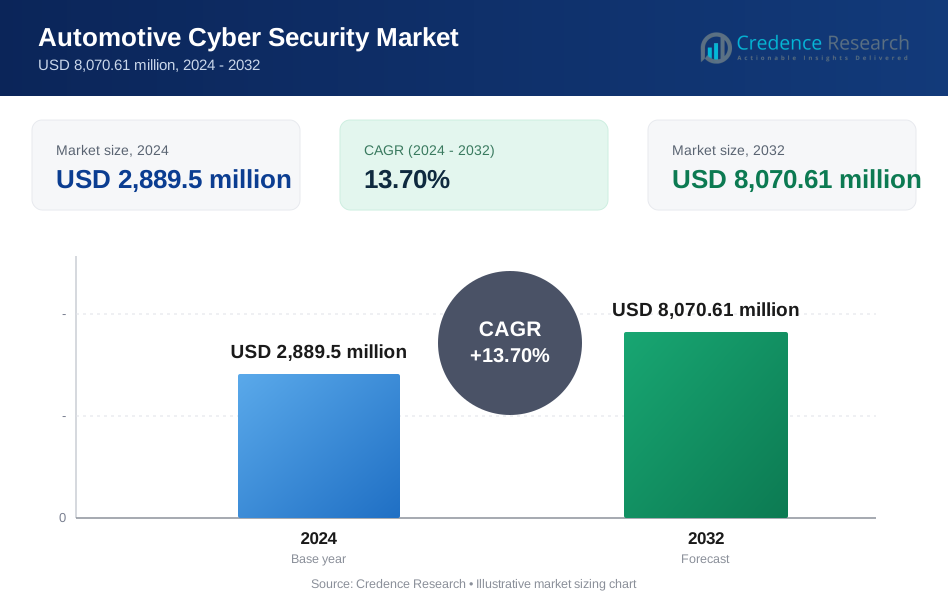
The Automotive Cybersecurity Market is projected to grow from USD 2,889.5 million in 2024 to USD 8,070.61 million by 2032, achieving a compound annual growth rate (CAGR) of 13.70%.
The automotive cybersecurity market is primarily driven by the increasing connectivity of vehicles and the growing sophistication of cyber threats. As vehicles become more integrated with advanced technologies like IoT and AI, the demand for robust cybersecurity measures intensifies. Additionally, regulatory mandates for data protection and safety standards are pushing manufacturers to invest in comprehensive cybersecurity solutions. Trends such as the rise of electric and autonomous vehicles further underscore the need for enhanced security protocols. This landscape fosters innovation in cybersecurity technologies, ensuring the protection of sensitive vehicle data and safeguarding against potential cyberattacks.
The automotive cybersecurity market exhibits significant growth across various regions, with North America and Europe leading due to stringent regulations and a high concentration of key players. Notable companies such as DENSO Corporation, Karamba Security, Robert Bosch GmbH, Aptiv PLC, Harman International, and Continental AG are pivotal in shaping market dynamics. These firms are investing in advanced security solutions to address the increasing vulnerabilities associated with connected and autonomous vehicles. As the demand for secure automotive technologies rises, these key players are crucial in enhancing vehicle safety and protecting consumer data across global markets.
Market Drivers
Growing Adoption of Electric Vehicles
The shift towards electric vehicles (EVs) introduces new attack surfaces due to their distinct components and architectures compared to traditional vehicles. These variations create potential vulnerabilities that must be addressed to protect consumers and manufacturers alikeFor instance, the International Energy Agency (IEA) reported that nearly one in five cars sold in 2023 was electric. Additionally, battery management systems, which are critical for the operation of EVs, are potential targets for cyberattacks. Ensuring the security of these systems is vital to prevent safety hazards and maintain the integrity of electric vehicle technologies.
Government Regulations and Mandates
Governments worldwide are implementing stricter data privacy regulations, compelling automotive manufacturers to protect customer data effectively. For instance, the U.S. National Highway Traffic Safety Administration (NHTSA) has updated its cybersecurity best practices for the safety of modern vehicles. The development and enforcement of cybersecurity standards and guidelines are crucial for ensuring the safety and security of vehicles. Compliance with these regulations not only mitigates the risk of cyber threats but also fosters consumer confidence in the automotive industry. As a result, manufacturers must prioritize cybersecurity to align with regulatory requirements and enhance their market reputation.
Increased Connectivity
Modern vehicles are becoming increasingly connected to the internet, enabling remote updates, diagnostics, and enhanced entertainment features. However, this connectivity exposes them to potential cyber threats, necessitating robust cybersecurity measures. Technologies such as Vehicle-to-Infrastructure (V2I) and Vehicle-to-Vehicle (V2V) communication are essential for the development of autonomous driving. These systems create complex networks that can be vulnerable to cyberattacks, highlighting the need for comprehensive security protocols to safeguard connected cars from potential breaches.
Advancement in Autonomous Driving
Autonomous vehicles rely heavily on complex software systems, making them particularly susceptible to cyberattacks that could compromise safety and functionality. The integration of advanced sensors and control systems increases the potential attack surface, making these vehicles attractive targets for malicious actors. Furthermore, the vast amounts of data collected and processed by autonomous vehicles raise significant data privacy concerns. Protecting this sensitive information is crucial to maintaining consumer trust and ensuring the secure operation of self-driving technologies.
Market Trends
Increased Focus on Over-the-Air (OTA) Updates and Artificial Intelligence Integration
The automotive industry is witnessing an increased focus on Over-the-Air (OTA) updates as a crucial mechanism for enhancing vehicle functionality and security. For instance, a survey conducted by the National Highway Traffic Safety Administration (NHTSA) highlights that OTA updates are now quite common in the automotive market, with major vehicle manufacturers routinely rolling out updates for infotainment and navigation systems. While OTA updates provide convenience and the ability to address security vulnerabilities remotely, they also introduce new attack surfaces that cybercriminals can exploit. To mitigate these risks, manufacturers are investing in secure update mechanisms that ensure the integrity and authenticity of the updates being deployed. Simultaneously, the integration of Artificial Intelligence (AI) and Machine Learning (ML) technologies is becoming paramount in the fight against cyber threats. These advanced technologies enable real-time threat detection and response, significantly enhancing the cybersecurity posture of connected vehicles. By employing AI and ML for anomaly detection, manufacturers can identify unusual behavior patterns that may indicate potential cyberattacks, thereby enabling a proactive approach to vehicle security.
Growing Importance of Cybersecurity Insurance and Expanding Global Regulatory Landscape
As the cyber threat landscape evolves, the growing importance of cybersecurity insurance has emerged as a significant trend within the automotive sector. Cybersecurity insurance provides manufacturers with risk mitigation strategies and helps offset the financial costs associated with cyberattacks. Furthermore, some jurisdictions are mandating cybersecurity insurance as a requirement for automotive manufacturers, reinforcing the need for robust security measures. Alongside this, the expanding global regulatory landscape is shaping the future of automotive cybersecurity. Countries are adopting international standards, such as ISO 26262 and UNECE WP.29, to ensure vehicle cybersecurity and safety. Regional regulations, including the EU's General Data Protection Regulation (GDPR), also impose strict guidelines that automotive manufacturers must adhere to in their cybersecurity practices. By complying with these regulations, manufacturers not only enhance their security measures but also foster consumer confidence in their commitment to protecting sensitive data and maintaining the integrity of their vehicles. This combination of increased focus on cybersecurity insurance and adherence to global regulations highlights the industry's dedication to strengthening its defenses against evolving cyber threats.
Market Challenges Analysis
Complexity of Automotive Systems and Rapid Technological Advancements
One of the primary challenges in automotive cybersecurity lies in the complexity of modern vehicle systems. Today’s vehicles are composed of numerous interconnected components, each with its own set of vulnerabilities that can be exploited by cybercriminals. For instance, a report by McKinsey highlights that modern cars have up to 150 electronic control units (ECUs) and about 100 million lines of code, which is projected to rise to 300 million lines of code by 2030. This diversity complicates the task of safeguarding the entire vehicle ecosystem. Furthermore, many older vehicles still rely on legacy systems, which often feature outdated security measures that leave them particularly susceptible to attacks. As technology advances rapidly, the automotive industry also faces the challenge of new attack surfaces created by emerging technologies, such as autonomous driving and connected vehicles. These advancements necessitate that cybersecurity solutions not only keep pace with technological developments but also evolve continually to counteract a range of new threats and vulnerabilities that emerge alongside them.
Supply Chain Vulnerabilities and Regulatory Fragmentation
Another significant challenge arises from supply chain vulnerabilities inherent in the automotive sector. Many critical components are sourced from third-party suppliers, which can increase the risk of compromised hardware or software infiltrating the vehicle's systems. Ensuring the security of the entire supply chain presents a complex challenge for manufacturers, who must implement secure supply chain management practices to mitigate risks. This complexity is further compounded by regulatory fragmentation, where global efforts to harmonize cybersecurity standards encounter regional variations that can hinder manufacturers' compliance efforts. Navigating these diverse regulatory landscapes is both time-consuming and costly, creating additional hurdles for automotive companies striving to meet multiple compliance requirements. Furthermore, the industry is grappling with a shortage of specialized talent in automotive cybersecurity. Finding skilled professionals who possess the necessary expertise to address these multifaceted challenges is increasingly difficult. Consequently, manufacturers must invest in training and development programs to cultivate the talent pool required to navigate the evolving cybersecurity landscape effectively. Overall, these challenges underscore the pressing need for the automotive sector to adopt comprehensive and adaptive cybersecurity strategies to safeguard their products and consumers against emerging threats.
Market Segmentation Analysis:
By Offering:
The automotive cybersecurity market is broadly segmented based on offerings and applications, with each segment reflecting unique demands and growth potential. The offerings are categorized into software and hardware. Software solutions encompass a range of cybersecurity applications, including threat detection, secure communication protocols, and over-the-air (OTA) updates, which are essential for safeguarding vehicle systems. On the other hand, hardware solutions focus on physical security components, such as secure chips and firewalls, to protect critical automotive systems from cyber threats. The increasing complexity of connected and autonomous vehicles amplifies the demand for both software and hardware solutions, as manufacturers strive to protect their vehicles from sophisticated cyberattacks.
By Application:
In terms of application, the market is segmented into several key areas, including Advanced Driver Assistance Systems (ADAS) and safety, body control and comfort, infotainment, telematics, powertrain systems, and communication systems. Each of these applications requires specialized cybersecurity measures to address specific vulnerabilities. For instance, ADAS and safety systems demand robust security protocols to ensure passenger safety, while infotainment and telematics systems prioritize secure data transmission. The growing emphasis on connected vehicles and autonomous driving is driving investment in cybersecurity solutions across all application segments, highlighting the critical need for comprehensive protection measures in the automotive industry.
Segments:
Based on Offering:
- Software
- Hardware
Based on Application:
- ADAS & safety
- Body control & comfort
- Infotainment
- Telematics
- Powertrain systems
- Communication systems
Based on Form Type
- In-vehicle
- External cloud services
Based on Security Type
- Application
- Wireless
- Endpoint
Based on Approach
- Intrusion Detection System
- Security Operations Centre
Based on Vehicle Type
- Passenger Vehicles
- Light Commercial Vehicles
- Heavy Commercial Vehicles
Based on Propulsion Type
- ICE Vehicles
- Electric Vehicles
Based on Vehicle Autonomy
- Non-autonomous Vehicles
- Semi-autonomous Vehicles
- Autonomous Vehicles
Based on EV Application
- ADAS & safety
- Body control & comfort
- Infotainment
- Telematics
- BMS & powertrain systems
- Communication systems
- Charging management
Based on the Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American automotive cybersecurity market holds a significant share, estimated at approximately 35% of the global market. This dominance can be attributed to the rapid adoption of connected vehicles, stringent regulatory frameworks, and heightened awareness of cybersecurity threats among consumers and manufacturers. Major automotive players in the region are investing heavily in advanced cybersecurity technologies to safeguard their vehicles against potential cyberattacks. For instance, in January 2023, Valeo and C2A Security collaborated to improve software-defined vehicle cybersecurity. Through this partnership, Valeo is able to improve the cybersecurity management of its products, give its clients more assurance, and transform cybersecurity into a true business enabler. The presence of leading automotive manufacturers, technology firms, and a robust research and development ecosystem further propels the growth of the automotive cybersecurity sector in North America. Additionally, the implementation of government regulations aimed at ensuring data privacy and vehicle safety drives demand for effective cybersecurity solutions across the region.
Asia-Pacific
In contrast, the Asia-Pacific region is emerging as a formidable player in the automotive cybersecurity market, accounting for approximately 30% of the global share. The rapid growth of the automotive industry in countries like China, Japan, and South Korea, coupled with the increasing adoption of electric vehicles (EVs) and advanced driver assistance systems (ADAS), is fueling the demand for cybersecurity solutions. As manufacturers focus on enhancing vehicle connectivity and automating processes, the need for robust cybersecurity measures has become paramount to protect vehicles from cyber threats. Furthermore, the region's commitment to aligning with international cybersecurity standards and regulations ensures that automotive manufacturers prioritize cybersecurity in their product development strategies, creating significant growth opportunities in the Asia-Pacific automotive cybersecurity market.
Key Player Analysis
- DENSO Corporation (Japan)
- Karamba Security (Israel)
- Robert Bosch GmbH (Germany)
- Aptiv PLC (Ireland)
- Harman International (US)
- Continental AG (Germany)
Competitive Analysis
The competitive landscape of the automotive cybersecurity market is characterized by the presence of several key players, including DENSO Corporation, Karamba Security, Robert Bosch GmbH, Aptiv PLC, Harman International, and Continental AG. These companies are heavily investing in research and development to innovate robust security solutions tailored for connected and autonomous vehicles. Key strategies include significant investments in research and development to create robust frameworks that protect critical vehicle systems, such as powertrain, infotainment, and telematics. Firms are also emphasizing the integration of artificial intelligence and machine learning to enhance threat detection and response capabilities. Additionally, partnerships and alliances are becoming increasingly common, as companies seek to combine expertise and resources to develop comprehensive cybersecurity solutions. As the market continues to evolve, organizations must stay agile and proactive in addressing emerging threats to maintain a competitive edge.
Recent Developments
- In February 2023, ETAS (a subsidiary of Robert Bosch GmbH) offered ESCRYPT C_ycurRISK, a software tool for threat analysis and risk assessment. It allows the automotive OEMs and suppliers to identify security vulnerabilities during vehicle development and reduce cyber risks systematically.
- In January 2023, HL Mando Corporation collaborated with Argus Cyber Security. Through this collaboration, the Argus CAN Intrusion Detection Systems (IDS) solution was applied to HL Mando’s electrification system products, such as brakes and steering, beginning in January 2023.
- In October 2022, NTT Communications Corporation, along with DENSO Corporation (DENSO), was supposed to develop the security operation center technology for vehicles (VSOC1) to respond to the threat of increasingly sophisticated cyber-attacks against vehicles.
- In November 2022, Garrett Motion Inc. developed multi-layered on-and-off board intrusion detection systems (IDS) to identify cyber threats, which support OEMs to enhance vehicle security.
Market Concentration & Characteristics
The automotive cybersecurity market exhibits moderate concentration, characterized by a mix of established players and emerging startups. Leading companies dominate through significant investments in research and development, enabling them to offer comprehensive cybersecurity solutions tailored to the evolving needs of connected and autonomous vehicles. These firms often leverage advanced technologies, such as artificial intelligence and machine learning, to enhance threat detection and mitigation strategies. Additionally, the market is witnessing an increase in collaborations and partnerships, allowing companies to pool resources and expertise to develop innovative security frameworks. Despite the presence of dominant players, the emergence of niche startups is fostering competition by introducing specialized solutions that address specific vulnerabilities in automotive systems. This dynamic landscape drives continuous improvement and adaptation, ensuring that the industry can effectively respond to the ever-evolving threat landscape while meeting regulatory requirements and consumer demands for safer vehicles.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Offering, Application, Form Type, Security Type, Approach, Vehicle Type, Propulsion Type, Vehicle Autonomy, EV Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for robust automotive cybersecurity solutions will continue to grow as vehicles become increasingly connected and autonomous.
- Integration of artificial intelligence and machine learning technologies will enhance real-time threat detection and response capabilities.
- Regulatory bodies will implement stricter cybersecurity standards, compelling manufacturers to adopt comprehensive security measures.
- The rise of electric vehicles will introduce new security challenges, necessitating specialized cybersecurity frameworks.
- Collaboration among industry players will increase to share threat intelligence and best practices for enhancing overall cybersecurity.
- Investment in cybersecurity insurance will become more prevalent as manufacturers seek to mitigate financial risks associated with cyberattacks.
- Over-the-air (OTA) updates will become a standard practice, requiring secure mechanisms to prevent vulnerabilities during the update process.
- Consumer awareness regarding automotive cybersecurity risks will drive demand for safer vehicles and influence purchasing decisions.
- The expansion of cybersecurity-as-a-service (CaaS) will provide scalable solutions for manufacturers, particularly smaller companies with limited resources.
- Continuous monitoring and proactive defense strategies will be essential to keep pace with the evolving threat landscape in the automotive sector.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Adoption of Electric Vehicles
The increasing shift towards electric vehicles introduces new digital architectures and components, creating additional attack surfaces that require specialized cybersecurity solutions. As EV sales rise globally, manufacturers are compelled to invest in advanced security frameworks to protect critical systems such as battery management and charging infrastructure.
Government Regulations and Mandates
Stricter data privacy and vehicle safety regulations worldwide are compelling automotive manufacturers to implement robust cybersecurity measures. Compliance with standards such as UNECE WP.29 and regional mandates like the EU's GDPR is driving the adoption of comprehensive security protocols across the industry.
Increased Connectivity and V2X Communication
Modern vehicles are increasingly connected to external networks and infrastructure, enabling features like remote diagnostics and vehicle-to-everything (V2X) communication. This connectivity exposes vehicles to potential cyber threats, necessitating advanced cybersecurity solutions to safeguard data and ensure operational safety.
Advancement in Autonomous Driving
The proliferation of autonomous and semi-autonomous vehicles, which rely on complex software and sensor systems, significantly increases the potential for cyberattacks. Protecting these vehicles from malicious interference is critical to ensuring passenger safety and maintaining consumer trust.
Rising Importance of Over-the-Air (OTA) Updates
The automotive industry's adoption of OTA updates for software and firmware improvements introduces new vulnerabilities that cybercriminals can exploit. Secure OTA mechanisms are essential to prevent unauthorized access and maintain the integrity of vehicle systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Cyber Security market?
What factors are driving the growth of the Automotive Cyber Security market?
What are the key segments within the Automotive Cyber Security market?
What are some challenges faced by the Automotive Cyber Security market?
Who are the major players in the Automotive Cyber Security market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offering
- 1.2.1 Software
- 1.2.2 Hardware
- 1.3 By Application
- 1.3.1 ADAS & safety
- 1.3.2 Infotainment
- 1.3.3 Telematics
- 1.3.4 Powertrain systems
- 1.3.5 Communication systems
- 1.3.6 Body control & comfort
- 1.4 By Vehicle Type
- 1.4.1 Passenger Vehicles
- 1.4.2 Light Commercial Vehicles
- 1.4.3 Heavy Commercial Vehicles
- 1.5 By Security Type
- 1.5.1 Application
- 1.5.2 Wireless
- 1.5.3 Endpoint
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,889.5 million → 2032: USD 8,070.61 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Cyber Security Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Cyber Security Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Cyber Security Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Cyber Security Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Cyber Security Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Cyber Security Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Cyber Security Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Cyber Security Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,889.5 million → 2032: USD 8,070.61 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Cyber Security Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offering - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Software
- 12.3.6.2 Hardware
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 ADAS & safety
- 12.4.6.2 Infotainment
- 12.4.6.3 Telematics
- 12.4.6.4 Powertrain systems
- 12.4.6.5 Communication systems
- 12.4.6.6 Body control & comfort
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Passenger Vehicles
- 12.5.6.2 Light Commercial Vehicles
- 12.5.6.3 Heavy Commercial Vehicles
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Security Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Application
- 12.6.6.2 Wireless
- 12.6.6.3 Endpoint
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Cyber Security End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Cyber Security Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Cyber Security Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Cyber Security Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DENSO Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Karamba Security
- 18.4 Robert Bosch GmbH
- 18.5 Aptiv PLC
- 18.6 Harman International
- 18.7 Continental AG
- 18.8 Garrett Motion Inc.
- 18.9 Argus Cyber Security
- 18.10 ETAS (Bosch subsidiary)
- 18.11 NTT Communications Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

