
Market Overview
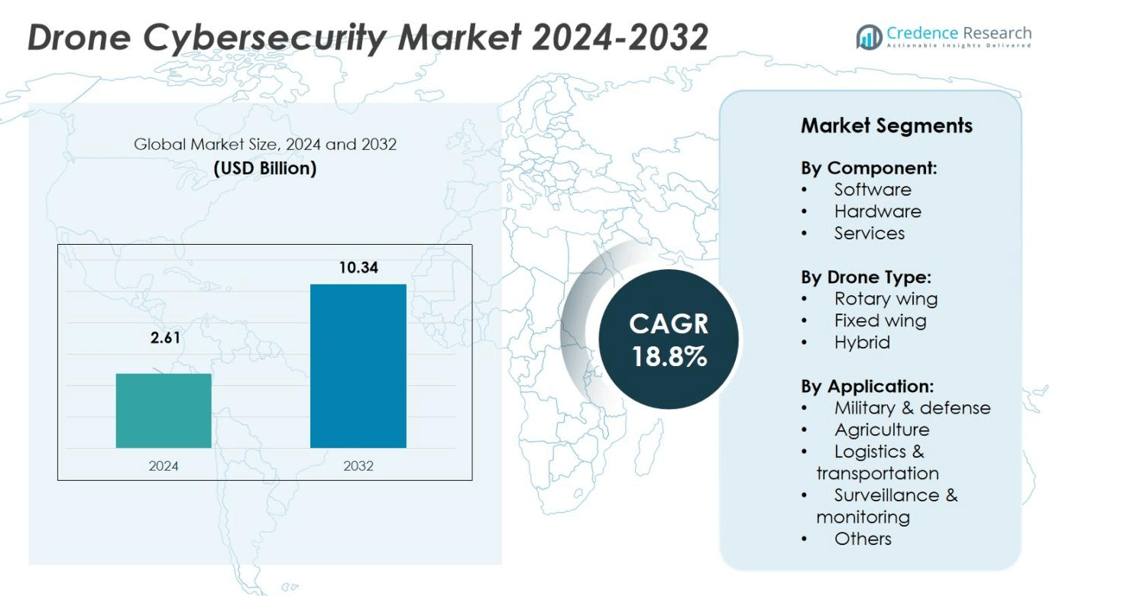
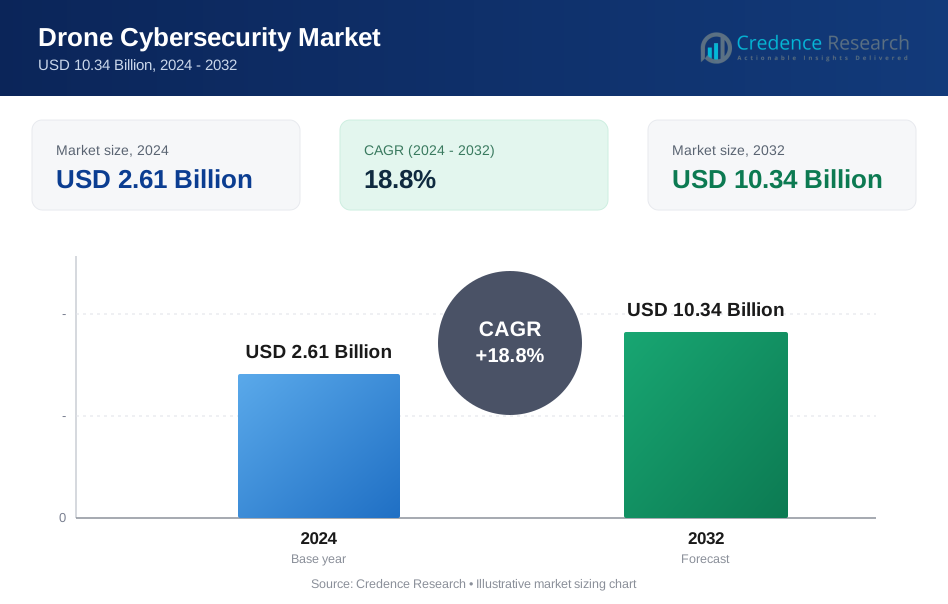
Drone Cybersecurity Market size was valued USD 2.61 Billion in 2024 and is anticipated to reach USD 10.34 Billion by 2032, at a CAGR of 18.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Drone Cybersecurity Market Size 2024 | USD 2.61 Billion |
| Drone Cybersecurity Market, CAGR | 18.8% |
| Drone Cybersecurity Market Size 2032 | USD 10.34 Billion |
The Drone Cybersecurity Market is characterized by strong competition among major players such as 3M, Toray Industries, Hexcel Corporation, DuPont, SABIC, BASF, ArcelorMittal, Victrex, Alcoa Corporation, and Honeywell International. These companies focus on developing integrated cybersecurity solutions that enhance drone communication security, encryption, and real-time threat detection. Strategic alliances with defense and aerospace agencies drive advancements in AI-based intrusion prevention and blockchain-enabled data protection. North America leads the global market with a 36% share in 2024, supported by robust defense investments, advanced technological infrastructure, and stringent regulatory frameworks that promote secure drone operations across both commercial and military applications.
Market Insights
- The Drone Cybersecurity Market was valued at USD 2.61 Billion in 2024 and is projected to reach USD 10.34 Billion by 2032, growing at a CAGR of 18.8%.
- Rising drone adoption in defense, logistics, and surveillance applications drives demand for advanced cybersecurity solutions to secure communication and data systems.
- The market trends highlight increasing integration of AI, blockchain, and quantum encryption for real-time threat detection and secure drone operations.
- Key players such as 3M, Toray Industries, DuPont, SABIC, and Honeywell International focus on R&D, partnerships, and regulatory compliance to expand market presence.
- North America leads with a 36% share, followed by Europe with 28% and Asia-Pacific with 25%, while the software segment dominates the market with 52% share in 2024 due to growing demand for encryption and real-time monitoring solutions.
Market Segmentation Analysis:
By Component
Software dominates the drone cybersecurity market with a 52% share in 2024, driven by the need for real-time threat detection, encryption, and secure communication protocols. Software solutions enable autonomous drones to identify, analyze, and mitigate cyberattacks instantly through AI-driven analytics and machine learning algorithms. For instance, companies integrate advanced firmware protection and network firewalls to prevent GPS spoofing and data breaches. The rising demand for cloud-based monitoring and cybersecurity-as-a-service platforms further boosts adoption across both commercial and defense drone operations.
- For instance, Fortress Information Security provides a platform for managing the cybersecurity of assets and software within critical infrastructure supply chains, including uncrewed aerial systems (UAS or drones), to help organizations meet defense-grade operational and regulatory standards.
By Drone Type
Rotary-wing drones hold the leading 58% market share in 2024, supported by their widespread use in surveillance, logistics, and agricultural monitoring. Their continuous flight capability and vertical takeoff features make them more prone to cybersecurity vulnerabilities, creating strong demand for secure control systems and encrypted communication links. Manufacturers deploy AI-enabled intrusion prevention and endpoint security systems for rotary models to safeguard flight control data. The expanding use of rotary-wing drones in defense and urban delivery operations accelerates cybersecurity investments in this sub-segment.
- For instance, DJI's Matrice 300 RTK employs AES-256 encryption and Trusted Execution Environment (TEE) technology to secure flight data and user information. The drone platform supports offline updates and local data mode to enhance operational security, with over 15,000 units deployed worldwide for public safety and industrial monitoring applications.
By Application
Military and defense applications dominate with a 47% share in 2024, due to the critical need to protect mission-sensitive data and ensure operational integrity. Armed forces increasingly rely on encrypted communication systems, secure command-and-control (C2) links, and blockchain-based authentication to prevent signal jamming and data interception. Cyber threats such as spoofing and malware infiltration have prompted defense agencies to adopt layered cybersecurity solutions. Growing use of unmanned aerial vehicles (UAVs) in reconnaissance, border surveillance, and combat missions continues to strengthen cybersecurity integration across this segment.
Key Growth Drivers
Rising Drone Adoption Across Commercial and Defense Sectors
The increasing use of drones across logistics, agriculture, surveillance, and defense sectors is driving demand for robust cybersecurity systems. Military drones require secure communication and navigation to prevent data interception and mission compromise. Similarly, commercial drones used for mapping, delivery, and inspection need encrypted networks for data transfer. The growing reliance on drones for real-time intelligence and delivery operations encourages manufacturers to integrate end-to-end encryption and secure command links, making cybersecurity a key differentiator in system reliability.
- For instance,Pantherun integrates AES encryption directly into drone controllers, enabling encryption and decryption cycles within 5 milliseconds, thus preventing real-time command hijacking in industrial drones.
Increasing Incidents of Drone-Related Cyber Threats
Cyberattacks on drones have become more frequent, targeting GPS signals, flight data, and communication systems. Hackers exploit unprotected links to hijack drones or disrupt their missions. In response, companies are developing stronger firmware, intrusion detection systems, and encrypted protocols. The growing awareness among drone operators about security vulnerabilities also contributes to higher adoption of cybersecurity measures. This rise in threat intensity drives innovation and deployment of advanced defense technologies for unmanned systems globally.
- For instance, Fortem Technologies deploys radar-based drone detection systems capable of scanning airspace continuously with coverage of up to 15 kilometers, enabling the interception of unauthorized drones before they can breach secure zones
Technological Advancements in Encryption and AI-Based Security
Artificial intelligence and advanced encryption technologies are transforming drone cybersecurity. AI-driven systems detect anomalies and respond to threats in real time, while machine learning enhances predictive threat analysis. Blockchain solutions provide tamper-proof transaction records between drones and control stations, ensuring transparency. Manufacturers are also adopting quantum-resistant cryptography to future-proof data security. These technological improvements enhance system resilience and promote the development of intelligent, adaptive cybersecurity frameworks for both defense and commercial drone applications.
Key Trends & Opportunities
Integration of Blockchain and Decentralized Security Networks
Blockchain technology is emerging as a key enabler of secure drone operations. It ensures transparent communication and immutable recordkeeping across drone networks. Decentralized identity verification minimizes unauthorized access while maintaining traceable mission data. Smart contracts within blockchain systems automate authentication, mission validation, and control protocols. This innovation supports secure swarm operations and fosters trust in large-scale drone deployments for surveillance, logistics, and emergency response missions.
- For instance, the DroneCrypt IFF system uses Hyperledger Fabric to manage drone identities with a blockchain capacity of processing up to 20,000 transactions per second, ensuring tamper-proof identity verification for secure urban air mobility deployments.
Expansion of Cybersecurity-as-a-Service (CaaS) Models
Cybersecurity-as-a-Service models are gaining traction as drone operators seek flexible and cost-effective protection. These cloud-based solutions provide continuous monitoring, risk detection, and automated updates for large drone fleets. CaaS platforms reduce infrastructure costs and allow remote management of cybersecurity layers. Drone manufacturers and service providers increasingly collaborate to deliver scalable subscription-based protection, creating new opportunities for recurring revenue and stronger fleet-level security across industrial and government sectors.
- For instance, DroneShield has deployed over 4,000 counter-drone devices globally, with more than 1,500 of these devices connected to its cloud-based software platform, enabling real-time threat detection and response for large drone fleets
Key Challenges
High Implementation Costs and Integration Complexity
The integration of advanced cybersecurity tools within drone systems increases both production and operational costs. Small and medium drone manufacturers often face financial barriers when adopting AI-driven or blockchain-based systems. Compatibility between hardware, communication protocols, and cloud infrastructure adds complexity to deployment. The requirement for specialized expertise in cybersecurity also limits adoption among smaller operators, slowing market expansion despite the growing threat landscape.
Lack of Standardized Regulations and Compliance Frameworks
The absence of uniform cybersecurity standards across nations creates uncertainty for drone manufacturers and operators. Regulatory inconsistencies make it difficult to design universal protection systems that meet diverse security requirements. This challenge affects international drone operations, especially in defense and commercial logistics sectors. Efforts by aviation and defense authorities to establish global cybersecurity guidelines are ongoing but fragmented, delaying cross-border deployment of secure and compliant drone systems.
Regional Analysis
North America
North America dominates the drone cybersecurity market with a 36% share in 2024, driven by strong defense investments and commercial drone adoption. The United States leads regional growth, supported by high defense spending, cybersecurity infrastructure, and the presence of key players developing AI-powered security systems. The Federal Aviation Administration (FAA) regulations also encourage compliance with cybersecurity protocols. Growing use of drones for surveillance, logistics, and law enforcement further increases demand for advanced threat detection and encryption technologies across the U.S. and Canada.
Europe
Europe holds a 28% market share in 2024, fueled by rising adoption of unmanned aerial systems for logistics, border security, and environmental monitoring. Countries such as Germany, France, and the U.K. lead the regional growth, emphasizing compliance with strict EU cybersecurity regulations. Collaborative defense initiatives like the European Defence Fund support research into secure drone communication systems. The expansion of commercial drone fleets and the need for standardized cybersecurity frameworks drive innovation across both public and private sectors.
Asia-Pacific
Asia-Pacific accounts for a 25% share in 2024, driven by growing drone deployment in agriculture, logistics, and defense sectors. China, Japan, and India are major contributors, investing heavily in UAV manufacturing and secure navigation systems. Increasing government support for smart city and surveillance projects accelerates adoption of secure drone communication networks. Regional startups are focusing on AI-driven cybersecurity software for drone data protection. The expanding e-commerce and logistics industries also push demand for secure and compliant drone operations.
Latin America
Latin America represents a 7% market share in 2024, with growing opportunities in infrastructure inspection, mining surveillance, and agriculture. Brazil and Mexico lead regional adoption, supported by government programs encouraging safe and regulated drone operations. Rising concerns about data security in cross-border drone operations promote demand for secure communication protocols. However, limited awareness of advanced cybersecurity solutions among local operators constrains rapid market growth. Partnerships between global cybersecurity firms and regional drone service providers are expected to strengthen market development.
Middle East & Africa
The Middle East & Africa region captures a 4% share in 2024, supported by rising drone usage in defense, oil and gas monitoring, and infrastructure projects. Countries like the UAE, Saudi Arabia, and South Africa are investing in drone surveillance systems with embedded cybersecurity measures. Government-driven smart infrastructure projects and increasing security concerns along borders accelerate demand for encrypted data communication. Although the market is in its early stages, strategic partnerships and regulatory initiatives are fostering growth and digital resilience in drone operations.
Market Segmentations:
By Component:
- Software
- Hardware
- Services
By Drone Type:
- Rotary wing
- Fixed wing
- Hybrid
By Application:
- Military & defense
- Agriculture
- Logistics & transportation
- Surveillance & monitoring
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Drone Cybersecurity Market is defined by the presence of key players such as 3M, Toray Industries, Hexcel Corporation, DuPont, SABIC, BASF, ArcelorMittal, Victrex, Alcoa Corporation, and Honeywell International. These companies focus on developing integrated hardware and software solutions that enhance drone communication security, data encryption, and real-time threat monitoring. Strategic collaborations with defense agencies and drone manufacturers drive innovation in anti-hacking technologies and AI-enabled threat detection systems. Market leaders emphasize the use of blockchain, quantum encryption, and intrusion prevention to strengthen drone data integrity. Continuous investments in R&D, regulatory compliance, and cloud-based security platforms enable these players to expand global presence. The competition remains intense, with firms pursuing mergers, product diversification, and partnerships to capture opportunities in commercial, military, and industrial drone applications worldwide.
Key Player Analysis
- Toray Industries
- ArcelorMittal
- BASF
- Alcoa Corporation
- Honeywell International
- Victrex
- 3M
- DuPont
- SABIC
- Hexcel Corporation
Recent Developments
- In May 2024, Axon announced the acquisition of Dedrone, aiming to enhance public safety and accelerate the development of advanced drone security solutions.
- In Jul 2024, Thales and Garuda Aerospace have signed an MoU to promote secure drone operations and innovation in India, focusing on UTM solutions, UAV detection, and system integration.
- In October 2025, Mobilicom Limited launched Secured Autonomy™, recognized as the industry’s first full-scale cybersecurity framework designed for autonomous drones and robotics, offering advanced protection across communication and control systems.
- In August 2025, DroneShield Ltd. deployed its next-generation counter-UAS technology during the multinational defense exercise “Project FlyTrap,” showcasing enhanced cyber-electromagnetic security capabilities for drone detection and neutralization.
Report Coverage
The research report offers an in-depth analysis based on Component, Drone Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for AI-driven drone cybersecurity systems will continue to rise across industries.
- Governments will implement stricter cybersecurity regulations for drone operations and data protection.
- Defense and surveillance applications will remain the largest consumers of advanced drone security solutions.
- Blockchain integration will enhance transparency and authentication in drone communication networks.
- Cloud-based cybersecurity platforms will gain traction for fleet-level monitoring and threat response.
- The expansion of commercial drone delivery and logistics will increase the need for real-time data protection.
- Partnerships between cybersecurity firms and drone manufacturers will strengthen solution portfolios.
- Quantum encryption and zero-trust frameworks will emerge as key technologies in drone security.
- Asia-Pacific will witness rapid adoption due to growing smart city and defense initiatives.
- Continuous innovation and compliance with global standards will define long-term market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Drone Cybersecurity Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Drone Cybersecurity Market projected to grow between 2025 and 2032?
Which Drone Cybersecurity Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Drone Cybersecurity Market?
Who are the leading companies in the Drone Cybersecurity Market?
Which region commanded the largest share of the Drone Cybersecurity Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.61 Billion → 2032: USD 10.34 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drone Cybersecurity Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drone Cybersecurity Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Drone Cybersecurity Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Drone Cybersecurity Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drone Cybersecurity Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drone Cybersecurity Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drone Cybersecurity Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drone Cybersecurity Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.61 Billion → 2032: USD 10.34 Billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drone Cybersecurity Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drone Cybersecurity Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Drone Cybersecurity Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Drone Cybersecurity Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

