
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Idler Arm Market Size 2024 | USD 3,471.85 million |
| Automotive Idler Arm Market , CAGR | 2.90% |
| Automotive Idler Arm Market Size 2032 | USD 4,363.98 million |
Market Overview:
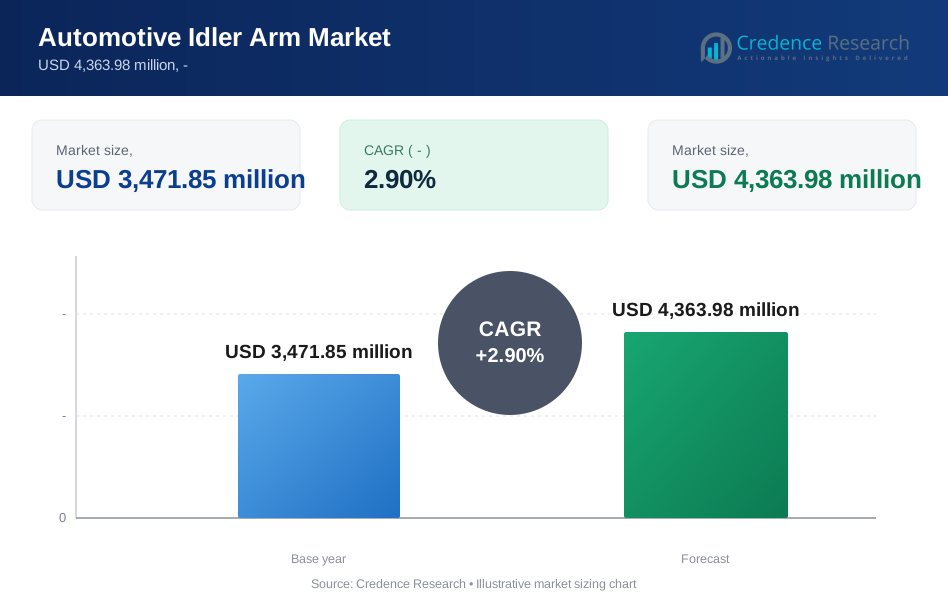
The global automotive idler arm market is projected to grow steadily, with the market size expected to increase from USD 3,471.85 million in 2024 to USD 4,363.98 million by 2032, reflecting a compound annual growth rate (CAGR) of 2.90% over the forecast period. The idler arm is a critical component in the steering system of vehicles, particularly in heavy-duty trucks and SUVs, where it helps to support the steering linkage and maintain proper alignment. The market’s growth is driven by the rising demand for commercial vehicles and the increasing focus on vehicle safety and performance. As more consumers and industries opt for vehicles that offer superior handling and stability, the need for reliable and durable idler arms continues to rise, fuelling market expansion.
Several factors are driving the growth of the automotive idler arm market. The increasing production and sales of commercial vehicles, particularly in emerging economies, is a major driver. As industries such as logistics and construction expand, the demand for heavy-duty vehicles, which heavily rely on robust steering components like idler arms, is growing. Additionally, advancements in automotive technology, including the development of more sophisticated steering systems, are boosting the demand for high-quality idler arms that can enhance vehicle handling and safety. The growing focus on aftermarket services, where replacement of worn-out idler arms is a common requirement, also supports market growth.
North America is expected to dominate the automotive idler arm market, accounting for the largest market share during the forecast period. This dominance is attributed to the region’s strong automotive industry, particularly in the United States, where there is a high demand for trucks and SUVs that require durable steering components. Asia-Pacific is projected to be the fastest-growing region, driven by the rapid industrialization and urbanization in countries like China and India, leading to increased vehicle production and sales. Europe also represents a significant market, supported by the region’s emphasis on vehicle safety and the presence of major automotive manufacturers. The diverse growth patterns across these regions highlight the global importance of the automotive idler arm market.
Market Drivers:
Rising Demand for Commercial Vehicles:
The increasing demand for commercial vehicles, particularly in sectors such as logistics, construction, and agriculture, is a significant driver of the automotive idler arm market. Commercial vehicles, including trucks and SUVs, require robust steering systems to ensure reliability and safety during heavy-duty operations. For instance, in the United States, the trucking industry plays a crucial role in the economy, with a substantial portion of goods transportation relying on heavy-duty trucks. This demand for commercial vehicles directly correlates with the need for durable idler arms that can withstand the rigorous demands of these vehicles, driving market growth.
Focus on Vehicle Safety and Performance:
Enhanced vehicle safety and performance are paramount concerns for both manufacturers and consumers, contributing to the growth of the automotive idler arm market. As steering systems play a critical role in vehicle control and stability, high-quality idler arms are essential for ensuring precise steering and maintaining alignment. For example, automakers are continuously improving steering components to enhance vehicle handling, especially in off-road and heavy-duty vehicles, where reliable steering is crucial. The emphasis on safety features and performance enhancements drives the demand for advanced idler arms that meet these stringent requirements.
Advancements in Automotive Technology:
The automotive industry is witnessing rapid technological advancements, particularly in steering and suspension systems, which are key to the market's growth. Innovations in materials and manufacturing processes have led to the development of more durable and efficient idler arms, capable of enhancing vehicle performance under various conditions. For instance, manufacturers are increasingly using high-strength materials and precision engineering to produce idler arms that offer better corrosion resistance and longer service life. These technological advancements support the market's expansion by providing products that meet the evolving needs of modern vehicles.
Expansion of Aftermarket Services:
The expansion of the automotive aftermarket is another crucial driver of the idler arm market. As vehicles age, the demand for replacement parts, including idler arms, grows. The aftermarket provides a wide range of products that cater to the maintenance and repair needs of both commercial and passenger vehicles. For instance, many vehicle owners prefer to replace worn-out idler arms with high-quality aftermarket options to ensure continued vehicle safety and performance. This trend is particularly strong in regions with a large aging vehicle fleet, further fueling the growth of the automotive idler arm market.
Market Trends:
Shift Towards Lightweight Materials:
A significant trend in the automotive idler arm market is the shift towards the use of lightweight materials in manufacturing. As the automotive industry increasingly focuses on improving fuel efficiency and reducing vehicle emissions, the adoption of lighter yet durable materials in steering components, including idler arms, has gained momentum. For instance, manufacturers are now utilizing advanced composites and high-strength aluminum alloys to produce idler arms that offer comparable or superior strength to traditional steel components, while significantly reducing weight. This trend is aligned with broader industry efforts to enhance overall vehicle performance and meet stringent environmental regulations.
Integration of Advanced Manufacturing Technologies:
The integration of advanced manufacturing technologies, such as computer-aided design (CAD) and precision machining, is transforming the production of idler arms. These technologies allow manufacturers to produce more complex and precise idler arm designs that improve steering performance and durability. For example, CNC machining enables the production of idler arms with tighter tolerances and better surface finishes, leading to components that fit more accurately and perform more reliably in various driving conditions. This technological advancement ensures that modern idler arms can meet the rigorous demands of contemporary vehicles, particularly those used in off-road and heavy-duty applications.
Increased Focus on Durability and Longevity:
There is an increasing focus on enhancing the durability and longevity of automotive idler arms as vehicle owners and manufacturers prioritize long-term reliability. Idler arms are subjected to significant wear and tear, especially in commercial vehicles and SUVs, which are often used in challenging terrains. To address this, manufacturers are developing idler arms with improved corrosion resistance and stronger materials to withstand harsh conditions. For instance, the use of advanced coatings and treatments that prevent rust and degradation is becoming more common, ensuring that idler arms maintain their performance over extended periods.
Growing Aftermarket Demand:
The aftermarket segment for automotive idler arms is experiencing robust growth as vehicle owners seek high-quality replacement parts to maintain and enhance their vehicles' performance. This trend is particularly notable in regions with a large aging vehicle fleet, where maintaining older vehicles is essential. For example, many aftermarket suppliers are expanding their product lines to include idler arms that meet or exceed OEM specifications, providing consumers with reliable and cost-effective options for vehicle maintenance. This growing focus on the aftermarket highlights the ongoing demand for replacement idler arms as vehicles age and require regular maintenance.
Market Challenges Analysis:
High Production Costs:
One of the primary restraints in the automotive idler arm market is the high production costs associated with manufacturing durable and high-performance components. The use of advanced materials, such as high-strength alloys and composites, and the incorporation of precision engineering technologies drive up the cost of production. Manufacturers face the challenge of balancing the need for high-quality products with the pressure to keep prices competitive, particularly in price-sensitive markets. These high costs can limit the market penetration of premium idler arms, especially in regions where cost is a significant purchasing factor.
Technological and Design Complexity:
As vehicles become more advanced, the design and technology required for automotive components like idler arms become increasingly complex. The integration of these components into modern steering systems, particularly those in high-performance and off-road vehicles, demands significant investment in research and development (R&D). Smaller manufacturers may struggle to keep up with these technological demands, limiting their ability to compete with larger, well-established companies that have more extensive R&D resources. Additionally, the complexity of producing idler arms that meet the stringent requirements of modern vehicles can lead to longer development cycles and higher production costs.
Fluctuating Raw Material Prices:
The automotive idler arm market is also challenged by fluctuating raw material prices, particularly for metals and alloys used in manufacturing. The volatility in global commodity markets can lead to unpredictable cost structures, affecting the profitability of manufacturers. For instance, sudden increases in the price of steel or aluminum can significantly impact the cost of producing idler arms, forcing manufacturers to either absorb the additional costs or pass them on to consumers. This price volatility adds another layer of complexity to managing production and pricing strategies in the competitive automotive market.
Competition from Alternative Technologies:
The rise of alternative steering technologies, such as electronic power steering (EPS) systems that reduce the need for traditional mechanical components like idler arms, poses a potential challenge to the market. As automotive manufacturers increasingly adopt these technologies, particularly in electric and hybrid vehicles, the demand for traditional idler arms may decline. Manufacturers must adapt to this shift by exploring new opportunities or risk losing market share to emerging steering technologies.
Market Segmentation Analysis:
By Type:
The market is divided into several types, including alloy steel, iron, carbon steel, and others. Alloy steel holds the largest market segment due to its high strength and durability, making it a preferred choice for automotive idler arms. Iron and carbon steel are also widely used, offering cost-effective solutions for various vehicle types.
By Technology:
Technological segmentation includes precision engineering, advanced materials, and real-time communication systems. Precision engineering ensures accurate manufacturing of idler arms, enhancing their performance and longevity. Advanced materials, such as lightweight alloys and composites, are increasingly used to improve fuel efficiency and reduce emissions. Real-time communication systems, including vehicle-to-vehicle and vehicle-to-infrastructure technologies, facilitate autonomous driving and traffic flow optimization.
By End User:
The end-user segmentation comprises passenger cars, light commercial vehicles, and heavy commercial vehicles. Passenger cars form the largest segment, driven by the increasing demand for reliable and efficient steering systems. Light commercial vehicles also contribute significantly, particularly in the logistics and transportation sectors. Heavy commercial vehicles, including trucks and buses, rely on robust idler arm systems to ensure reliable performance in demanding conditions.
Segmentations:
By Material:
- Alloy Steel
- Iron
- Carbon Steel
- Others
By Sales Channel:
- OEM
- Aftermarket
By Vehicle Type:
- Passenger Cars
- Commercial Vehicles
By Region
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the market, accounting for approximately 35% of the global market. This dominance is driven by the strong presence of the automotive industry, particularly in the United States, where there is a high demand for heavy-duty vehicles like trucks and SUVs. These vehicles rely heavily on robust steering systems, including idler arms, to ensure durability and performance in challenging driving conditions. The region's well-established automotive aftermarket sector also contributes to the market, with a significant focus on replacement parts for aging vehicles.
Asia-Pacific
Asia-Pacific is the fastest-growing region, projected to account for around 30% of the global market share by 2032. This rapid growth is fuelled by the increasing vehicle production and sales in countries such as China, India, and Japan. China, in particular, is the largest automotive market globally, with a strong emphasis on both passenger and commercial vehicles. The ongoing industrialization and urbanization in Asia-Pacific are leading to a surge in demand for reliable and high-performance steering components, including idler arms. Additionally, the expanding automotive aftermarket in this region, driven by the rising number of vehicles on the road, supports the growing demand for idler arms as replacement parts.
Europe
Europe represents approximately 25% of the global market share, with countries like Germany, France, and the United Kingdom playing key roles. The region is known for its focus on automotive innovation, particularly in the production of high-performance and luxury vehicles, which require advanced steering systems. The stringent safety regulations in Europe also drive the demand for high-quality idler arms that enhance vehicle handling and stability. Furthermore, the presence of major automotive manufacturers and the region's commitment to sustainable vehicle technologies contribute to the steady growth of the idler arm market in Europe.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa together account for the remaining 10% of the market share, with Latin America leading at around 7%. In Latin America, Brazil and Mexico are the primary contributors, driven by the growing automotive sector and increasing demand for both commercial and passenger vehicles. In the Middle East & Africa, the market is gradually expanding, supported by rising investments in infrastructure and the growing adoption of vehicles equipped with modern steering systems.
Key Player Analysis:
Top Key Players
- Denso Corporation
- Continental AG
- Lear Corporation
- Tenneco Inc.
- BorgWarner Inc.
- Federal-Mogul Motorparts LLC
- Dorman Products Inc.
- GMB Corporation Japan
- ACDelco
- Sankei Industries Co. Ltd.
Competitive Analysis:
The automotive idler arm market is moderately competitive, with a mix of global and regional players vying for market share. Key players such as Moog (Federal-Mogul), TRW Automotive (ZF Friedrichshafen AG), ACDelco (General Motors), and Delphi Technologies dominate the market with their extensive product offerings and strong brand presence. These companies leverage advanced manufacturing technologies and robust distribution networks to maintain their competitive edge. They focus on producing high-quality, durable idler arms that meet the stringent requirements of both OEMs and the aftermarket. The competition is also characterized by strategic partnerships, product innovations, and a focus on expanding into emerging markets where vehicle production is rapidly increasing. Additionally, the presence of numerous smaller, regional players adds to the competitive dynamics, particularly in price-sensitive markets. As the market continues to evolve, companies are expected to invest in research and development to introduce more advanced and cost-effective solutions.
Recent Developments:
- Moog (Federal-Mogul) introduced an upgraded line of idler arms in 2023, designed with enhanced durability for off-road and heavy-duty applications. These new idler arms feature advanced corrosion-resistant coatings and improved sealing technologies, which significantly extend the lifespan of the components in harsh environments. This launch aligns with Moog's strategy to cater to the growing demand for high-performance steering components in the commercial vehicle segment.
- TRW Automotive (ZF Friedrichshafen AG), in 2022, expanded its range of idler arms by incorporating advanced materials that reduce weight without compromising strength. The new idler arms are designed to improve fuel efficiency by reducing the overall weight of the vehicle, which is particularly important in meeting stricter emission regulations. This development highlights TRW's commitment to innovation in steering and suspension systems.
- ACDelco (General Motors) announced in 2024 the release of a new series of idler arms specifically designed for electric vehicles (EVs). These idler arms are engineered to handle the unique demands of EV drivetrains, offering enhanced precision and durability. This product line expansion reflects ACDelco's focus on supporting the shift towards electrification in the automotive industry.
Market Concentration & Characteristics:
The automotive idler arm market is moderately concentrated, with a few key players dominating the industry due to their extensive product portfolios, technological expertise, and global reach. Major companies like Moog (Federal-Mogul), TRW Automotive (ZF Friedrichshafen AG), ACDelco (General Motors), and Delphi Technologies lead the market, offering high-quality, durable idler arms designed for both OEM and aftermarket applications. These market leaders focus on continuous innovation, integrating advanced materials and technologies to improve product performance and meet the evolving demands of the automotive industry. Additionally, they benefit from strong brand recognition and established distribution networks that allow them to maintain a competitive edge. However, the market also features a significant number of regional players, particularly in emerging markets, where price sensitivity and local preferences play a more prominent role. This combination of global dominance and regional competition creates a dynamic and evolving market landscape.
Report Coverage:
The research report offers an in-depth analysis based on Material, Sales Channel, Vehicle Type, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
1. Increased adoption of advanced materials like aluminum and composites to reduce weight and improve fuel efficiency.
2. Integration of sensors and electronic components for real-time monitoring and predictive maintenance.
3. Growing demand in emerging markets as vehicle production and sales continue to rise.
4. Shift towards electric and autonomous vehicles will drive innovations in idler arm design and functionality.
5. Rising focus on sustainability will lead to the development of more durable and recyclable idler arms.
6. Expansion of the aftermarket segment due to growing consumer interest in vehicle customization and performance upgrades.
7. Increased collaboration between OEMs and idler arm manufacturers to develop tailored solutions for specific vehicle models.
8. Implementation of advanced manufacturing techniques like 3D printing for more efficient and cost-effective production.
9. Growing emphasis on noise, vibration, and harshness (NVH) reduction will drive improvements in idler arm design.
10. Increasing integration of idler arms with other steering and suspension components for enhanced overall vehicle performance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Idler Arm Market?
What factors are driving the growth of the Automotive Idler Arm Market?
What are some challenges faced by the Automotive Idler Arm Market?
Who are the major players in the Automotive Idler Arm Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Idler Arm Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Idler Arm Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 3,471.85 million → forecast year: USD 4,363.98 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Idler Arm Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Idler Arm Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Idler Arm Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Idler Arm Market Drivers
- 3.3 Automotive Idler Arm Market Restraints & Challenges
- 3.4 Automotive Idler Arm Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Idler Arm Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Idler Arm Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Idler Arm category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Idler Arm Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Idler Arm Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Idler Arm market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Idler Arm Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Idler Arm Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Idler Arm Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Idler Arm (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Idler Arm Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Idler Arm Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Idler Arm Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Idler Arm Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Idler Arm Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Idler Arm Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Idler Arm Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Idler Arm Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Idler Arm Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
