
Market Overview
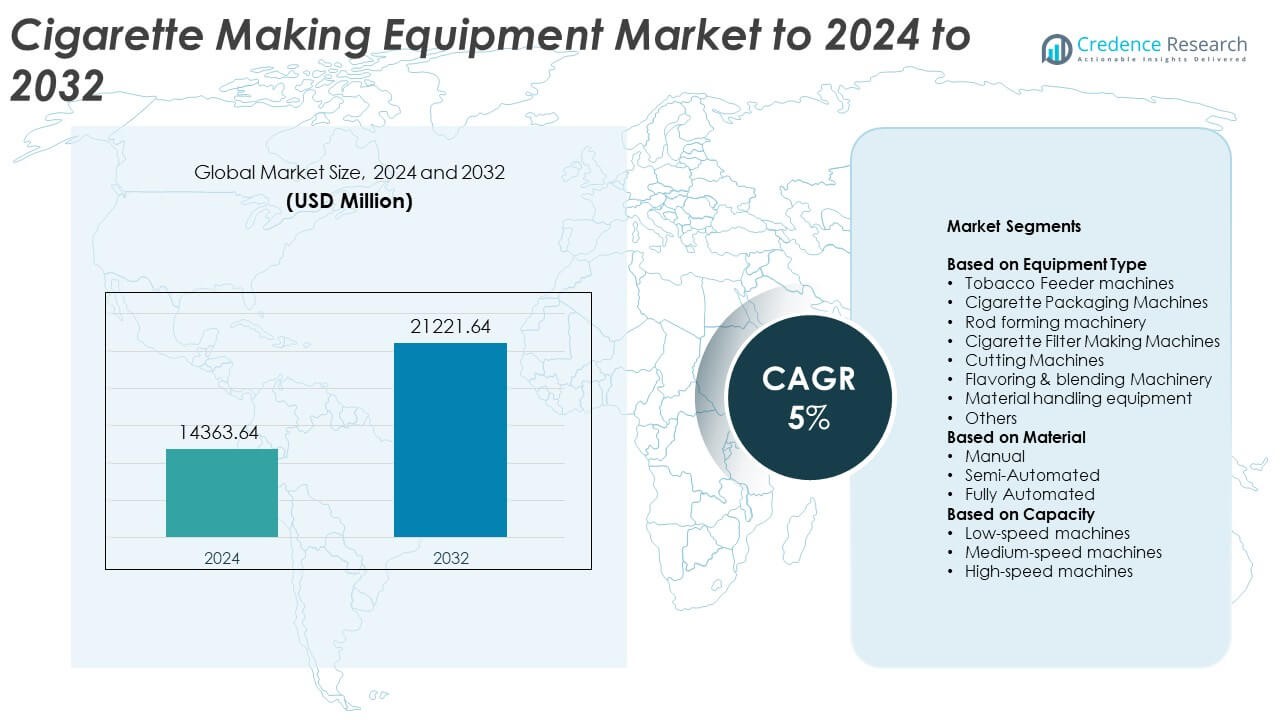
Cigarette Making Equipment Market size was valued at USD 14363.64 Million in 2024 and is anticipated to reach USD 21221.64 Million by 2032, at a CAGR of 5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cigarette Making Equipment Market Size 2024 | USD 14363.64 Million |
| Cigarette Making Equipment Market, CAGR | 5% |
| Cigarette Making Equipment Market Size 2032 | USD 21221.64 Million |
The cigarette making equipment market is dominated by major companies such as Hauni Maschinenbau GmbH, G.D S.p.A., Körber Technologies, ITM Group, Focke & Co., and Molins, known for their advanced manufacturing systems and global reach. These players emphasize automation, digital monitoring, and energy-efficient designs to enhance production speed and precision. Regional competitors including HK UPPERBOND INDUSTRIAL LIMITED, Cipta Bena Kencana, Orchid Tobacco Machinery, and Makepak International are strengthening their presence with cost-effective and region-specific solutions. Asia-Pacific leads the market with a 39% share in 2024, followed by North America at 26% and Europe at 23%, supported by strong industrial infrastructure and modernization initiatives.
Market Insights
- The cigarette making equipment market was valued at USD 14363.64 million in 2024 and is projected to reach USD 21221.64 million by 2032, growing at a CAGR of 5%.
- Growth is driven by increasing adoption of automated and high-speed machinery that enhances production efficiency and precision across global manufacturing facilities.
- Rising integration of smart monitoring, IoT, and energy-efficient designs is shaping new trends, helping manufacturers achieve sustainability and compliance with global standards.
- The market is competitive, with companies focusing on technological innovation, modular designs, and regional expansion to strengthen their positions amid evolving tobacco regulations.
- Asia-Pacific dominates with around 39% share in 2024, followed by North America at 26% and Europe at 23%, while the cigarette packaging machines segment leads the market with nearly 33% share due to high demand for precision wrapping and labeling systems.
Market Segmentation Analysis:
By Equipment Type
The cigarette packaging machines segment dominates the cigarette making equipment market, accounting for around 33% share in 2024. Their leadership is driven by growing demand for high-speed, precision packaging systems that enhance efficiency and ensure product consistency. Automation in wrapping, labeling, and sealing has improved production throughput and reduced operational costs. Increasing investments by tobacco manufacturers to adopt advanced packaging technology for regulatory compliance and brand differentiation further boost this segment’s growth. Meanwhile, rod forming and filter-making machinery are gaining traction with the rise in filtered cigarette production.
- For instance, FOCKE’s latest hinge-lid packer produces 1,000 packs per minute.
By Material
The fully automated segment leads the market with approximately 58% share in 2024, driven by the growing shift toward smart manufacturing and productivity optimization. Fully automated systems streamline cigarette production, minimize human error, and ensure consistent quality standards across batches. Manufacturers increasingly favor automation to meet stringent safety regulations and achieve higher output rates. Integration of intelligent control systems, predictive maintenance, and robotics in cigarette manufacturing has strengthened the dominance of this segment, reducing downtime and enhancing operational efficiency across large-scale production facilities.
- For instance, Hauni PROTOS 80 ER outputs 8,000 cpm (regular) and 7,000 cpm (slim).
By Capacity
High-speed machines dominate the cigarette making equipment market, capturing nearly 61% share in 2024. Their dominance stems from the strong demand among large tobacco producers for machinery capable of exceeding 8,000 cigarettes per minute. These systems enable mass production while maintaining precision in rod formation, cutting, and wrapping. Continuous advancements in servo-driven technology and synchronized control systems have enhanced speed without compromising product quality. The high-speed segment continues to benefit from modernization initiatives in established cigarette factories aimed at improving efficiency and reducing manufacturing costs.
Key Growth Drivers
Rising Demand for Automated Manufacturing Systems Automation remains the primary growth driver in the cigarette making equipment market. Tobacco manufacturers are rapidly adopting fully automated machinery to improve precision, reduce waste, and ensure high-speed production. These systems enhance quality consistency and minimize operational errors. The integration of robotics, sensors, and digital monitoring tools helps producers meet strict global standards. This transition toward smart manufacturing supports higher productivity and cost efficiency, driving strong investment in modern cigarette-making technologies across both established and emerging markets.
- For instance, Körber’s LASERPORT supports makers operating up to 20,000 cpm.
Expansion of Tobacco Production in Emerging Economies Expanding cigarette production capacities across Asia-Pacific, Africa, and parts of Latin America fuels equipment demand. Countries like China, Indonesia, and India continue to host large-scale tobacco manufacturing hubs due to strong domestic consumption and export activities. Local producers increasingly invest in advanced forming, packaging, and filtration machinery to meet growing output requirements. Supportive government policies and lower labor costs encourage manufacturers to establish production plants, strengthening regional demand for efficient and high-capacity cigarette-making systems.
- For instance, Dynamic Tools’ M5000 delivers 4,500 cpm, and the company serves customers in 41+ countries with its various machinery lines.
Technological Advancements in Machinery Design Continuous innovation in cigarette-making technology enhances operational performance and energy efficiency. Modern equipment integrates digital controls, servo-driven components, and IoT-based monitoring systems that optimize performance in real time. These advancements reduce downtime, improve yield, and ensure consistent product quality. Manufacturers increasingly focus on developing modular and flexible systems that accommodate diverse cigarette sizes and flavors. Such innovations enable producers to adapt to changing consumer preferences and comply with international quality and safety regulations.
Key Trends & Opportunities
Shift Toward Sustainable Manufacturing Solutions Sustainability is emerging as a key trend shaping the cigarette making equipment industry. Manufacturers are designing machines that consume less energy, use recyclable materials, and generate minimal waste. The move toward eco-friendly packaging materials also drives innovation in related machinery. Equipment capable of supporting biodegradable filters and low-impact production processes is gaining preference. As global regulations tighten around environmental impact, companies adopting sustainable production technologies are positioned to achieve long-term competitiveness and regulatory compliance.
- For instance, Filtrona’s ECO Tube achieved 90% biodegradation in 90 days.
Integration of Digital and Smart Monitoring Systems The growing adoption of Industry 4.0 solutions presents major opportunities for cigarette equipment manufacturers. Smart monitoring systems equipped with AI and IoT technologies provide real-time data on machine performance and maintenance needs. This digitalization improves operational transparency and predictive maintenance capabilities, reducing unplanned downtime. It also enhances traceability and compliance with regulatory standards. The integration of connected technologies in cigarette-making systems is expected to boost efficiency, precision, and production flexibility across global manufacturing plants.
- For instance, Körber Digital's Uptime solution and other AI-driven predictive maintenance technologies can reduce equipment downtime by up to 50%, lower maintenance costs by 10% to 40%, and increase operational availability by 12%, which helps improve overall productivity.
Key Challenges
Stringent Regulatory Restrictions on Tobacco Production Global tobacco control initiatives continue to challenge market growth. Strict government regulations related to cigarette advertising, packaging, and health warnings directly affect production volumes. Many countries are implementing higher taxes and plain packaging mandates, limiting market expansion opportunities. These regulatory pressures force manufacturers to adapt their production strategies and reconfigure machinery to meet compliance requirements. This ongoing regulatory uncertainty remains a significant hurdle for cigarette-making equipment suppliers worldwide.
High Capital Costs and Maintenance Requirements The high cost of advanced cigarette-making equipment poses a major barrier for small and mid-sized manufacturers. Modern automated and high-speed machinery requires substantial investment, which increases initial setup and operational expenses. Regular maintenance and skilled technical support add further costs. Additionally, integrating advanced technologies such as robotics and IoT systems demands specialized expertise and infrastructure upgrades. These financial and technical constraints often delay adoption in developing markets, restraining overall market penetration.
Regional Analysis
North America
North America accounts for around 26% share of the cigarette making equipment market in 2024. The region’s growth is driven by ongoing modernization of existing production facilities and the adoption of automated packaging and filter-making systems. Major tobacco companies in the United States and Canada are investing in high-speed machinery to maintain efficiency amid tightening regulatory standards. The shift toward sustainable production and reduced labor dependency further supports equipment upgrades. Despite declining smoking rates, consistent demand for premium cigarettes sustains machinery replacement and innovation across established manufacturers.
Europe Europe holds approximately 23% share of the cigarette making equipment market in 2024. The region benefits from advanced manufacturing infrastructure and the presence of leading machinery suppliers in Germany, Italy, and the United Kingdom. Strict quality standards and automation adoption continue to drive technological development. Manufacturers focus on energy-efficient systems to meet environmental regulations under the EU’s sustainability directives. Additionally, modernization of Eastern European facilities and the rising export of high-quality machinery enhance market expansion across both domestic and international markets.
Asia-Pacific Asia-Pacific dominates the cigarette making equipment market, capturing around 39% share in 2024. Strong tobacco production hubs in China, India, Indonesia, and the Philippines contribute significantly to regional growth. The region’s high consumption rates and export-oriented manufacturing drive substantial investment in automated and high-speed production lines. Local producers are increasingly embracing digital control systems and robotics to improve output quality and operational efficiency. Supportive government policies, cost-effective labor, and expanding cigarette exports strengthen Asia-Pacific’s position as the leading market for cigarette-making equipment.
Latin America
Latin America represents nearly 7% share of the cigarette making equipment market in 2024. Growth is supported by modernization efforts in Brazil, Mexico, and Argentina, where tobacco processing and cigarette manufacturing remain key industries. Increasing adoption of semi-automated and fully automated equipment improves productivity and compliance with global standards. Local manufacturers seek cost-effective machinery to meet growing export demands across neighboring markets. However, economic volatility and fluctuating tobacco regulations limit the pace of technological adoption across smaller producers in the region.
Middle East & Africa
The Middle East & Africa region accounts for about 5% share of the cigarette making equipment market in 2024. Rising consumption in countries like Egypt, Nigeria, and Saudi Arabia drives moderate growth. Investments in small to medium-scale production facilities are increasing as regional manufacturers expand output to meet domestic demand. Equipment suppliers are focusing on introducing affordable, energy-efficient systems suitable for developing markets. However, inconsistent regulatory enforcement and limited industrial infrastructure continue to challenge widespread adoption of advanced cigarette-making technologies in the region.
Market Segmentations:
By Equipment Type
- Tobacco Feeder machines
- Cigarette Packaging Machines
- Rod forming machinery
- Cigarette Filter Making Machines
- Cutting Machines
- Flavoring & blending Machinery
- Material handling equipment
- Others
By Material
- Manual
- Semi-Automated
- Fully Automated
By Capacity
- Low-speed machines
- Medium-speed machines
- High-speed machines
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Hauni Maschinenbau GmbH, G.D S.p.A., Körber Technologies, ITM Group, Focke & Co., Molins, HK UPPERBOND INDUSTRIAL LIMITED, Cipta Bena Kencana, Orchid Tobacco Machinery, Makepak International, Dynamic Tools Pvt Ltd., Decouflé, and CBK are the key players in the cigarette making equipment market. The competitive landscape is marked by strong technological advancement, automation, and continuous innovation to enhance production efficiency. Global manufacturers emphasize digital monitoring, modular machine design, and energy optimization to meet diverse production demands. Strategic mergers, partnerships, and expansion into emerging markets help companies strengthen their regional foothold. Growing regulatory pressures and the push for sustainable operations are also driving investment in eco-efficient and precision-engineered equipment.
Key Player Analysis
- Hauni Maschinenbau GmbH
- G.D S.p.A.
- Körber Technologies
- ITM Group
- Focke & Co.
- Molins
- HK UPPERBOND INDUSTRIAL LIMITED
- Cipta Bena Kencana
- Orchid Tobacco Machinery
- Makepak International
- Dynamic Tools Pvt Ltd.
- Decouflé
- CBK
Recent Developments
- In 2025, Dynamic Tools has continued to emphasize and market its range of advanced cigarette packing machines, particularly the HLP2 Cigarette Packing Machine and the Shell and Slide Packer.
- In 2025, Körber Technologies announced a sustainability tie-up with H.B. Fuller. Tests targeted adhesive performance in tobacco production.
- In 2024, Focke & Co. participated at PACK EXPO International 2024. Tobacco packaging capabilities were profiled for attendees.
Report Coverage
The research report offers an in-depth analysis based on Equipment Type, Material, Capacity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow with increasing automation across cigarette manufacturing lines.
- Manufacturers will focus on developing energy-efficient and low-emission machinery to meet green standards.
- Demand for high-speed and precision packaging equipment will rise among global tobacco producers.
- Digital monitoring and predictive maintenance technologies will enhance productivity and equipment life.
- Emerging economies in Asia-Pacific and Africa will drive new machinery investments for capacity expansion.
- Equipment suppliers will introduce modular systems allowing flexible production across cigarette types.
- Global regulations will push innovation in sustainable materials and recyclable packaging equipment.
- Integration of AI and IoT will support real-time process optimization in manufacturing facilities.
- Consolidation among key manufacturers will strengthen global distribution networks and aftersales services.
- Long-term growth will depend on balancing automation efficiency with evolving health and regulatory norms.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cigarette Making Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cigarette Making Equipment Market projected to grow between 2025 and 2032?
Which Cigarette Making Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cigarette Making Equipment Market?
Who are the leading companies in the Cigarette Making Equipment Market?
Which region commanded the largest share of the Cigarette Making Equipment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14363.64 million → 2032: USD 21221.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cigarette Making Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cigarette Making Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cigarette Making Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cigarette Making Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cigarette Making Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cigarette Making Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cigarette Making Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cigarette Making Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14363.64 million → 2032: USD 21221.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cigarette Making Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cigarette Making Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cigarette Making Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cigarette Making Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

