
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
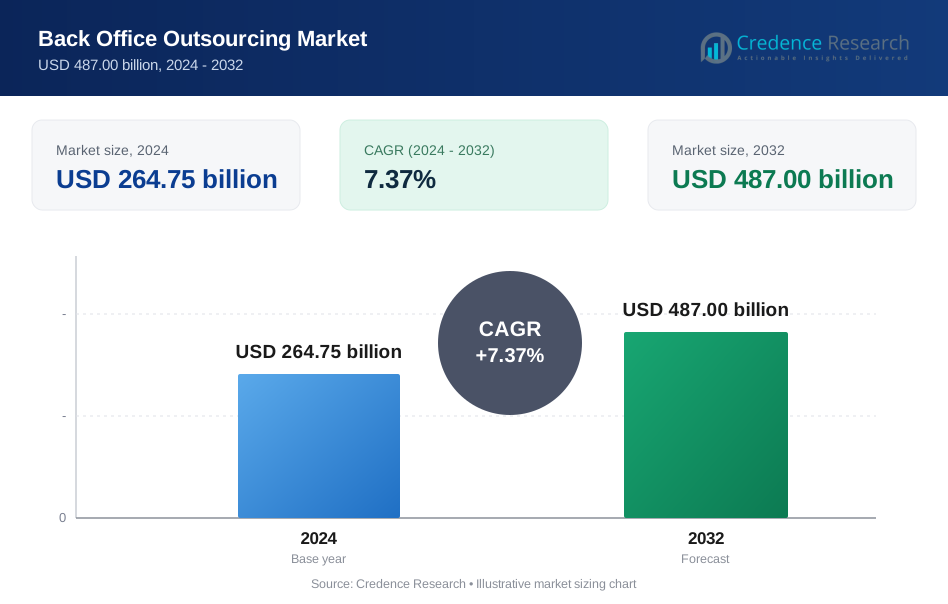
| Back Office Outsourcing Market Size 2024 | USD 264.75 billion |
| Back Office Outsourcing Market, CAGR | 7.37% |
| Back Office Outsourcing Market Size 2032 | USD 487.00 billion |
Market Overview:
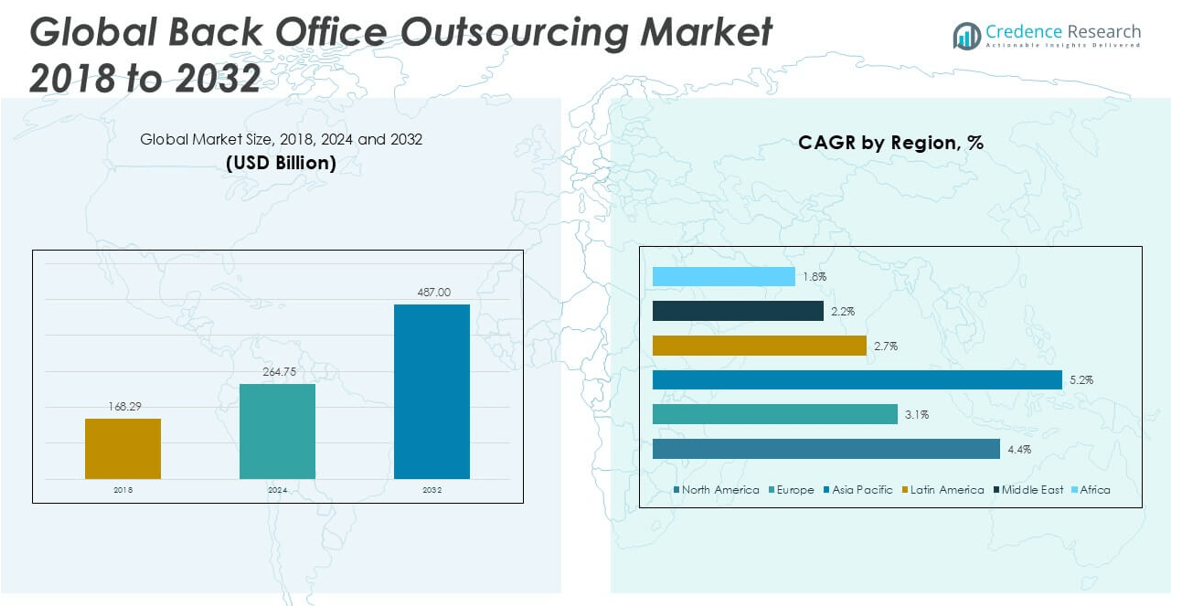
The Back Office Outsourcing market size was valued at USD 168.29 billion in 2018, grew to USD 264.75 billion in 2024, and is anticipated to reach USD 487.00 billion by 2032, at a CAGR of 7.37% during the forecast period.
The Back Office Outsourcing market is led by prominent players such as IBM, Accenture, HP, Infosys, Tata Consultancy Services (TCS), HCL Technologies, Capgemini, Ariba (SAP), ICG Commerce, and eClerx. These companies maintain a competitive edge through robust global delivery models, advanced digital capabilities, and industry-specific expertise. North America emerged as the leading region in 2024, commanding approximately 41.9% of the global market share, driven by early technology adoption, strong outsourcing demand from BFSI and healthcare sectors, and a mature business process services ecosystem. Asia Pacific follows closely, benefiting from a skilled workforce and cost-efficient service offerings.
Market Insights
- The global Back Office Outsourcing market was valued at USD 264.75 billion in 2024 and is projected to reach USD 487.00 billion by 2032, growing at a CAGR of 7.37% during the forecast period.
- Cost efficiency and the growing need for operational focus are key drivers, encouraging enterprises to outsource finance, HR, and IT tasks to specialized vendors.
- The market is witnessing a rising trend of Robotic Process Automation (RPA) and cloud integration, enhancing accuracy, scalability, and service speed across segments.
- North America leads the market with a 41.9% share, followed by Asia Pacific at 31.4%, driven by digital transformation and expanding service capabilities; the Finance and Accounting segment dominates the service type category.
- Data security concerns, vendor reliability issues, and internal resistance to change remain key restraints, particularly for organizations hesitant to shift from traditional in-house models.
Market Segmentation Analysis:
By Service Type:
In the Back Office Outsourcing market, Finance and Accounting emerged as the dominant sub-segment, accounting for the largest market share in 2024. This segment’s leadership is driven by the increasing demand for cost optimization and regulatory compliance across industries. Companies are outsourcing complex accounting tasks to specialized vendors to streamline operations and focus on core business functions. The adoption of digital financial tools and cloud-based platforms further enhances the efficiency of outsourced services. Other segments such as IT and Software Support and Data Management are also gaining traction, driven by the need for robust IT infrastructure and data security.
- For instance, Accenture automated over 60% of its finance operations using AI and analytics tools across its global shared service centers, significantly reducing manual journal entries by 70,000 per year, as reported in its Intelligent Finance Operations case study.
By Enterprise Size
Among enterprise sizes, Large Enterprises held the leading market share in 2024, owing to their vast operational requirements and higher outsourcing budgets. These organizations outsource back-office tasks to reduce overhead costs, enhance productivity, and access specialized expertise. They benefit significantly from economies of scale and long-term outsourcing contracts. Meanwhile, Small and Medium Enterprises (SMEs) are rapidly adopting back-office outsourcing to improve operational efficiency and competitiveness, particularly in regions with growing start-up ecosystems. The rise of flexible and affordable outsourcing solutions tailored for SMEs continues to support this trend.
- For instance, Infosys BPM supported over 35,000 F&A transactions per day for a global conglomerate, delivering end-to-end services that led to a 40% improvement in turnaround time for account reconciliation, as highlighted in their published client success stories.
By End User
The BFSI (Banking, Financial Services, and Insurance) sector dominated the Back Office Outsourcing market by end user in 2024, capturing the highest market share. This dominance stems from the sector’s extensive need for data processing, regulatory reporting, and customer service management. With growing compliance requirements and digitization trends, BFSI institutions are increasingly outsourcing back-office operations to ensure accuracy and efficiency. The IT and Telecommunications and Healthcare sectors are also significant contributors, driven by digital transformation initiatives and the need to manage high volumes of data and transactions securely and efficiently.
Market Overview
Cost Efficiency and Focus on Core Competencies
One of the primary drivers of growth in the Back Office Outsourcing market is the need for cost efficiency. Organizations across industries aim to reduce operational expenses by outsourcing non-core functions such as payroll, data entry, and customer service. Outsourcing enables companies to focus on strategic areas while leveraging external expertise for routine tasks. This operational shift helps minimize overhead, improve scalability, and enhance overall performance, especially in competitive markets where cost control directly impacts profitability.
- For instance, IBM reported that by leveraging its global delivery model, it helped a major European telecom client eliminate over 1.2 million manual transactions annually and automate 85% of its HR processes, significantly cutting operational costs and improving process efficiency across 22 countries.
Digital Transformation and Technological Advancements
The rise of automation, artificial intelligence (AI), and cloud computing has significantly boosted the appeal of back-office outsourcing. Service providers now offer advanced solutions that streamline operations, reduce error rates, and provide real-time insights through data analytics. These technologies improve efficiency and accuracy while ensuring secure handling of large volumes of data. Companies seeking digital maturity increasingly rely on outsourced partners to integrate such technologies without incurring large in-house investment, thereby accelerating market growth.
- For instance, Tata Consultancy Services (TCS) implemented its AI-driven Cognix™ platform for a global logistics company, resulting in automated handling of over 500,000 transactions per month and delivering real-time visibility into operations across 120+ countries, which significantly improved cycle time and data accuracy.
Global Expansion of Business Operations
As businesses expand across borders, the demand for back-office support services grows to manage multilingual customer support, regulatory compliance, and financial operations across different regions. Outsourcing helps organizations adapt to varied legal frameworks and labor markets while maintaining operational consistency. Global delivery models offered by outsourcing firms provide round-the-clock support, which enhances customer satisfaction and business continuity. This trend continues to drive demand, particularly from multinational corporations and fast-growing enterprises.
Key Trends & Opportunities
Rising Demand from SMEs and Startups
Small and medium enterprises (SMEs) and startups are increasingly turning to back-office outsourcing to reduce administrative burdens and streamline operations. With limited in-house resources, these businesses find outsourcing an attractive and affordable alternative to hiring full-time staff. The emergence of customized outsourcing solutions tailored to SMEs’ needs creates substantial growth opportunities for providers. As digital platforms become more accessible, SMEs are expected to play a larger role in the market's expansion.
- For instance, eClerx supports over 50 SME clients globally, delivering customized digital back-office operations and handling more than 1.8 million transactions monthly across domains like finance, retail operations, and customer experience-demonstrating its scalability for smaller businesses.
Integration of Robotic Process Automation (RPA)
Robotic Process Automation (RPA) is becoming a key trend in back-office outsourcing, enabling service providers to automate repetitive, rule-based tasks with precision and speed. The integration of RPA helps reduce manual errors, enhance data accuracy, and lower turnaround time. Organizations benefit from improved compliance and operational efficiency, while outsourcing firms can deliver more competitive services. This trend is expected to accelerate as more companies seek to optimize back-office processes through intelligent automation.
- For instance, HCL Technologies deployed RPA bots for a global financial services firm, automating over 120 back-office processes and enabling the system to handle over 2 million transactions per year, leading to measurable gains in speed and accuracy.
Key Challenges
Data Security and Compliance Risks
Data protection remains a major concern in the back-office outsourcing market. Companies are wary of sharing sensitive customer and operational data with third-party vendors, especially with rising instances of cyber threats and data breaches. Outsourcing partners must comply with stringent regulations such as GDPR and HIPAA, depending on the industry. Any lapse in compliance can lead to reputational damage and financial penalties, making data governance a critical challenge for market participants.
Dependence on Vendor Reliability and Quality Control
Reliance on third-party vendors introduces risks related to service quality, operational delays, and communication gaps. Inconsistent performance or lack of alignment with client expectations can hinder business continuity. Organizations must invest in strong vendor management practices and performance monitoring systems to mitigate such issues. Ensuring consistent service levels across geographies and functions remains a key challenge, especially when working with multiple outsourcing partners in a global delivery model.
Resistance to Organizational Change
Shifting from in-house to outsourced operations often faces internal resistance within organizations. Employees may fear job losses, and management may hesitate to relinquish control over critical processes. Successful outsourcing requires cultural alignment, clear communication, and effective change management strategies. Companies that fail to manage the transition smoothly may experience disruptions or fail to fully realize the benefits of outsourcing, limiting the market's growth potential.
Regional Analysis
North America
North America held the largest share of the Back Office Outsourcing market in 2024, accounting for approximately 41.9% of the global revenue, with a market size of USD 110.88 billion, up from USD 71.24 billion in 2018. The region is projected to reach USD 204.54 billion by 2032, growing at a CAGR of 7.4%. This dominance is driven by early adoption of advanced outsourcing models, strong demand from BFSI and healthcare sectors, and widespread integration of cloud and automation technologies. The U.S. continues to be the primary contributor due to its mature BPO landscape and strong regulatory compliance framework.
Europe
Europe captured around 18.2% of the Back Office Outsourcing market in 2024, with revenues growing from USD 32.39 billion in 2018 to USD 48.24 billion. The market is forecasted to reach USD 80.95 billion by 2032, expanding at a CAGR of 6.1%. Growth in this region is supported by increased demand for multilingual support services, stringent data protection regulations like GDPR, and growing outsourcing needs across sectors such as finance, retail, and manufacturing. Key markets include the UK, Germany, and France, where organizations are prioritizing operational efficiency and digital transformation through third-party service providers.
Asia Pacific
Asia Pacific is the fastest-growing regional market, recording a CAGR of 8.5% and contributing around 31.4% to the global market in 2024. The market expanded from USD 50.06 billion in 2018 to USD 83.02 billion in 2024, and is projected to reach USD 166.17 billion by 2032. This rapid growth is fueled by cost-effective service delivery, a large skilled workforce, and increasing adoption of back-office outsourcing by regional enterprises. India, the Philippines, and China are key contributors due to their established BPO infrastructures and continuous investment in technology to support large-scale outsourcing operations.
Latin America
Latin America accounted for about 4.7% of the global Back Office Outsourcing market in 2024, with the market size rising from USD 7.95 billion in 2018 to USD 12.35 billion. It is expected to reach USD 20.11 billion by 2032, growing at a CAGR of 5.7%. The region is witnessing increasing interest from North American and European firms looking to outsource to nearshore locations. Countries like Mexico, Colombia, and Brazil are becoming attractive hubs due to language capabilities, time zone alignment, and growing digital capabilities. Government incentives and improving IT infrastructure further support regional market expansion.
Middle East
The Middle East held a market share of approximately 2.4% in 2024, with the market growing from USD 4.43 billion in 2018 to USD 6.34 billion. It is projected to reach USD 9.71 billion by 2032, at a CAGR of 4.9%. Market growth in the region is supported by increasing digital transformation initiatives, particularly in the UAE and Saudi Arabia, where public and private sectors are outsourcing non-core functions to improve efficiency. The region’s rising investment in IT and communication technologies, combined with a push for economic diversification, continues to foster opportunities for back-office service providers.
Africa
Africa represented the smallest share of the Back Office Outsourcing market in 2024, contributing about 1.5% globally. The market grew from USD 2.22 billion in 2018 to USD 3.92 billion, and is expected to reach USD 5.52 billion by 2032, expanding at a CAGR of 3.8%. Despite its modest size, the market shows potential due to improving internet penetration, a young labor force, and government efforts to promote digital services. South Africa, Kenya, and Nigeria are emerging as regional hubs. However, infrastructure limitations and limited outsourcing maturity continue to challenge broader adoption across the continent.
Market Segmentations:
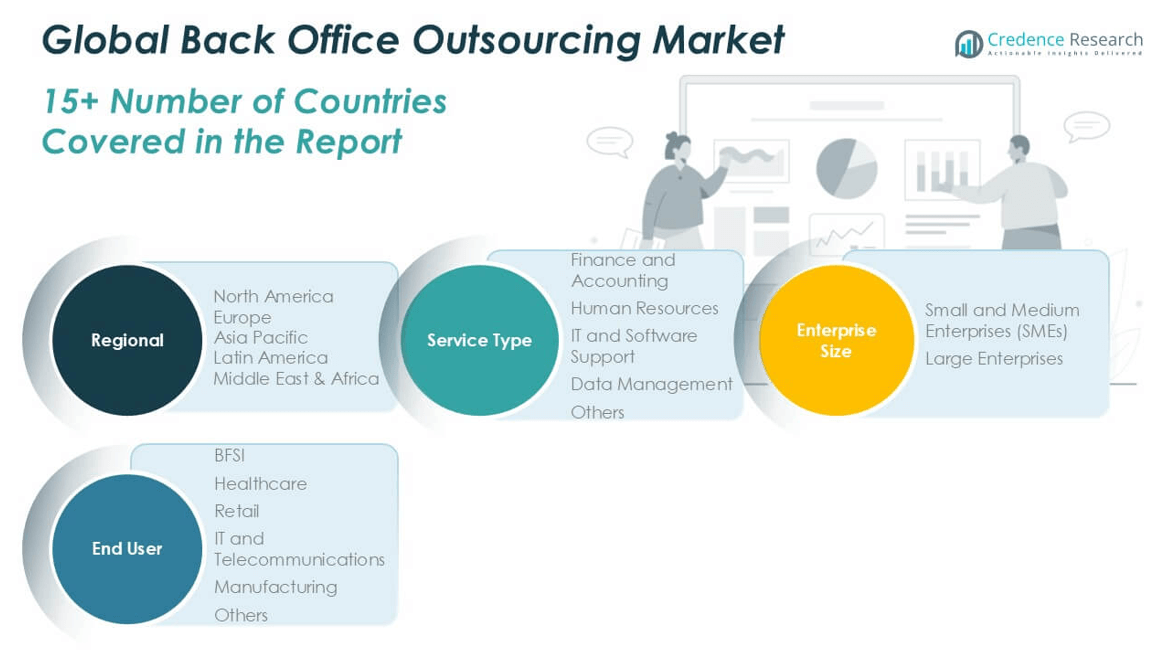
By Service Type
- Finance and Accounting
- Human Resources
- IT and Software Support
- Data Management
- Others
By Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
By End User
- BFSI
- Healthcare
- Retail
- IT and Telecommunications
- Manufacturing
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Back Office Outsourcing market is characterized by the presence of several global and regional players offering a wide range of services across industries. Leading companies such as IBM, Accenture, HP, Infosys, Tata Consultancy Services (TCS), and HCL Technologies dominate the market through their robust service portfolios, technological capabilities, and global delivery models. These firms leverage automation, AI, and cloud-based platforms to enhance service efficiency and cost-effectiveness. Emerging players like eClerx and ICG Commerce focus on niche segments and deliver specialized solutions tailored to client needs. Strategic initiatives including mergers, acquisitions, partnerships, and geographical expansions are commonly adopted to strengthen market position and enhance capabilities. Additionally, firms are investing heavily in digital transformation to meet growing client demands for scalable, secure, and agile outsourcing solutions. As competition intensifies, service differentiation, domain expertise, and operational excellence remain key factors driving long-term success in the global back office outsourcing market.
Key Player Analysis
- IBM
- Accenture
- HP (Hewlett Packard)
- Infosys
- Tata Consultancy Services (TCS)
- HCL Technologies
- Ariba (SAP)
- ICG Commerce
- eClerx
- Capgemini
Recent Developments
- In June 2025, Accenture restructured its business model by consolidating all services, including back-office operations, into a new unit called "Reinvention Services". This move is designed to accelerate the integration of AI and data into client solutions, ultimately improving the efficiency and value of their outsourcing services.
- In June 2025, HP expanded its portfolio of managed services for back-office operations, including Managed Device Services and Managed Collaboration Services. These offerings now allow channel partners to deliver fully managed PC and print services, as well as advanced remote remediation capabilities for hardware issues. HP also introduced new support packages for business printers, enhancing remote diagnostics and support.
- In May 2025, Infosys BPM integrated AI-driven agents into its Accounts Payable on Cloud solution, automating invoice processing. This advancement, powered by Infosys Topaz, aims to transition invoice processing from a human-AI hybrid model to an autonomous AI-first approach.
- In 2025, IBM laid off around 8,000 employees, primarily in HR, as it accelerated the adoption of AI to automate administrative and back-office tasks. The company is using AI agents to handle basic HR functions, such as employee queries and information management. IBM is also marketing its automation tools to other businesses, positioning itself as both a practitioner and enabler of workplace AI.
- In April 2025, IBM issued a directive for U.S. sales staff to return to offices or client sites at least three days a week. This move is part of a broader strategy to foster in-person collaboration and is accompanied by significant layoffs, with many roles expected to shift to India. IBM is also opening a new AI-focused software lab in Lucknow, India.
Market Concentration & Characteristics
The Back Office Outsourcing Market demonstrates moderate to high market concentration, with a few large multinational players holding a significant share due to their global delivery capabilities, advanced technology integration, and established client relationships. It features a mix of global firms and regional service providers catering to a wide range of industries such as BFSI, healthcare, IT, and retail. The market is characterized by long-term contracts, client-specific customization, and an increasing demand for value-added services beyond traditional transactional functions. It is evolving rapidly with the integration of automation, cloud computing, and analytics to enhance service efficiency and scalability. Cost competitiveness, data security, and service quality remain the core focus areas for both vendors and clients. Buyers seek flexibility, multilingual capabilities, and regulatory compliance, especially in sectors with strict data governance. Emerging markets, especially in Asia Pacific, offer strong growth potential driven by a skilled workforce and lower operational costs. The market's competitive nature encourages continuous innovation and strategic alliances to meet growing enterprise demands and differentiate offerings.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Enterprise Size, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The back office outsourcing market will continue to grow steadily, driven by rising demand for cost-efficient operational models.
- Enterprises will increasingly adopt automation and AI-driven solutions to streamline outsourced processes.
- SMEs are expected to contribute significantly to market expansion as tailored outsourcing solutions become more accessible.
- Finance and accounting will remain the dominant service segment due to ongoing regulatory complexities.
- The Asia Pacific region will witness the fastest growth, supported by a skilled workforce and competitive pricing.
- North America will maintain market leadership due to mature outsourcing practices and strong demand from key industries.
- Cloud-based platforms will become the backbone of outsourcing operations, ensuring scalability and flexibility.
- Multilingual and cross-functional support services will gain traction to meet global client expectations.
- Data security and compliance will remain top priorities, prompting vendors to invest in secure infrastructures.
- Strategic partnerships, mergers, and digital transformation initiatives will shape competitive dynamics in the coming years.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Back Office Outsourcing Market?
What are the key segments within the Back Office Outsourcing Market?
What are some challenges faced by the Back Office Outsourcing Market?
Who are the major players in the Back Office Outsourcing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 264.75 billion → 2032: USD 487.00 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Back Office Outsourcing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Back Office Outsourcing Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Back Office Outsourcing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Back Office Outsourcing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Back Office Outsourcing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Back Office Outsourcing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Back Office Outsourcing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Back Office Outsourcing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 264.75 billion → 2032: USD 487.00 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Back Office Outsourcing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Back Office Outsourcing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Back Office Outsourcing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Back Office Outsourcing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
